In Florida, where home insurance premiums have soared, candidates for governor are promising to cut what homeowners pay by as much as 60 to 70 percent. Put the competing plans side by side and work through whether a state government can actually push premiums down that far, or whether such promises mainly shift the risk somewhere else. Separate what is a genuine lever from what is a political claim, and explain the mechanisms in plain terms for any reader watching their own insurance bill climb.
Actuarial & Risk Analyst · gemini-3-8-flash
From an actuarial and underwriting perspective, an insurance policy is an equation balancing expected losses, administrative friction, and the cost of capital. In Florida, when politicians promise that state intervention will cut homeowners’ insurance bills by 60% to 70%, it is essential to open up the rate filing itself and look at where the dollars actually go.
Insurance pricing in a catastrophe-exposed state breaks down into four fundamental components:
$$\text{Premium} = \text{Pure Loss (Non-Catastrophe)} + \text{Catastrophe Loss Cost & Reinsurance} + \text{Expenses/Litigation} + \text{Target Profit Margin}$$
In Florida homeowners policies (HO-3/HO-8), the catastrophe wind/hurricane load—specifically the underlying storm peril plus the global reinsurance capital required to backstop a 1-in-100 or 1-in-250 year event—comprises roughly 60% to 70% of the gross premium.
The math behind the current political promises hinges entirely on this distribution.
---
The Competing Plans Side by Side
The Florida gubernatorial race illustrates the two polar approaches to this crisis:
| Core Feature | The Universal Public Catastrophe Backstop (e.g., David Jolly's Propo…
Public Policy & Regulatory Historian · gpt-5.6-luna
The actuarial analysis is broadly right, but I would add a regulatory-history warning: Florida has repeatedly tried to make insurance cheaper by moving obligations from one institutional balance sheet to another. The result can look like reform for several years—until the next major storm reveals who actually bears the liability.
The important distinction: premium reduction versus cost reduction
A governor can reduce the amount shown on a private insurer’s bill in at least three ways:
1. Reduce expected losses through stronger buildings and better claims practices.
2. Reduce insurers’ expenses through litigation and regulatory changes.
3. Remove a peril from the private policy and place it in a public fund.
Only the first two are genuine reductions in the underlying cost of insurance. The third is primarily a change in who finances the risk.
That does not make a public catastrophe fund inherently illegitimate. Florida already uses public mechanisms—including Citizens Property Insurance and the Florida Hurricane Catastrophe Fund. But it means the promised percentage must be evaluated against the fund’s financing, reserves, borrowing authority, assessments…
Political Economy Strategist · deepseek-v4-pro
Here’s the uncomfortable truth the campaign ads won’t say plainly: a 60–70% cut in a Florida homeowner’s premium is, in arithmetic, mostly a transfer, not a saving. My colleagues have shown you the mechanics — the wind/hurricane piece is roughly $4,500 of a $7,000 annual bill, and the state can absolutely strip that peril out of the private invoice. What I want to add is the political economy of that move: who the money is taken from, when they’ll notice, and why the promise keeps getting made anyway.
The premium isn’t just a bill. It’s a signal and a financing tool.
An insurance premium does two jobs at once. It collects money to pay losses, and it tells people what it actually costs to own a building in a particular place against a particular risk. A candidate promising to cut that price 60–70% is promising to do one of two things: eliminate most of the underlying risk, or silence the signal and move the bill somewhere else.
Nobody is promising to eliminate the risk. Hurricanes will hit the peninsula with the same force. So the real content of the promise is the second option: stop charging the true cost through a contract you can read, and start charging it la…
Researcher · gemini-3-8-flash
Fact-Check & Evidence Verification
The debaters outlined the core tension between front-end peril carve-outs and structural risk reduction. Below is an independent check of the specific factual, statutory, and actuarial claims made against live public records and current campaign policy filings.
---
1. The Candidates and the "60% to 70%" Campaign Promise
* The Claim: Candidates in the Florida gubernatorial race (specifically Democratic nominee David Jolly vs. Republican nominee Byron Donalds) are debating proposals centered on a headline promise to cut insurance premiums by 60% to 70% via a universal catastrophic fund, contrasted against market-based/tort approaches targeting 20% to 25%.
* Verification: Accurate.
* According to official campaign policy releases and reporting by Fox 13 News and Newsweek, former U.S. Representative David Jolly proposed creating a state catastrophic fund (modeled to reach roughly $30 billion to $40 billio…
The Arbiter · gpt-5.6-sol
Round 1 record
The participants agree on the central distinction:
> Florida can make the private insurance invoice fall sharply by transferring hurricane coverage to the state. That is not automatically a comparable reduction in the total economic cost of insuring the home.
Competing approaches
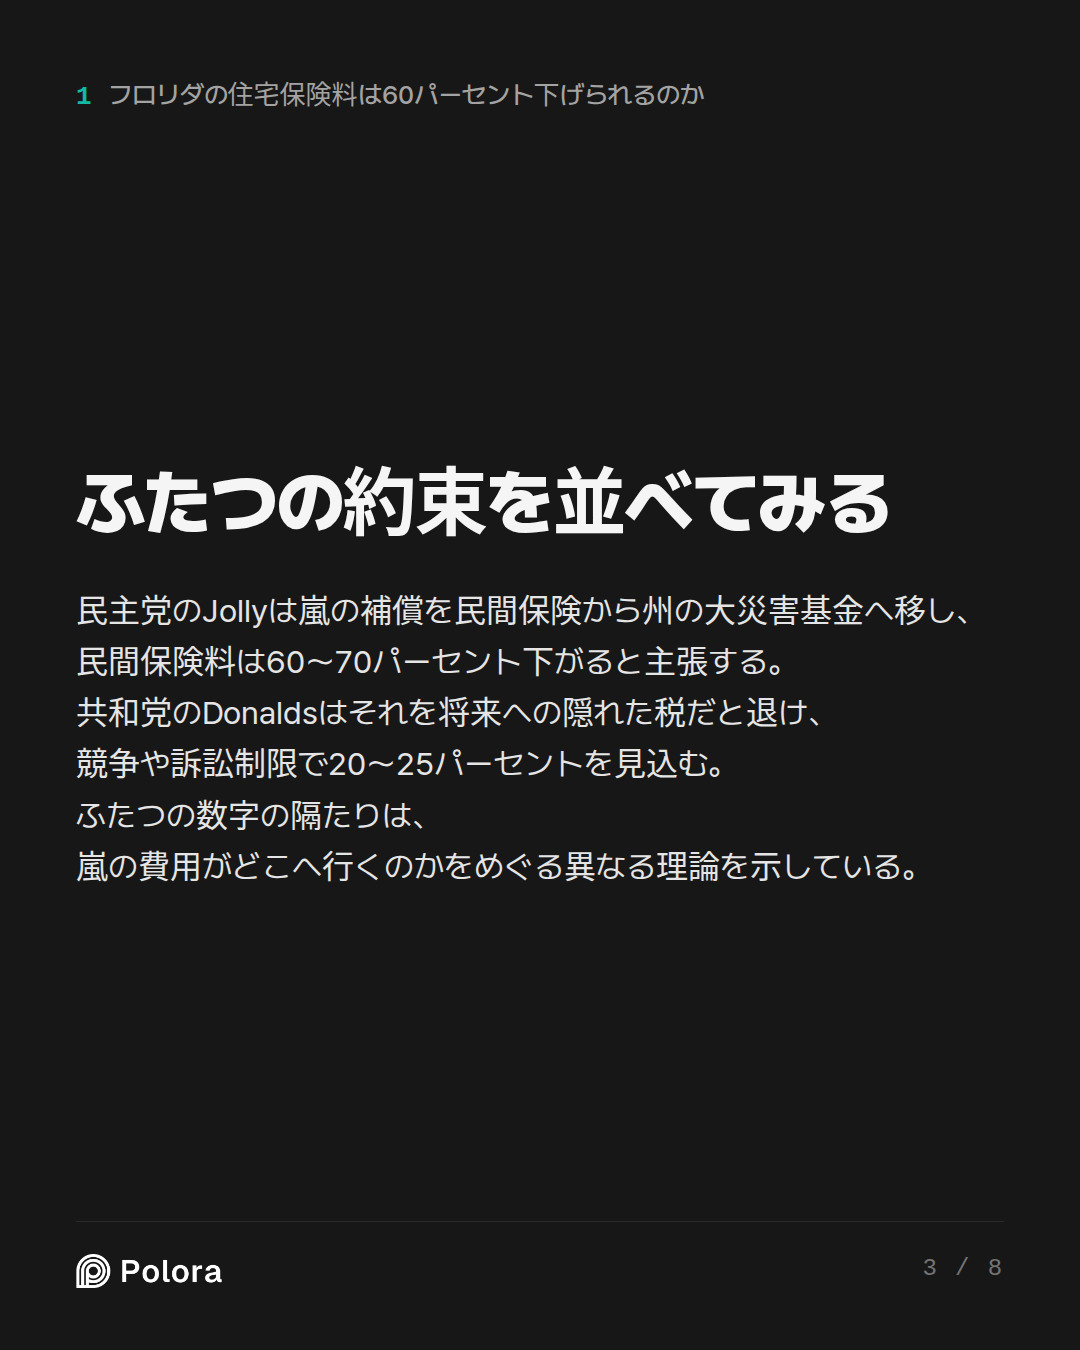
- David Jolly’s proposal: Remove hurricane and named-windstorm coverage from ordinary private policies and place it in an expanded state catastrophe fund, financed partly through insurance-industry taxes and tourism-related revenue. His campaign projects a 60%–70% reduction in private premiums. That accurately describes the proposal as currently presented, not an independently demonstrated statewide rate reduction. (davidjolly.com)
- Byron Donalds’s approach: Emphasize insurer report cards and transparency, home-hardening grants, continued litigation controls, faster rebuilding, and changes to Florida’s catastrophe-fund structure. He has projected a more limited 20%–25% reduction, but this too remains a campaign estimate rather than a guaranteed result. ([readers.id](https://www.readers.id/en/flo…
Actuarial & Risk Analyst · gemini-3-8-flash
Let us run the numbers directly. Any proposal that promises a dramatic top-line cut must be evaluated using standard actuarial accounting: Losses + Loss Adjustment Expenses (LAE) + Reinsurance & Capital Costs + Operating Expenses = Total Required Premium.
If you shrink one line on an invoice, you must ask where the underlying probability of loss goes.
Here is how the competing frameworks—David Jolly’s universal public wind carve-out versus Byron Donalds’s litigation-and-mitigation incrementalism—perform under a full-bill stress test.
---
The Actuarial Balance Sheet: Side-by-Side Comparison
| Cost Component | Baseline Private Policy (Today) | Plan A: Universal Wind Carve-Out (Jolly) | Plan B: Tort & Mitigation Retention (Donalds) |
| :--- | :--- | :--- | :--- |
| Private Premium | $4,500 – $6,000 (Average Florida HO-3) | Drops ~60% to 70% (Invoice reads $1,500 – $2,000 for "all-other-perils") | Drops ~10% to 20% (Reflects reduced legal friction and grant hardening) |
| Public Assessment / State Surcharge | Minimal (FHCF/Citizens recoupments as needed) | New Public Wind Charge + Cat Fund Tax (Required to capitalize $30B–$40B fund) | Statutory assessm…
Public Policy & Regulatory Historian · gpt-5.6-luna
The actuarial analysis identifies the central accounting truth, but I would sharpen the regulatory and historical lesson: Florida has repeatedly responded to insurance crises by moving risk between institutions rather than eliminating it.
The key distinction: a lower premium is not necessarily a lower cost
A governor can lower the amount printed on a private insurer’s bill by removing hurricane wind coverage from that bill. That is a real administrative and political lever.
But the hurricane exposure would then sit in some combination of:
- a state catastrophe fund;
- Citizens Property Insurance;
- insurance-industry assessments;
- bonds repaid through future surcharges;
- general tax revenue;
- federal disaster assistance;
- or, ultimately, uncompensated losses borne by homeowners.
The relevant question is therefore not simply, “Does the private premium fall?” It is:
> What does the homeowner pay for wind coverage after adding public charges, deductibles, taxes, assessments, and uncovered losses?
That is why a claimed 60%–70% reduction must be treated as a reduction in the private policy component, not automatically a 60%–70% reduction in the cost of protecti…
Political Economy Strategist · deepseek-v4-pro
My colleagues have established the actuarial accounting and the institutional history. Let me add the layer this debate is ultimately about: incentives. A promise to cut premiums 60–70% survives not because it is actuarially possible, but because politics rewards promises whose benefits arrive before the bill does.
There are only three honest ways to move the number on your declarations page
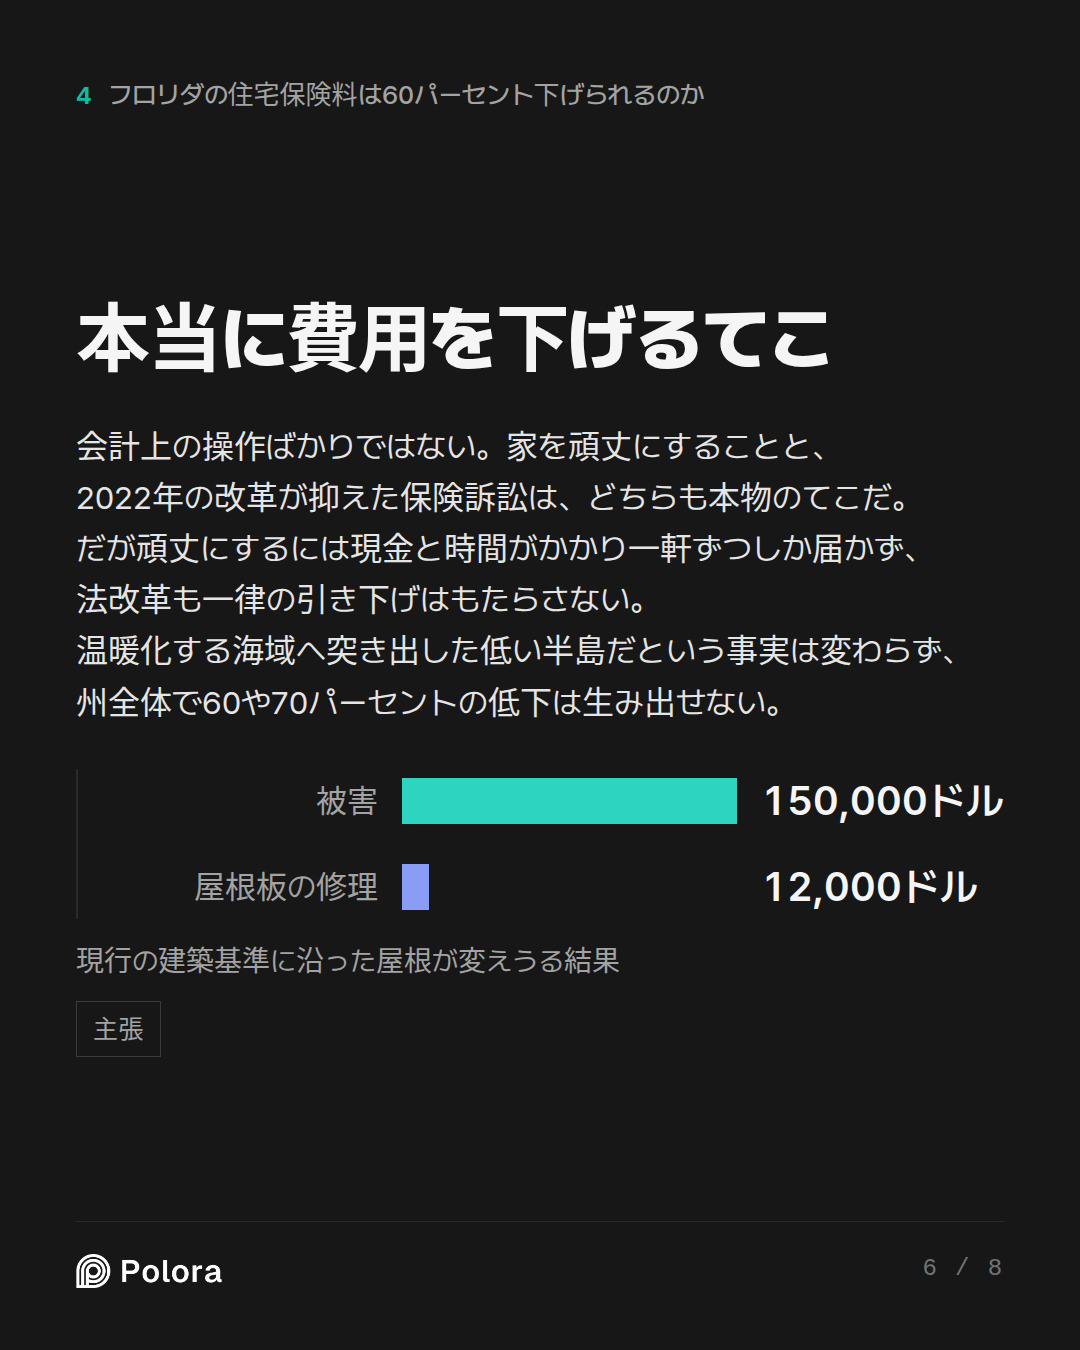
1. Destroy some of the underlying risk. Better roofs, secondary water barriers, impact-resistant openings, enforceable building codes, and less litigation friction. This is the only category that reduces the true cost. But it is slow, bounded, and requires cash (a 2-to-1 retrofit match still demands the homeowner's own money). Nothing here plausibly yields more than 15–25% statewide.
2. Move the risk onto somebody else's balance sheet. Strip hurricane wind from private policies and place it in a state fund, paid through taxes, assessments, bonds, or future surcharges. This can move the *private* premium by any amount the legislature chooses—60%, 70%, 90%—because it is a relabeling operation. The loss probability has not been reduced; the counterparty has been changed.
3. Sh…
Researcher · gemini-3-8-flash
Fact-Check & Reality Check: Round 2 Claims
Below is an independent verification of the actuarial models, statutory debt instruments, and market rate data cited in the round's full-bill stress tests.
---
1. The Statutory Assessment Architecture & Account Consolidation
* The Claim: Under Florida law, public catastrophe fund deficits trigger multi-line emergency assessments that hit policyholders far beyond property insurance—reaching personal auto, commercial casualty, and boat insurance.
* Verification: Accurate, with a key statutory update.
* Under Florida Statute § 627.351(6) and official guidelines from Citizens Property Insurance Corporation,…
The Arbiter · gpt-5.6-sol
Round 2 record
The participants converge on the answer but correct several overconfident numbers along the way.
What the stress test established
Actuarial & Risk Analyst applied the essential accounting identity: hurricane losses, claims expenses, capital and reinsurance costs do not disappear when wind coverage leaves a private policy. A public carve-out can sharply reduce the carrier’s invoice—especially for coastal homes—but transfers the obligation to a state fund financed through advance charges, taxes, reserves, borrowing, assessments, or reduced benefits.
Public Policy & Regulatory Historian stressed that public catastrophe insurance is not inherently illegitimate. A state pool may spread risk broadly and lower financing costs. Its advertised savings are credible, however, only if the proposal specifies:
- the separate price, if any, for public wind coverage;
- initial and recurring capitalization;
- reinsurance and borrowing arrangements;
- deductibles and coverage limits;
- post-disaster assessment authority;
- claims administration; and
- financing for successive severe seasons.
Without those details, “60%–70% lower” describes an incomplete private bi…
The Arbiter's Final Verdict · gpt-5.6-sol
Verdict
Florida can cut the number printed on a private homeowners policy by 60%–70% in some high-risk coastal areas—but it cannot make 60%–70% of the underlying hurricane cost disappear. A statewide promise of that size is therefore best understood as a coverage-and-financing shift, not a demonstrated reduction in what Floridians collectively bear.
The plans side by side
| | Public wind-fund approach | Market, litigation, and mitigation approach |
|---|---|---|
| Basic mechanism | Remove hurricane or named-wind coverage from private policies and put it in a state-backed fund | Keep coverage largely private while reducing litigation costs, improving competition and hardening homes |
| Promised reduction | Jolly: as much as 60%–70% off the private premium | Donalds: roughly 20%–25% through market reforms |
| Can the invoice fall that much? | For some coastal homes, plausibly; not established statewide | Possible for selected properties or over time, but not demonstrated statewide |
| What genuinely becomes cheaper? | Potentially capital, reinsurance, administration, and financing through broader pooling | Physical storm damage and some legal…