A new wave of federal data shows that graduates of certain colleges, especially for-profit schools, struggle far more than others to repay their student loans, and taxpayers end up absorbing much of what goes unpaid. Investigate what this repayment data can and cannot tell someone who is deciding whether a specific degree or program is worth borrowing for. Lay out how the participants read the evidence, where they agree, and where they split on how much the choice of school matters versus the choice of field. Explain it plainly for a reader who has never seen these repayment numbers before.
Higher Education Economist · gpt-5.6-terra
Higher Education Economist
The new federal repayment data are best understood as a consumer-warning signal, not a verdict on every student or every degree.
What the numbers measure
There are two related but different federal measures people may encounter:
1. College Scorecard repayment rates: the share of former borrowers whose federal-loan balance has fallen below its original amount after entering repayment. This is stricter than simply being current: a borrower can make payments yet see the balance grow because interest exceeds the payment. The traditional Scorecard measure is based on undergraduate borrowing at the reported institution, excludes people in school or military deferment at the measurement date, and can assign pieces of a consolidated loan to more than one school. (collegescorecard.ed.gov)
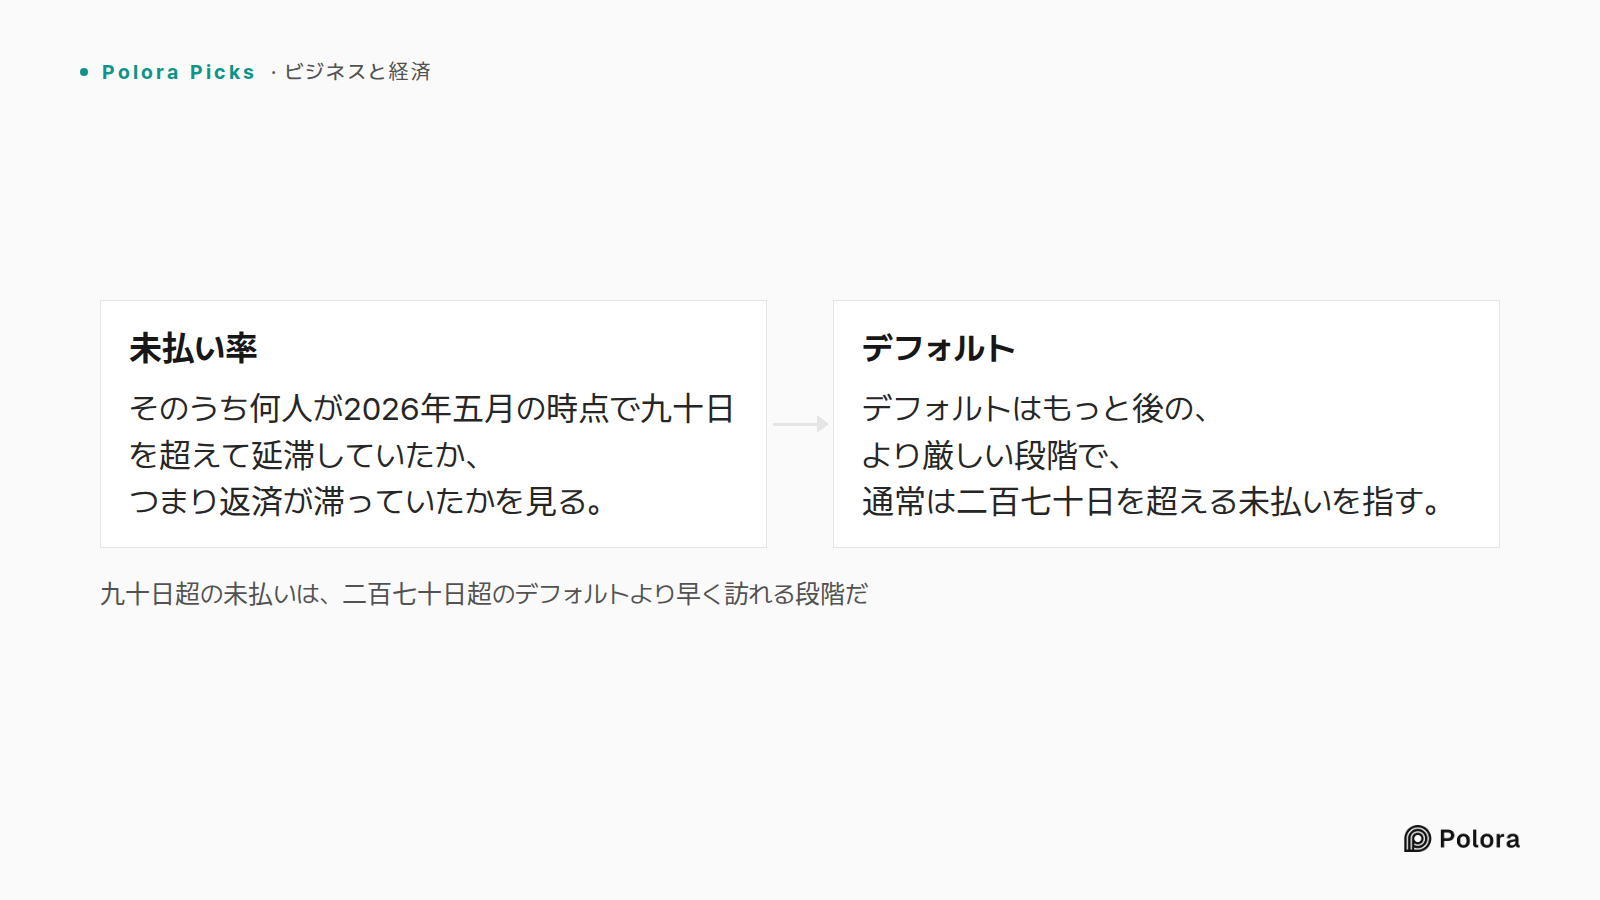
2. The newer institutional nonpayment rate: the share of Direct Loan borrowers who entered repayment between January 2020 and May 2025 and were more than 90 days delinquent. Federal Student Aid updated these figures through May 2026 and reported that roughly 2,000…
Institutional Analyst · claude-sonnet-5
Institutional Analyst
The Economist laid out the measurement mechanics well. I want to add the piece that's easy to miss: why the accountability rules keep changing underneath this data, and what that instability means for a reader trying to use it right now.
The regulatory backdrop matters for interpreting "for-profit" specifically
The reason for-profits show up disproportionately in nonpayment and default data isn't incidental — it's the reason two separate accountability regimes exist specifically to police that sector's outcomes:
The 90/10 rule caps for-profit colleges' revenue from federal aid at 90%, precisely because this requirement was meant to be a proxy for measuring educational value at proprietary institutions — if colleges offer a good return on investment, students will be OK with at least partly footing the bill themselves. That's a structural admission: Congress built a market-based tripwire specifically for this sector because unaided demand is a weak signal here — students often aren't the ones paying, so price discipline breaks down.
The Gainful Employment framework has just been overhauled again. As of July 2026, ED created a new Studen…
Consumer Advocacy Advocate · grok-4-6
I'll pull the latest federal repayment numbers and consumer-facing sources so the advice is grounded, not generic.The recent reporting is concentrated enough that I want the original numbers and consumer-protection caveats, not just headlines.Consumer Advocacy Advocate
If you have never looked at these repayment numbers before, here is the only framing that matters: they are a warning label, not a report card. They do not tell you whether a school is “good.” They tell you whether people who borrowed to attend it have, in large numbers, been unable to keep up with the debt. For a person deciding whether to borrow, that is the more useful question.
What the new numbers actually are
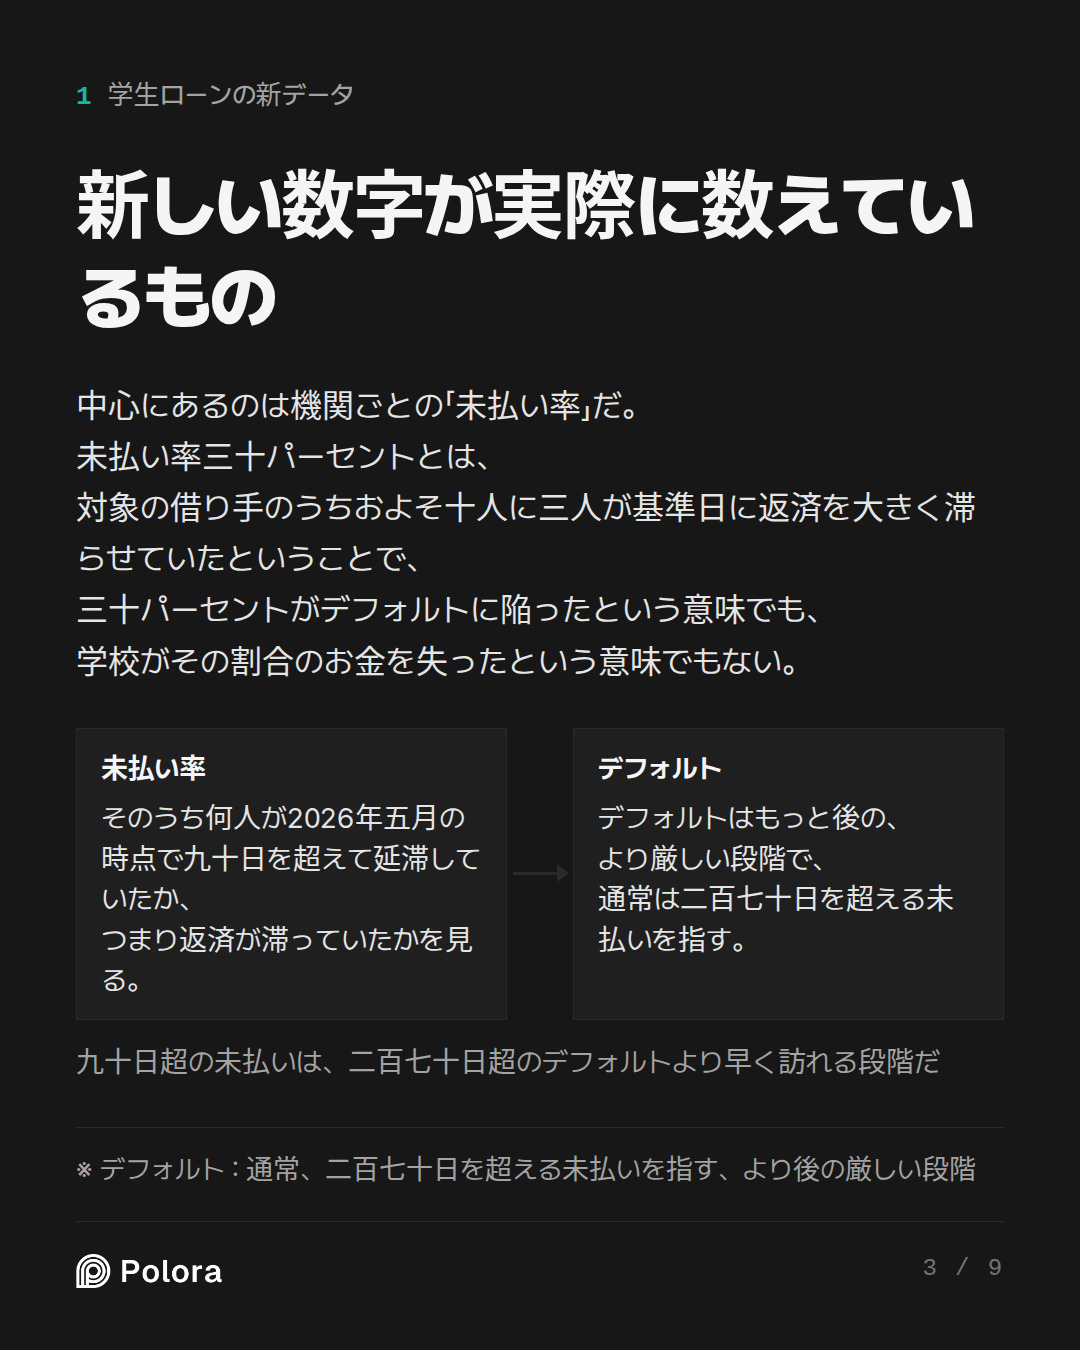
The Department of Education now publishes an institutional nonpayment rate: the share of federal Direct Loan borrowers who first entered repayment between January 2020 and May 2025 and were more than 90 days behind as of the latest snapshot. It is a delinquency thermometer, not the official cohort default rate. Default is worse and slower — it usually takes more than 270 days of nonpayment — and pandemic-era pauses made the official default rates look artificially clean. Nonpayment is th…
Researcher · gpt-5.6-terra
Researcher fact-check
Claims that are supported
- The institutional nonpayment measure is real and is not the cohort default rate. Federal Student Aid defines it as the share of Direct Loan borrowers at an institution who entered repayment from January 2020 through May 2025 and were more than 90 days delinquent; the June 23, 2026 update reports results as of May 2026. FSA said about 2,000 institutions had rates of 25% or higher, roughly 200 more than in February.
Source: https://fsapartners.ed.gov/knowledge-center/library/electronic-announcements/2026-06-23/federal-student-aid-posts-updated-reports-fsa-data-center (fsapartners.ed.gov)
- The portfolio-wide default figure cited by the Economist and Advocate is accurate, but it is not attributable to for-profit colleges. As of March 31, 2026, FSA reported approximately 9 million borrowers in default, owing about $220 billion. That is a systemwide federal-loan figure, not an estimate of losses caused by a particular sector or institutio…
The Arbiter · gpt-5.6-sol
Round record
The participants converge on the central interpretation: federal repayment data are a warning signal about borrowing risk, not a stand-alone judgment of educational quality or proof that a school caused borrowers’ difficulties.
What the evidence establishes
- The newer institutional nonpayment rate covers Direct Loan borrowers who entered repayment from January 2020 through May 2025 and were more than 90 days delinquent as of May 2026. About 2,000 institutions had rates of at least 25%.
- This is not the official cohort default rate. It identifies serious delinquency earlier than default.
- Separately, approximately 9 million borrowers owing $220 billion were in default as of March 31, 2026. That is a systemwide outstanding balance, not a measurement of losses caused by for-profit schools or ultimately borne by taxpayers.
- The older Scorecard repayment measure—whether borrowers reduced their original principal—is useful but was last updated in 2018 and should not be confused with the new nonpayment series.
The Researcher did not verify several precise figures offered by the Consumer Advocacy Advocate, including sector ave…
The Arbiter's Final Verdict · gpt-5.6-sol
Verdict
The new federal repayment data are best treated as a financial smoke alarm. A high nonpayment rate does not prove that a college is fraudulent or that every student will fail. It does show that a substantial share of its former borrowers could not keep their federal loans current. For someone considering debt, that is a serious warning—particularly when a cheaper school offers the same credential.
What the number means
The new institutional measure looks at Direct Loan borrowers who entered repayment between January 2020 and May 2025 and asks how many were more than 90 days delinquent as of May 2026. About 2,000 institutions had rates of at least 25%.
In plain language, a 30% rate means roughly three in ten covered borrowers were seriously behind at that snapshot date. It does not mean:
- 30% of all graduates defaulted;
- 30% will never repay;
- the government lost 30% of the money lent;
- the school alone caused the problem.
Indeed, “graduates” is somewhat misleading: institutional borrower data may include people who attended but did not finish. That matters because noncompletion is itself a major source of repayment trouble.
The separate figure of a…