대개 물건을 들여오는 기업이 자기 나라 세관에 냅니다. 최근 미국 관세에서는 외국 판매자가 값을 거의 내리지 않아, 부담이 미국 안에서 기업과 소비자에게 나뉘었습니다.
비즈니스와 경제 · 2026-10-03
관세 환급금은 소비자가 아니라 기업에게 돌아간다
2026년 2월 미국 연방대법원은 비상권한법이 대통령에게 관세를 매길 권한을 주지 않는다고 판결했습니다. 백악관이 2025년에 매긴 관세 가운데 가장 폭넓은 것들이 이 법에 기대고 있었습니다. 대부분 나라에서 들어오는 수입품에 매긴 관세와, 마약 밀매를 이유로 캐나다, 멕시코, 중국에 매긴 관세가 여기에 해당합니다. 철강, 알루미늄, 자동차 관세처럼 다른 법에 근거한 관세는 영향을 받지 않았습니다. 판결 자체가 환급을 명령하지는 않았습니다. 환급은 미국 국제무역법원이 따로 내린 명령에서 나왔습니다. 해당 수입분을 그 관세 없이 정산하라고 세관에 지시한 것인데, 정부는 이 명령에 항소했습니다. 세관 자료에 따르면 비상권한법으로 걷은 관세는 약 1,660억 달러이고, 33만 개가 넘는 기업이 냈습니다. 걷은 금액이지, 이미 돌려준 금액이 아닙니다.
정부가 돌려주는 돈은 한 푼도 소비자에게 가지 않습니다. 미국 세관은 이 관세를 통관 서류에 수입자로 이름이 오른 기업, 또는 그 기업이 지정한 당사자에게만 환급할 수 있다고 밝힙니다. 계산대에서 더 비싼 값을 치른 소비자는 정부에 청구할 길이 없습니다. 그래서 일부 소비자는 월마트를 비롯한 소매업체를 상대로 소송을 냈습니다. 기업이 받은 환급금 일부를 소비자에게 돌려줘야 한다고 주(州) 법을 근거로 주장하는 것입니다. 연방 관세법에는 그런 의무가 없습니다. 주 법에 있는지는 법원이 판단할 문제입니다.
정부에 돈을 건넨 쪽과 실제로 주머니가 가벼워진 쪽 사이의 이 틈이, 관세를 누가 내느냐는 질문의 전부입니다. 관세만큼 값을 올렸던 기업이 이제 관세를 돌려받는다면, 손님이 이미 치렀을지도 모를 비용을 돌려받는 셈입니다. 환급은 누가 세관에 돈을 냈는지를 보여 줄 뿐, 누가 그 비용을 떠안았는지는 보여 주지 않습니다.
이 질문이 다시 뉴스에 올랐습니다. 9월 하순 미국과 중국은 서로의 상품 약 300억 달러어치에 대한 관세 인하를 검토하는 절차를 마련했습니다. 이 문서 자체가 관세를 내리지는 않습니다. 이와 별개로 미국은 8월 22일부터 지정된 캐나다산 상품에 50% 관세를 매기고 있고, 9월 29일부터는 지정된 캐나다산 유제품, 포장 맥주, 와인, 배기량 800cc 초과 오토바이의 수입을 막았습니다.
관세는 물건을 사들이는 나라가 걷는 세금입니다. 중국에서 장난감을 실은 컨테이너가 도착하면, 그것을 들여오는 기업이 물건을 받기 전에 자기 나라 세관에 관세를 냅니다. 중국 정부는 아무것도 내지 않습니다. 중국 공장도 보통은 직접 내지 않습니다. 예외는 외국 판매자가 직접 수입자로 등록하는 경우입니다. 관세를 값에 포함해 파는 일부 판매자가 이렇게 하는데, 이때는 판매자가 세관에 직접 냅니다. 그래도 외국 정부가 내는 일은 없습니다.
정치인들이 다투는 '상대 나라가 내느냐'는 질문에는 법적으로 분명한 답이 있습니다. 내지 않습니다. 환급이 그것을 보여 줍니다. 돈이 수입 기업에서 나왔으니 수입 기업에게 돌아가는 것입니다. 진짜 질문은 따로 있습니다. 그 비용이 수입 기업에 머무는가, 외국 판매자에게 되밀려 가는가, 아니면 소비자에게 넘어가는가입니다.
이론상 외국 판매자는 손님을 잃지 않으려고 값을 내려서 관세의 일부를 조용히 떠안을 수 있습니다. 실제로 그랬는지는 관세를 더하기 전의 국경 가격을 보면 확인할 수 있습니다. 2018년과 2019년 미국 관세는 두 연구팀이 각각 따로 살폈는데, 결과는 같았습니다. 대체로 그런 일은 없었습니다. 관세 대상 수입품의 값은 내려가지 않았고, 관세는 거의 고스란히 미국 구매자가 치르는 값에 얹혔습니다.
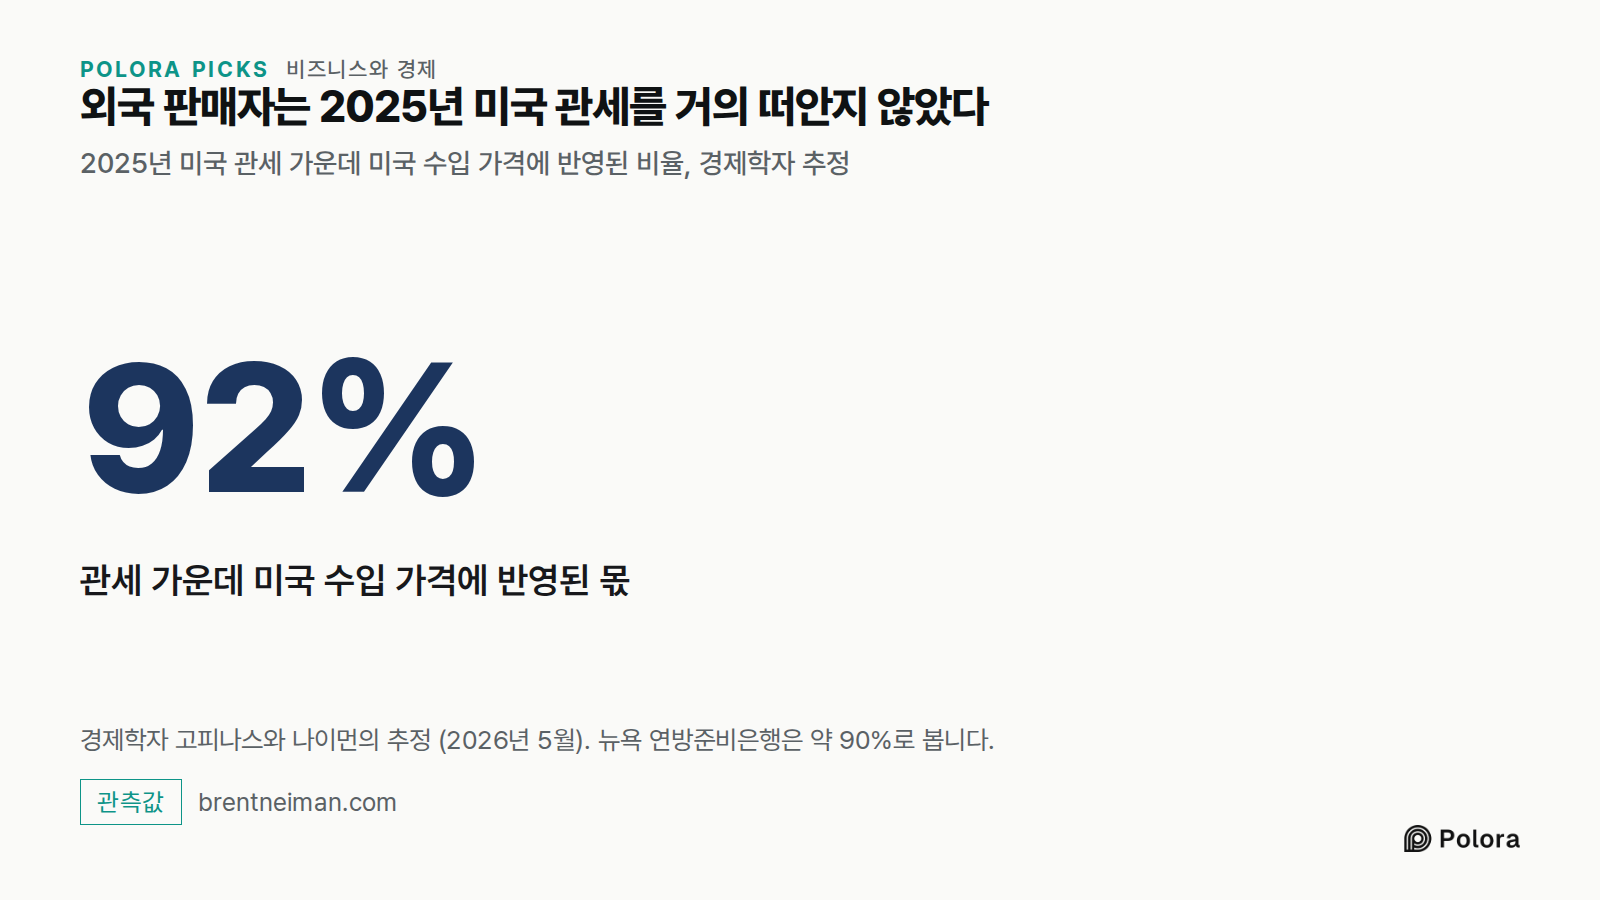
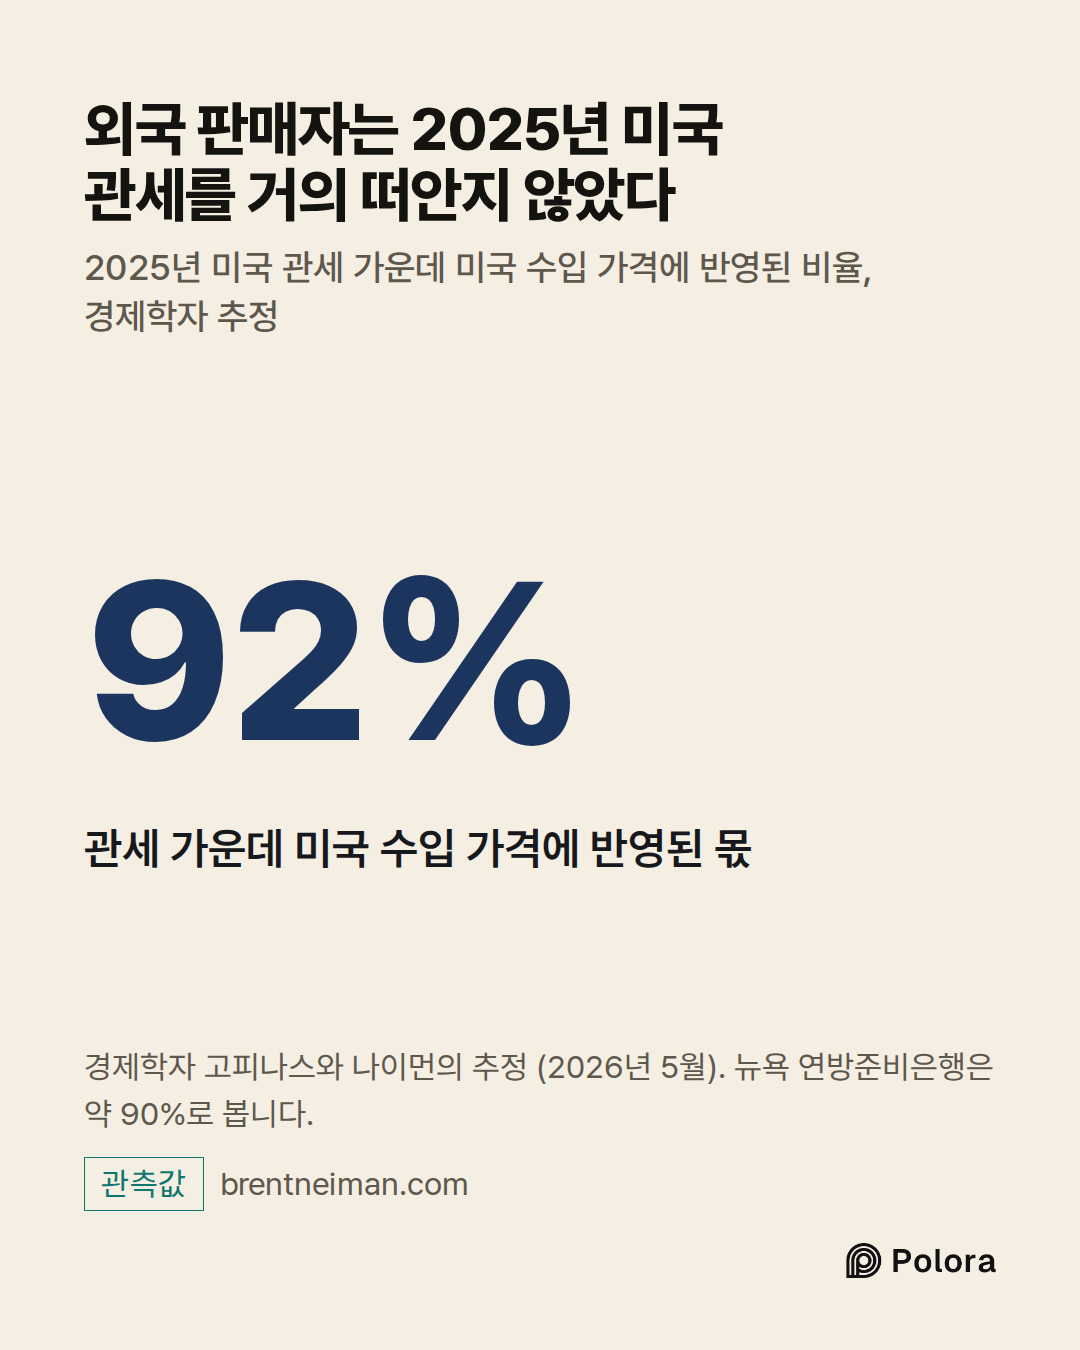
2025년 관세도 다르지 않아 보입니다. 경제학자 기타 고피나스와 브렌트 나이먼은 2026년 5월판 연구에서 관세의 92%가 미국 수입 가격에 반영됐다고 추정합니다. 미국 중앙은행 체계의 일부인 뉴욕 연방준비은행의 경제학자들은 약 90%로 봅니다. 관세가 한 달러라면 그중 약 90센트가 미국 안에 남았다는 뜻입니다.
눈에 띄는 예외가 하나 있는데, 방향이 반대입니다. 2018년 중국이 미국산 농산물에 보복 관세를 매겼을 때는 미국 수출업체들이 실제로 값을 내렸고, 그래서 중국 관세의 일부를 미국 농민이 떠안았습니다. 대표 품목인 콩은 어느 배에 실린 것이든 거기서 거기라, 사는 쪽이 다른 공급처로 쉽게 옮겨 갈 수 있습니다. 고피나스와 나이먼은 2025년에 관세가 가장 크게 오른 일곱 수출국도 살펴봤습니다. 관세를 빼고 본 평균 가격이 내려간 것은 중국에서 온 물량뿐이었고, 2025년 한 해 동안 3.1% 하락했습니다. 물량 전체의 평균일 뿐, 모든 중국 판매자가 값을 내렸다는 뜻은 아닙니다. 이런 사례는 부담을 나누는 비율이 자연법칙이 아님을 보여 줍니다. 사는 쪽이 얼마나 쉽게 다른 곳으로 옮겨 갈 수 있느냐에 달려 있습니다.
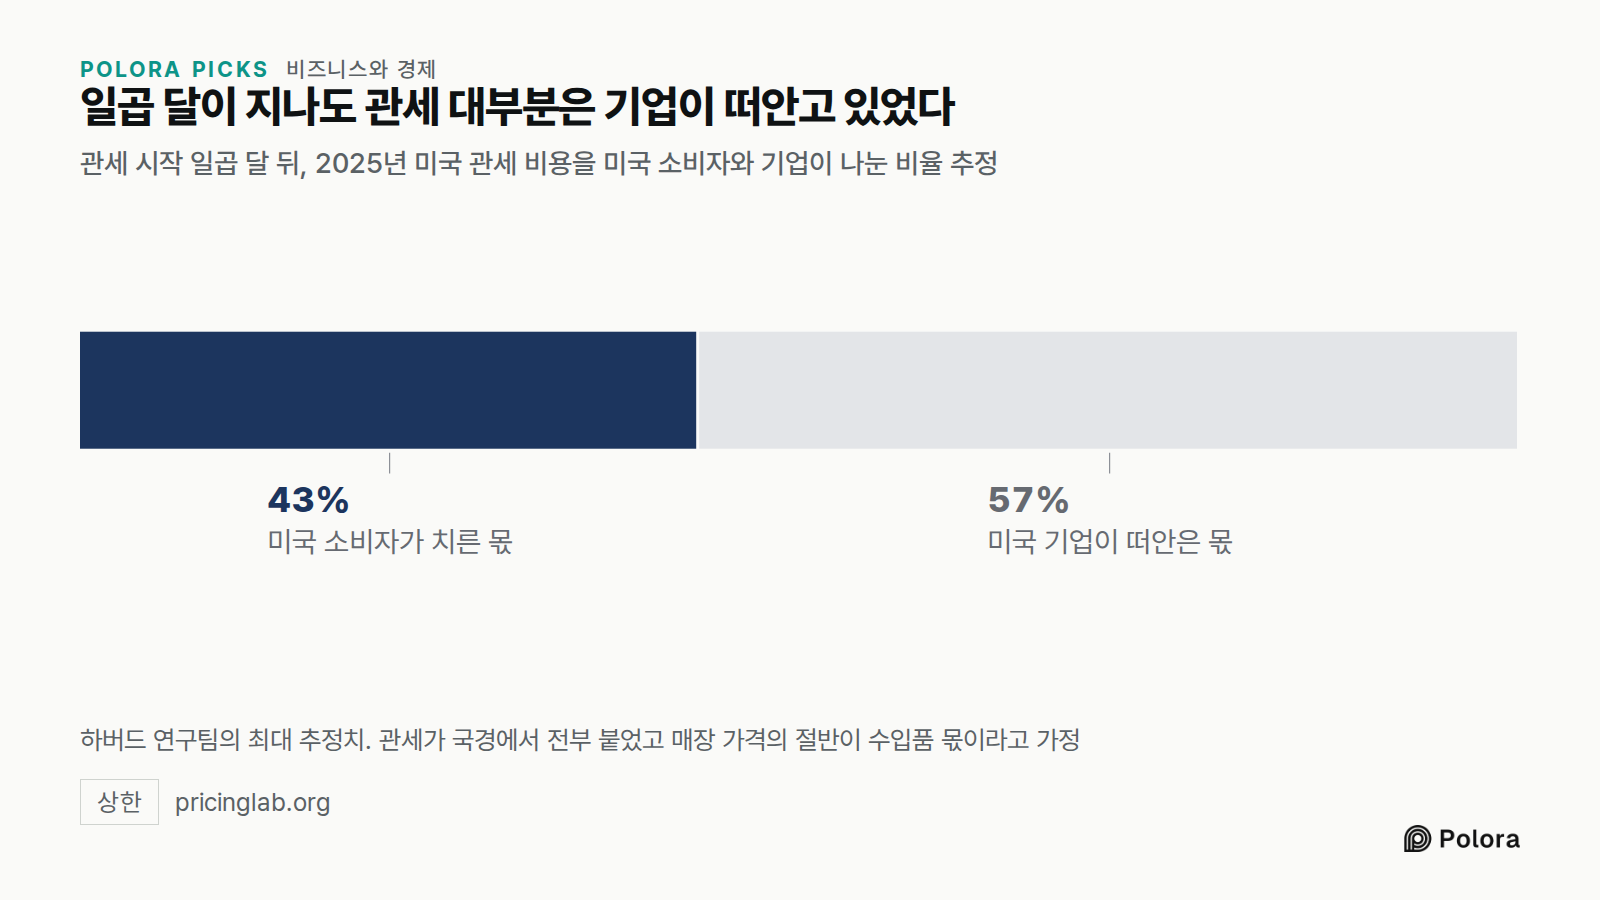
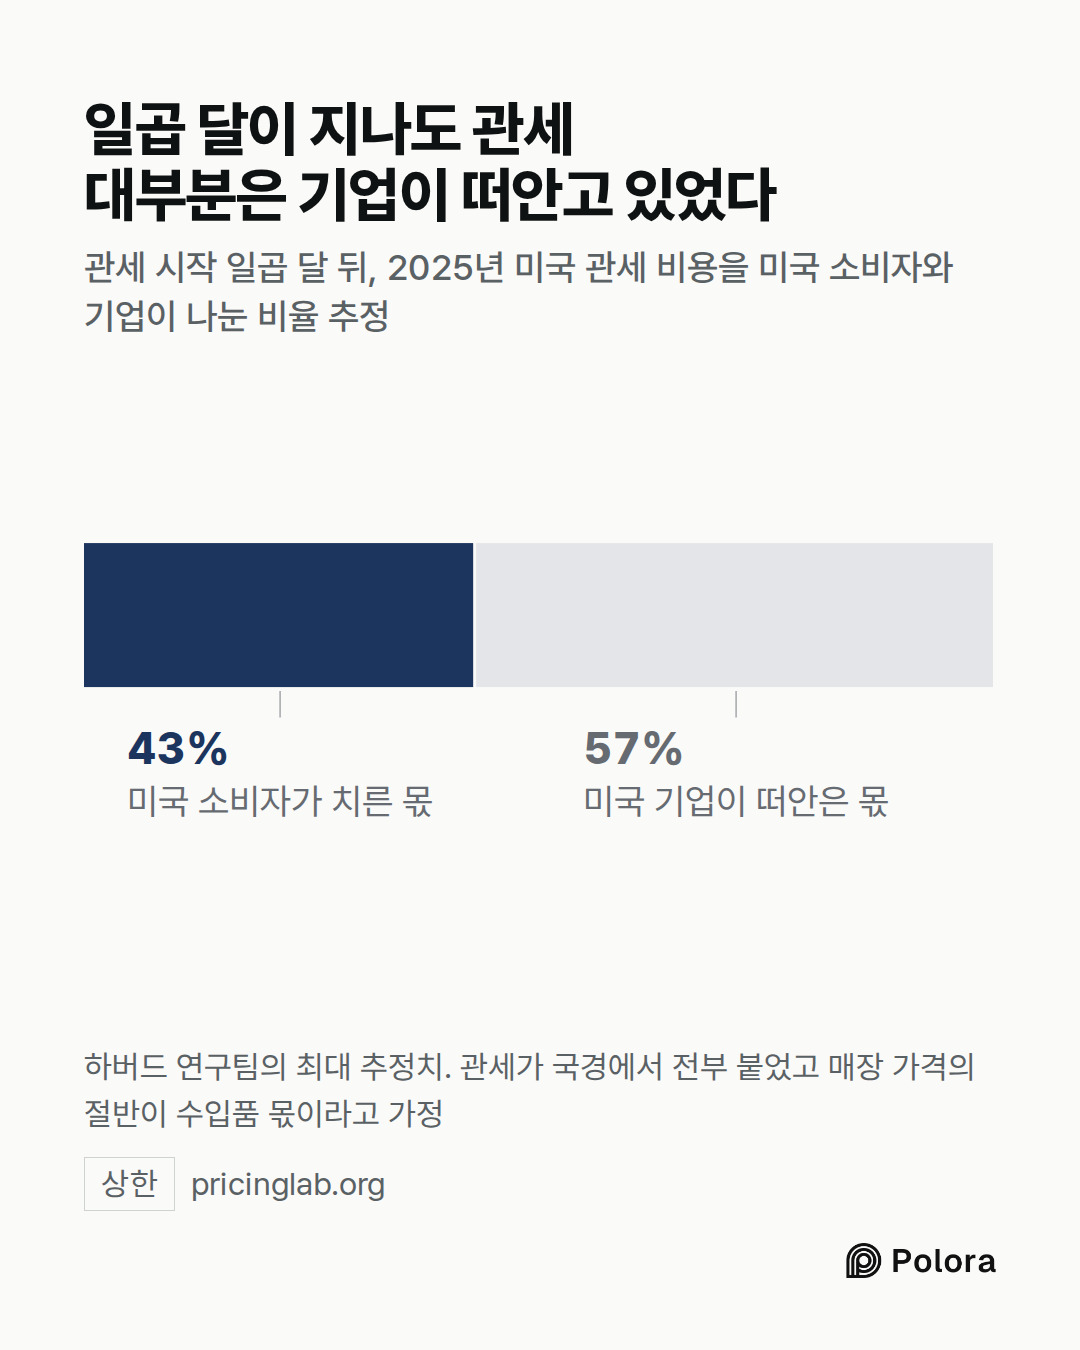
비용이 일단 나라 안으로 들어오면, 물건을 파는 기업과 사는 사람이 나눠 집니다. 처음에는 소비자 몫이 더 작았습니다. 알베르토 카발로가 이끄는 하버드 연구팀은 미국 대형 소매업체의 가격을 매일 추적했는데, 2025년 관세가 시작되고 일곱 달이 지난 시점에 매장 가격에 반영된 것은 관세의 최대 24%였습니다.
이 수치는 소비자 몫을 실제보다 작게 보여 줍니다. 매장이 매기는 값에서 수입품 자체는 일부일 뿐이고, 임대료, 인건비, 운송비가 나머지를 이루기 때문입니다. 연구팀은 관세가 국경에서 전부 더해졌고 매장 가격의 절반이 수입품 몫이라고 가정했습니다. 이 가정 위에서 그때까지 미국 소비자가 관세 비용의 최대 43%를 치렀고, 나머지는 미국 기업이 주로 마진을 줄여 흡수했다고 추정합니다.
소비자가 놓치기 쉬운 방식으로 치른 값도 있습니다. 수입품이 6.2% 오르는 동안 미국산 상품 값도 이전 추세보다 3.6% 더 올랐습니다. 국내 제조업체는 수입 부품에 더 많은 돈을 내야 하고, 외국 경쟁 상품이 비싸지니 자기 값도 올릴 수 있습니다. 뉴욕 연방준비은행 연구는 관세가 매장 가격에 미친 효과의 약 삼분의 일이 국내에서 만든 상품을 통해 왔다고 봅니다.
관세 시작 일곱 달 뒤, 2025년 미국 관세 비용을 미국 소비자와 기업이 나눈 비율 추정
첫째는 시간입니다. 수입품은 거의 곧바로 비싸지지만, 미국산 상품의 가격 상승은 오른 비용이 공급망을 타고 번지면서 아홉 달에서 열두 달에 걸쳐 쌓입니다. 뉴욕 연방준비은행 경제학자들은 한 해 전체로 보면 관세의 약 26%가 소비자 가격에 닿는다고 추정합니다. 관세 영향을 덜 받는 상품과 견준 수치라, 전체 물가 상승률에 대한 예측은 아닙니다.
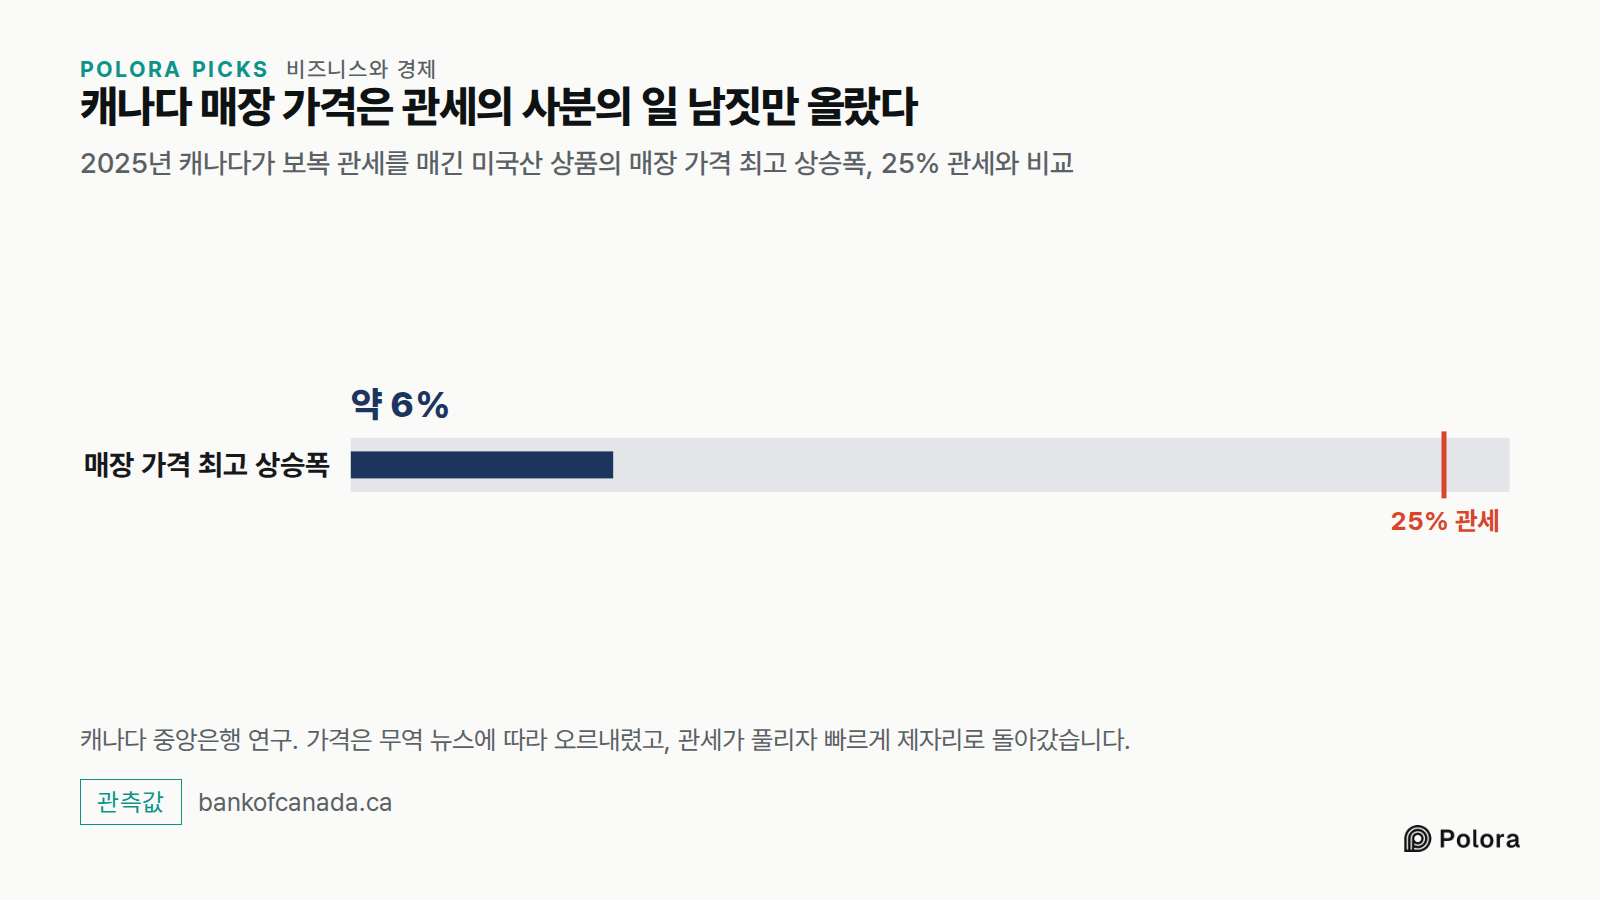
둘째는 기대입니다. 관세가 다음 달이면 사라지리라 보는 가게는 가격표를 새로 붙일 이유가 별로 없습니다. 캐나다가 좋은 예입니다. 2025년 캐나다가 미국산 상품에 보복 관세를 매겼을 때, 캐나다 중앙은행 연구에 따르면 해당 상품의 매장 가격은 최고 약 6% 올랐습니다. 25% 관세의 사분의 일 남짓입니다. 가격은 무역 뉴스에 따라 오르내렸고, 관세가 풀리자 빠르게 제자리로 돌아갔습니다.
셋째는 의외로 단순합니다. 진열대에 관세 때문이라고 적혀 있느냐입니다. 같은 캐나다 연구에서 매장이 관세 대상이라고 표시한 상품은 값이 더 많이 올랐습니다. 연구는 이런 양상을 기록했을 뿐 원인을 밝히지는 않았습니다. 이유를 들으면 소비자가 인상을 더 쉽게 받아들인다는 해석이 하나 있지만, 표시에 관한 결과만으로 그것이 증명되지는 않습니다.
2025년 캐나다가 보복 관세를 매긴 미국산 상품의 매장 가격 최고 상승폭, 25% 관세와 비교
관세는 들여오는 나라의 국경에서 매겨지고, 남는 질문은 그 청구서를 나라 안에서 어떻게 나누느냐입니다. 최근 미국 관세에서 외국 판매자에게 되돌아간 몫은 거의 없었습니다. 처음에는 기업이 대부분을 삼켰고, 달이 갈수록 소비자 몫이 커졌습니다. 국내에서 만든 상품도 예외가 아니었습니다.
이 숫자들은 특정한 관세, 상품, 시기를 설명합니다. 모든 경우에 들어맞는 규칙이 아니며, 어떤 관세가 그 비용만큼 값어치가 있는지에 대해서는 아무것도 말하지 않습니다. 그래도 다음 관세 뉴스를 읽는 방법은 알려 줍니다. 어느 나라가 낼지를 묻지 마십시오. 사는 쪽이 공급처를 얼마나 쉽게 바꿀 수 있는지, 관세가 얼마나 오래 갈 것으로 보이는지, 가게가 그것을 가격표에 적을지를 물으십시오.
When a country puts a tariff on imports, who actually pays it?
Alpha · claude-sonnet-5
My reading of the manuscript's core mechanism — and where it needs correction
The piece's central claim — tariff collected at the importer's own border, with the economic burden then splitting empirically among exporter, importer, and consumer — is correct and well-supported. But several specific numbers and attributions need fixing before publication.
The Supreme Court ruling: confirmed, but the piece understates its scope. In a 6-3 ruling, the U.S. Supreme Court held that the International Emergency Economic Powers Act ("IEEPA") does not authorize the President to impose tariffs. This covered both reciprocal tariffs on imports from most countries and the trafficking/fentanyl tariffs on imports from Canada, Mexico, and China related to opioid trafficking. The manuscript's "most of the 2025 tariffs" framing is reasonable, but it should flag — as the checks note — that Section 232 (steel/aluminum/autos) tariffs survived untouched. One correction to the manuscript: the Court's decision was confined to the legal issues and does not address whether or how the Government should refund IEEPA tariffs already paid — the refund obligation came from a *separate* CIT order, not the S…
Beta · gpt-6-sol
The premise stands, but the manuscript is not ready to publish unchanged. The importer of record owes the tariff to customs. That identifies who remits the tax, not who ultimately bears its cost: a foreign seller can accept a lower pre-tariff price, an importing or retail business can accept a lower margin, and buyers can face higher prices. The evidence in the cited U.S. studies points largely to costs borne in the United States, but not to an invariant split.
The most consequential corrections are these:
- The China news hook says a cut has been agreed when the primary document says a cut is still being considered. The September 27 U.S.–China Board of Trade procedures describe dialogue over goods worth *roughly $30 billion on each side*, “with a view toward” reduced tariff treatment. The September 25 White House fact sheet calls these *recommendations*. Neither establishes that tariffs on $60 billion of goods were lowered on September 28. Replace the claimed agreement to cut tariffs with the narrower, documented proposal; verify any subsequent implementing action separately. ([whitehouse.gov](https://www.whitehouse.gov/wp-content/uploads/2026/09/US-China-Board-of-Tr…
Gamma · gemini-3.1-pro
The premise of the manuscript—that a tariff is a tax remitted at the border by the importer, while the actual economic burden is an empirical question of price pass-through—is fundamentally sound. However, I agree with Beta that the manuscript needs critical surgical edits before publication to avoid turning legal complexities into factual errors.
Here is my assessment of the remaining claims and the final verdict on the manuscript's angle:
The Consumer Lawsuits and the Refund Mechanism
The manuscript claims shoppers have sued retailers like Walmart, Costco, and Amazon, noting that "no law requires [passing the refund on], and the cases are still open." This is an accurate characterization of the current legal landscape. Consumers in cases like *Glase v. Walmart Inc.* are relying on state-level unjust enrichment and consumer protection claims, precisely because federal customs law (19 U.S.C. § 1520) dictates that refunds go to the importer of record. There is no statutory mechanism for CBP to refund consumers. The manuscript’s categorical "not one dollar of it goes to shoppers" from the government is correct.
*Source: https://www.cbp.gov/trade/programs-administration/trade-…
Researcher · gemini-3-7-flash
Here is the verification of the specific factual claims, figures, legal mechanisms, and economic studies cited in the manuscript and raised by the debaters.
---
1. Legal and Regulatory Mechanics
Importer of Record and Direct Payment at the Border
* Claim: The importing company (importer of record) pays the tariff directly to customs at the border; the foreign government or exporter does not remit the payment.
* Finding: Confirmed. Under U.S. customs law (19 U.S.C. § 1484 / 19 U.S.C. § 1505), statutory liability to remit duties falls solely on the *importer of record* upon entry of merchandise into U.S. customs territory.
* Caveat: Under "Delivered Duty Paid" (DDP) Incoterms, a foreign seller can register with U.S. Customs and Border Protection (CBP) as a non-resident importer of record and remit the tariff directly. However, this is an administrative vehicle; it does not change the fact that foreign governments pay nothing and that statutory border liability is distinct from ultimate economic incidence.
* Source: U.S. Customs and Border Protection Guidance (cbp.gov…
The Arbiter · gpt-6-sol
Round record
The shared answer is sound: the importer of record remits a tariff to customs, but that does not establish who ultimately bears its cost. Foreign sellers may lower their prices, importing businesses may accept smaller margins, and shoppers may pay more. Alpha, Beta, Gamma and the Researcher agree that the manuscript’s premise stands; their dispute is over how confidently it states particular legal, news and pricing claims. A foreign seller can also serve as a non-resident importer of record, so “the foreign factory never pays customs directly” is too absolute. The May 2026 Gopinath–Neiman paper itself distinguishes legal payment from economic incidence. (brentneiman.com)
Address: https://brentneiman.com/research/GN2.pdf
The clearest factual correction is the China news hook. Beta found, and the Researcher confirmed, that the September 27 U.S.–China working procedures establish a dialogue about *roughly $30 billion of goods on each side*, with a view toward possible reduced tariffs. They do not establish the manuscript’s claimed September 28 agreement to cut tariffs on “$60 billion of each other’s goods.”…
The Arbiter's Final Verdict · gpt-6-sol
The importer of record pays the tariff to customs. Who ultimately bears the cost is a different question. The importer may absorb it in lower profits, pass it on to shoppers through higher prices, or persuade the foreign seller to accept a lower pre-tariff price. A foreign seller can itself be the importer of record, but a foreign *government* does not pay the importing country’s customs bill. (U.S. customs law)
Verdict on the manuscript: its central premise stands, but several claims need correction before publication. Research on the 2018–19 and 2025 U.S. tariffs finds that much of the cost remained with U.S. buyers at the border; it does not establish a fixed split between businesses and shoppers for every tariff. Gopinath and Neiman estimate border pass-through of 81% and 92%, respectively. The retail estimates describe particular goods and periods and depend on stated assumptions—not a universal consumer share. (Gopinath and Neiman; [Cavallo, Llamas and Vazquez](https://www.pricinglab.org/files/TrackingTariffs_Cavallo_Llamas_Vazquez.p…