Do airports make more money from parking and shops than from airlines?
Alpha · deepseek-v4-pro
No, not for most airports — but the question mixes two very different money streams.
Airlines still pay the larger share.
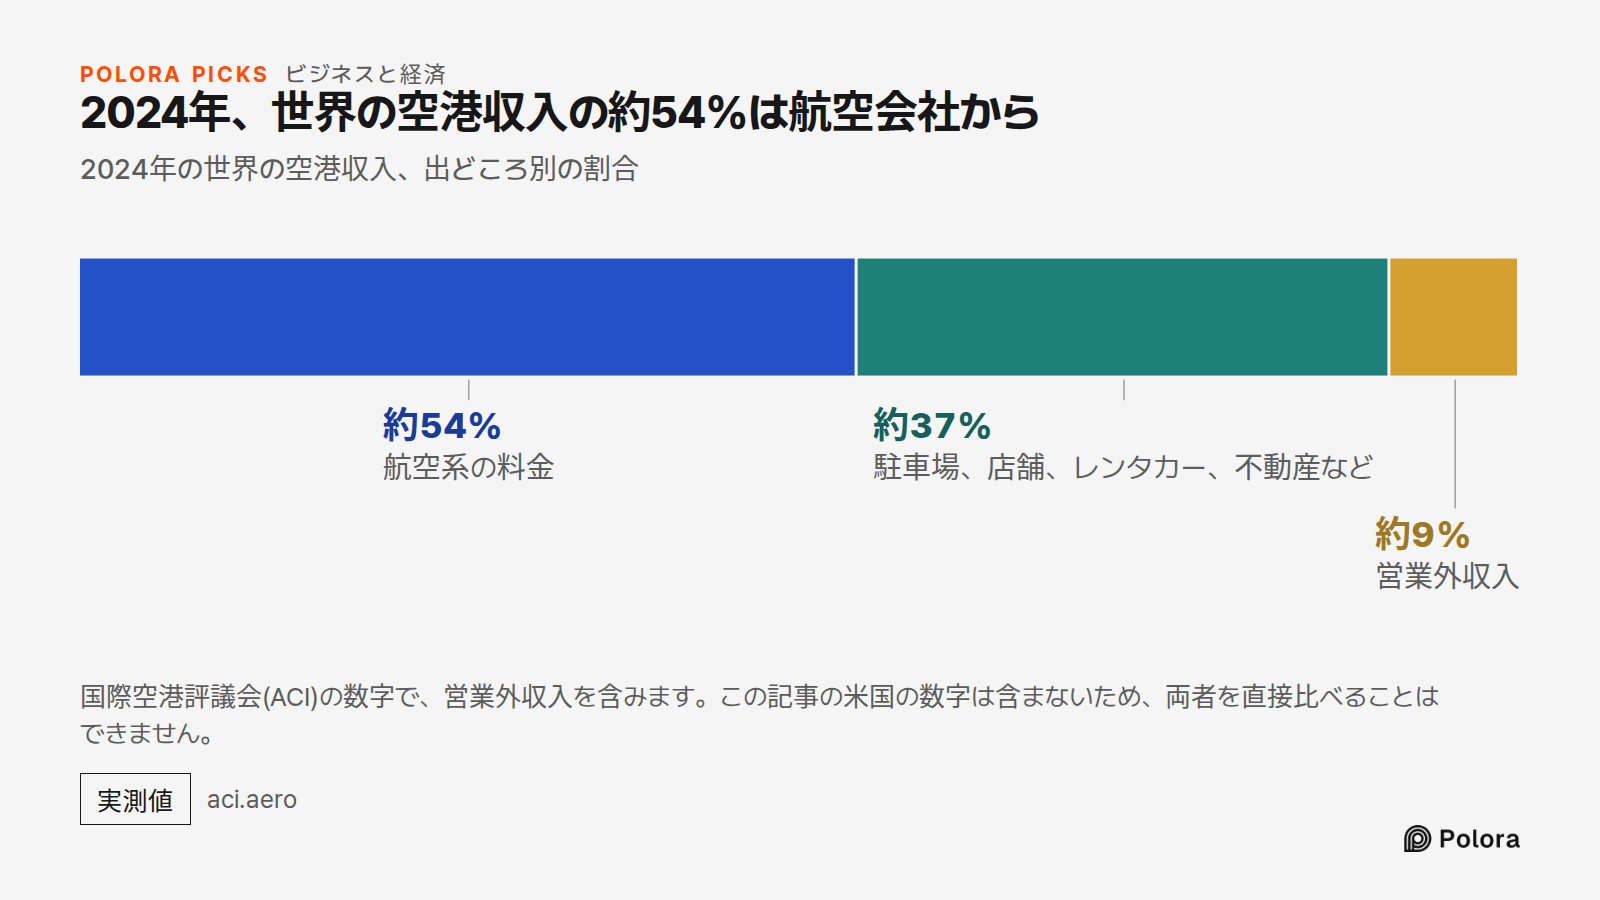
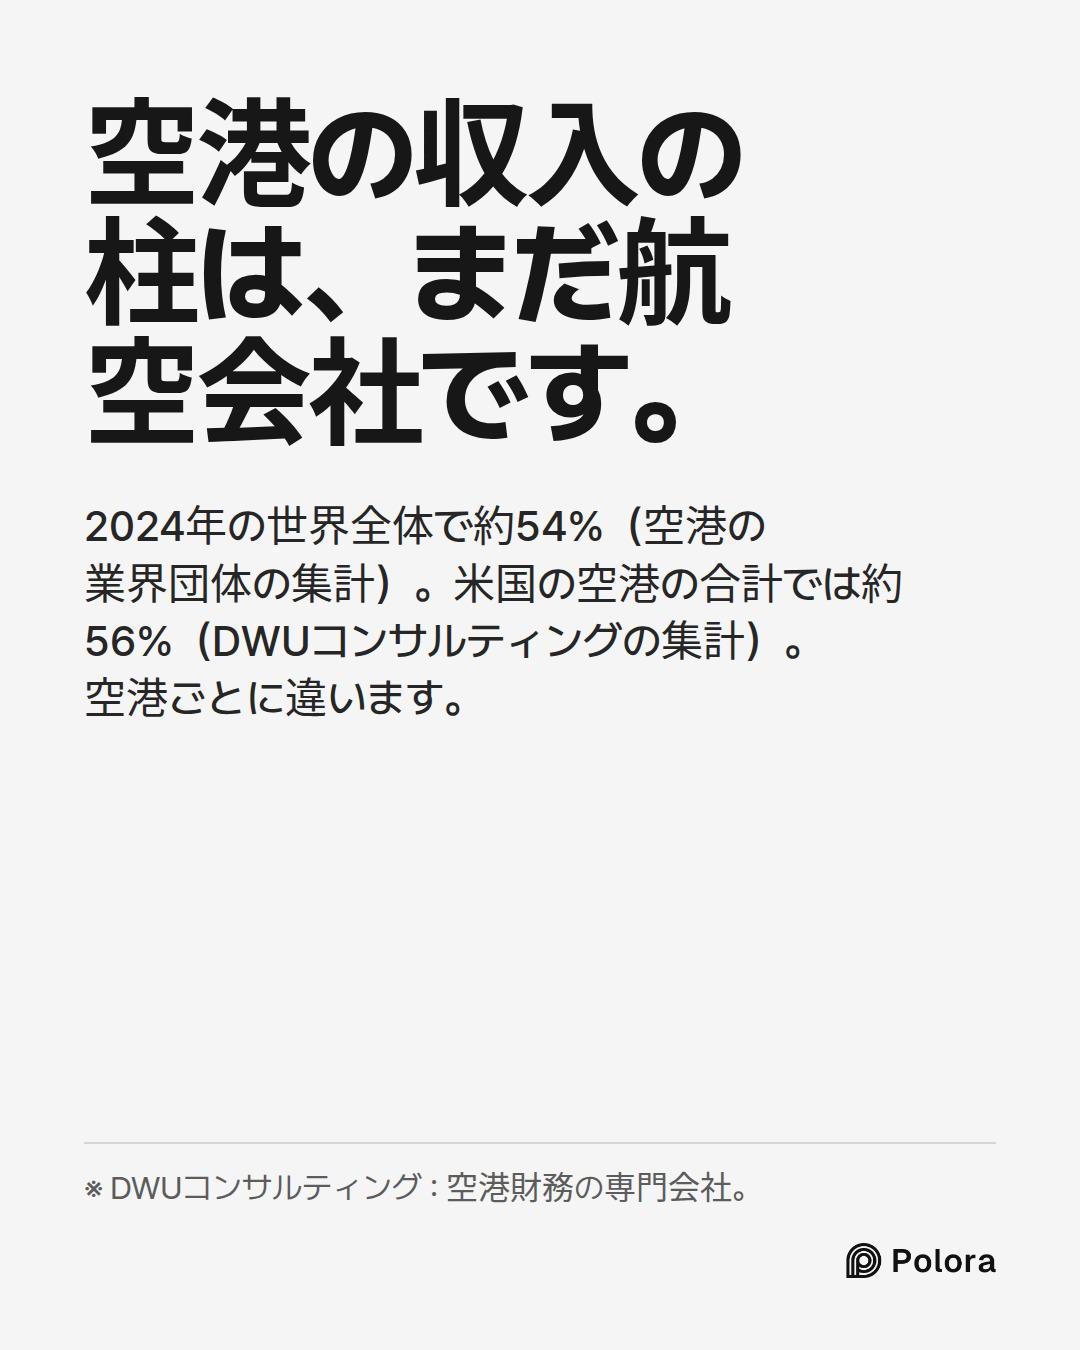
The broad global picture has aeronautical charges at roughly 54% of 2024 airport revenue, with about 37% coming from all non-aeronautical sources and 9% from non-operating income. So even if you lump parking, shops, food, car rental and everything else together, airlines still bring in more.
In the United States the gap is narrower. Adding up FAA filings for fiscal 2025 gives about $19.3 billion from airlines against $15.2 billion from all other operating sources — around 56/44. That is close, but airlines are still the larger of the two.
But parking and shops are not equal partners.
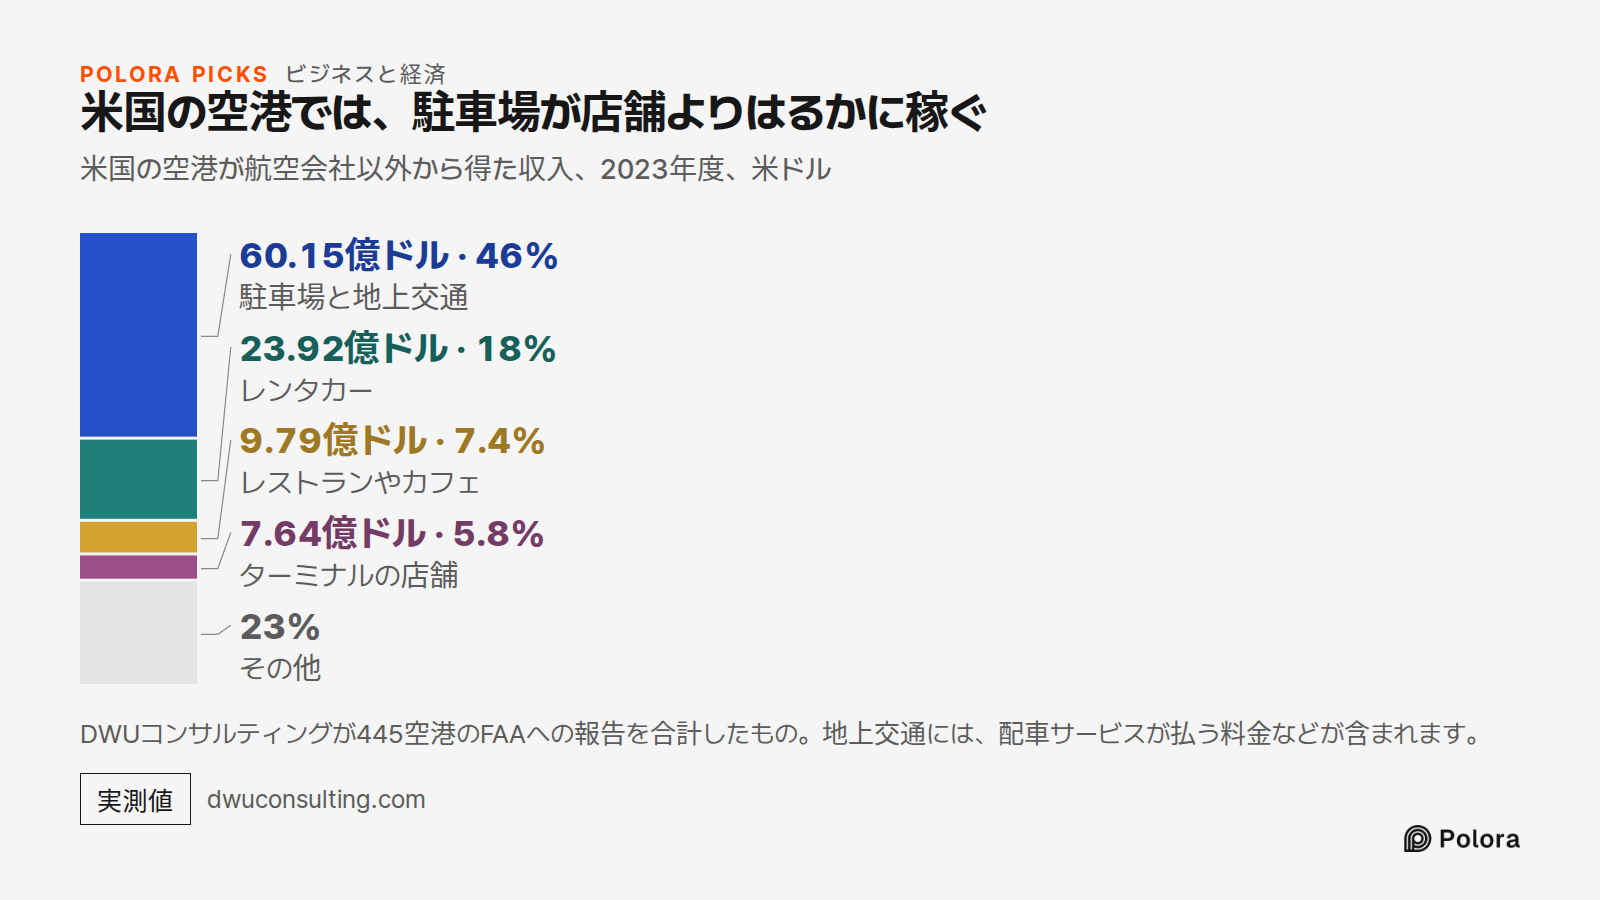
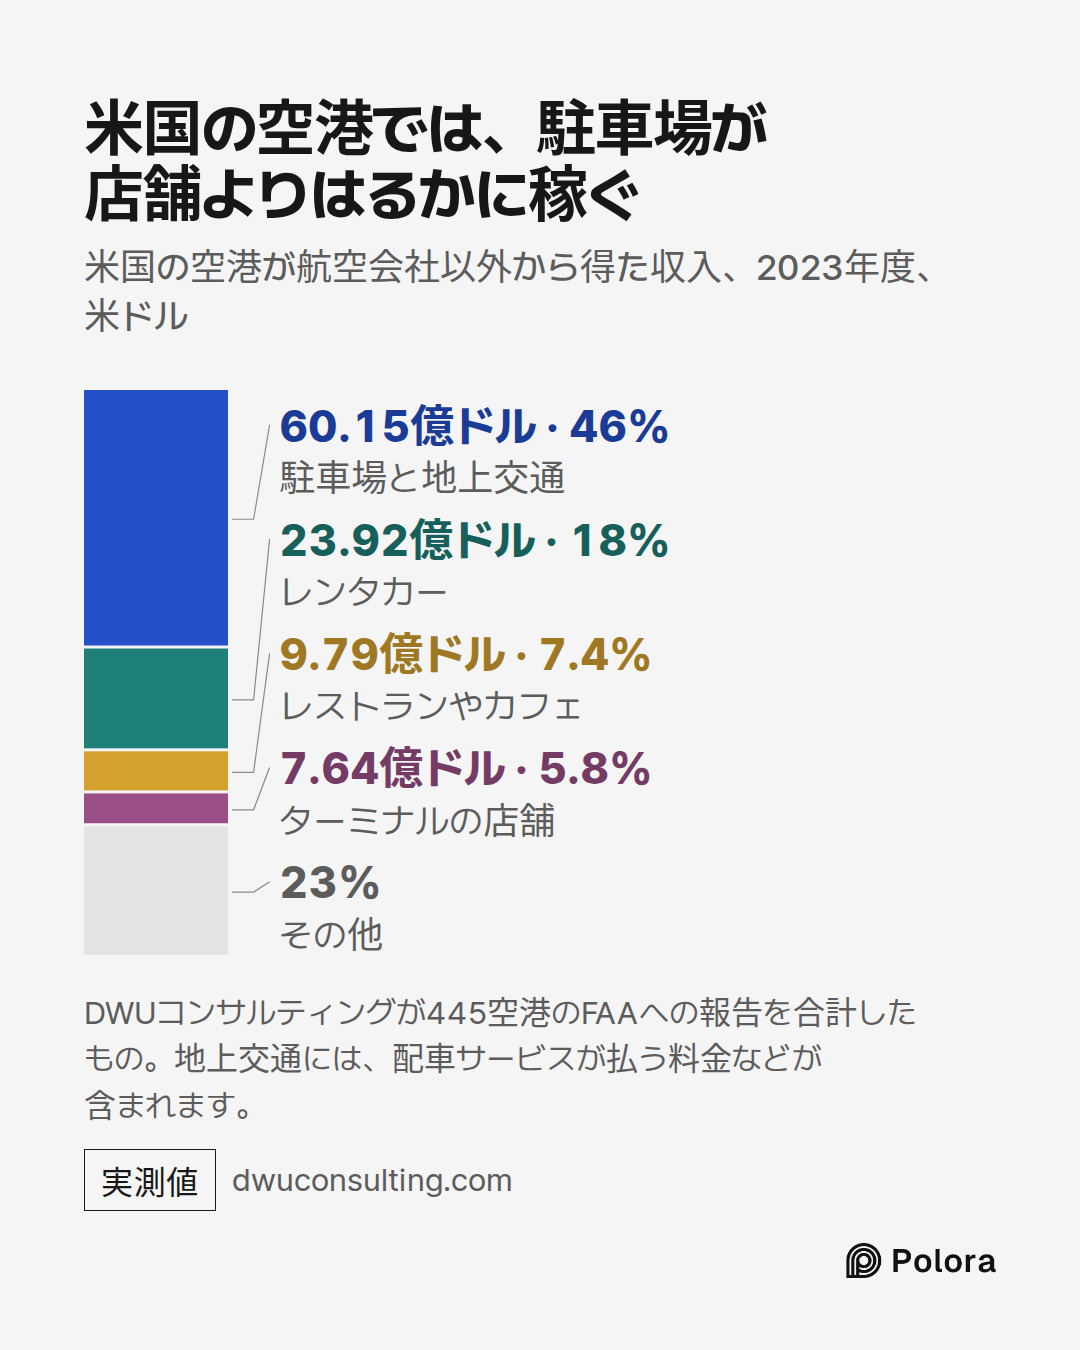
This is where the question goes wrong. In North America, car parking is about 43% of non-aeronautical revenue. Shops are only around 7%, and food and drink about 7.6%. In dollar terms from US figures, parking and ground transportation were roughly $6.0 billion, rental car concessions about $2.4 billion, while terminal shops brought in under $0.8 billion and restaurants under $1.0 billion.
So the real non-airline engine is the car park, not the duty-free bag. If the q…
Beta · gpt-6-sol
Usually no—but “parking and shops” is much narrower than “everything airlines don’t pay.” ACI World reports that aeronautical revenue made up 54% of airports’ total revenue worldwide in 2024, versus 37% from non-aeronautical businesses such as parking, shops, restaurants and car rental. Those figures support the manuscript’s overall answer, not a claim that airlines out-earn *parking and shops at every airport*. (aci.aero)
For the US, DWU Consulting’s aggregation of 417 FAA fiscal-2025 filings puts operating revenue at $19.3 billion aeronautical and $15.2 billion non-aeronautical—roughly 56/44. Its newer breakdown puts parking *and ground transportation* at $6.9 billion and rental cars at $2.5 billion. Neither category is parking alone; nor is all non-aeronautical revenue money paid directly by travellers. The 417 filings were a snapshot extracted on July 21, 2026, not a fixed final national total. The FAA confirms that airports can amend their filings. ([dwuconsulting.com](https://dwuconsulting.com/dwu-ai/us-airport-industry-…
Gamma · gemini-3.1-pro
I agree with the overall premise that airlines pay the larger share at most major airports, though the exact mix depends heavily on the airport's size and agreement structure.
To clear up a few remaining verification points from the research brief:
1. Heathrow 2025 Figures:
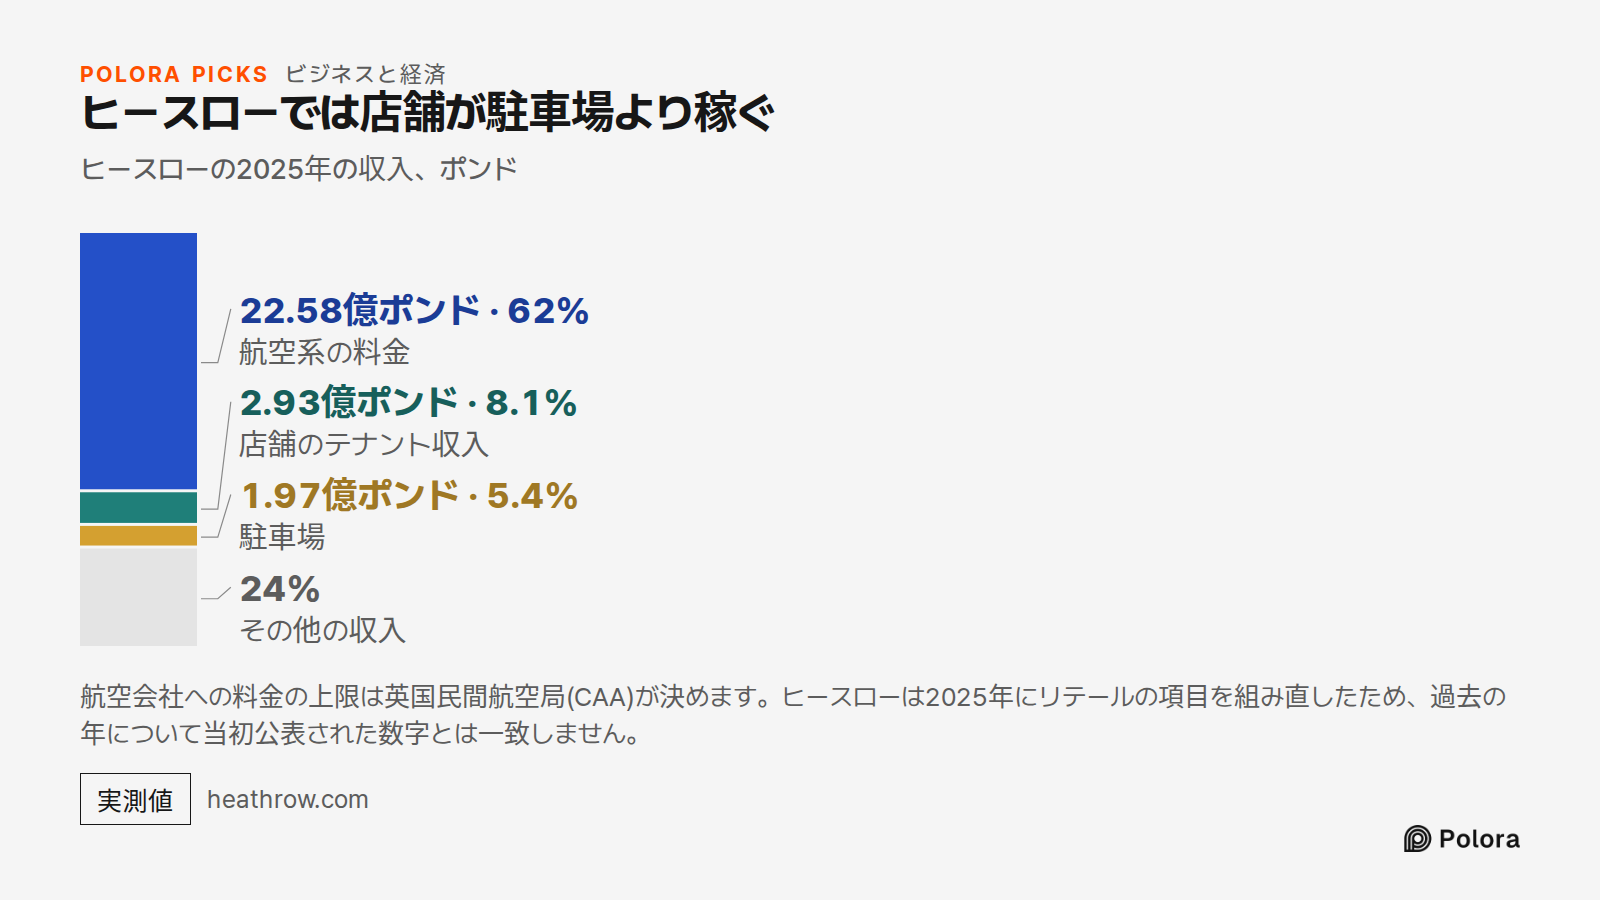
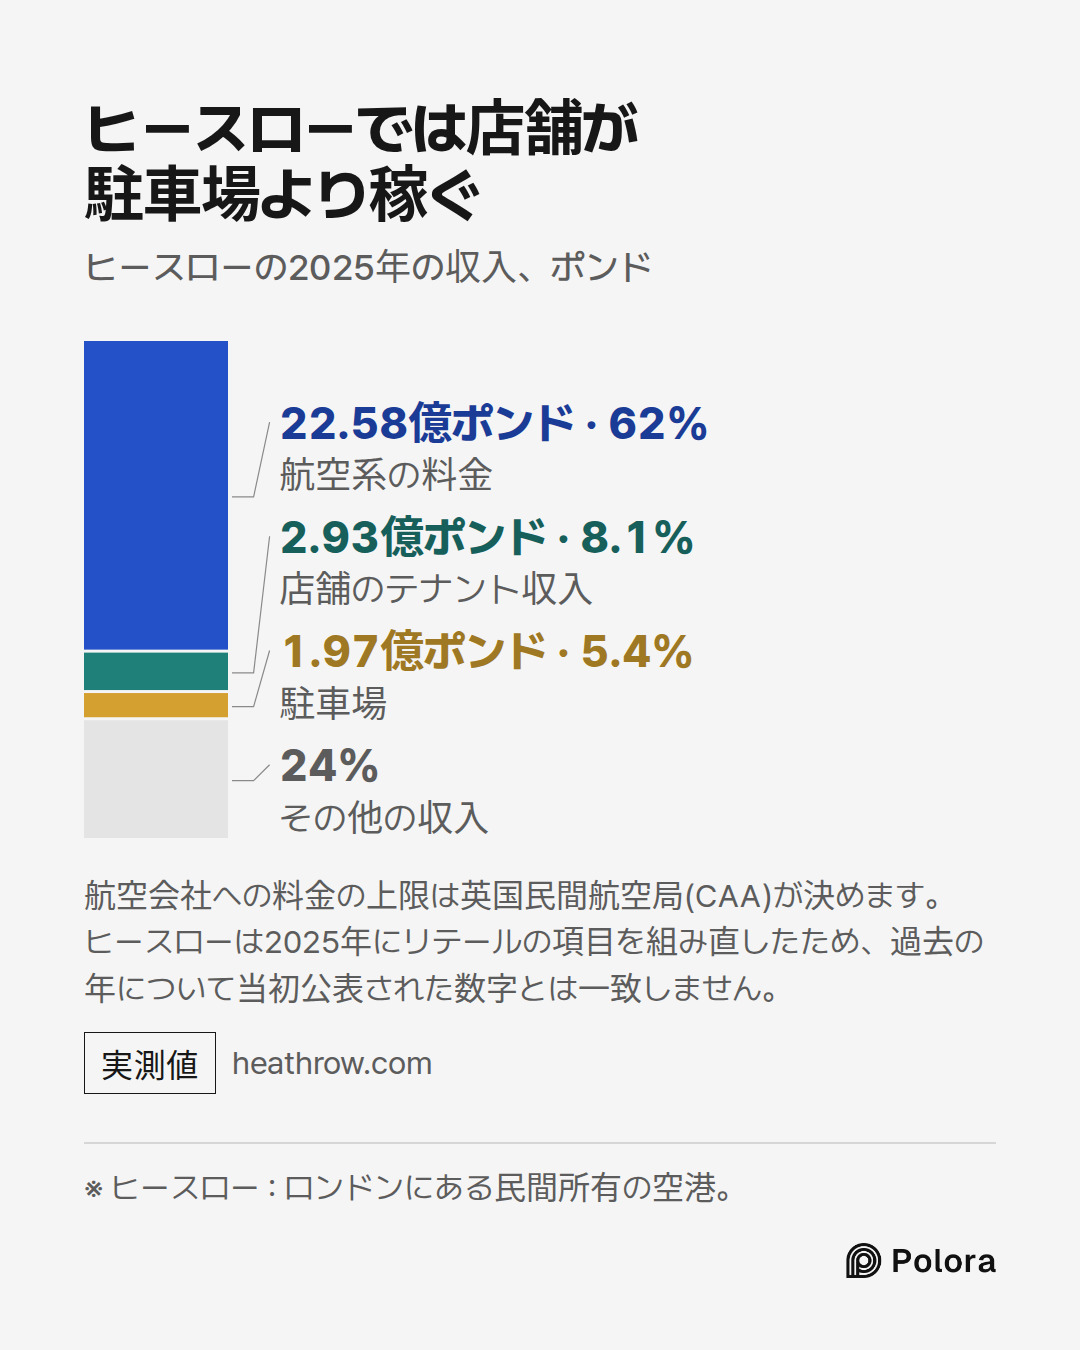
I checked Heathrow's 2025 Annual Report. I can confirm the top-line numbers stated in the manuscript: Heathrow reported £3,623 million in total revenue, with £2,258 million coming from aeronautical charges (roughly 62%) and £791 million from retail. The manuscript's claim that retail out-earns parking at Heathrow holds up at the macro level, as retail forms the largest non-aeronautical block there. (heathrow.com)
2. Residual vs. Compensatory Agreements:
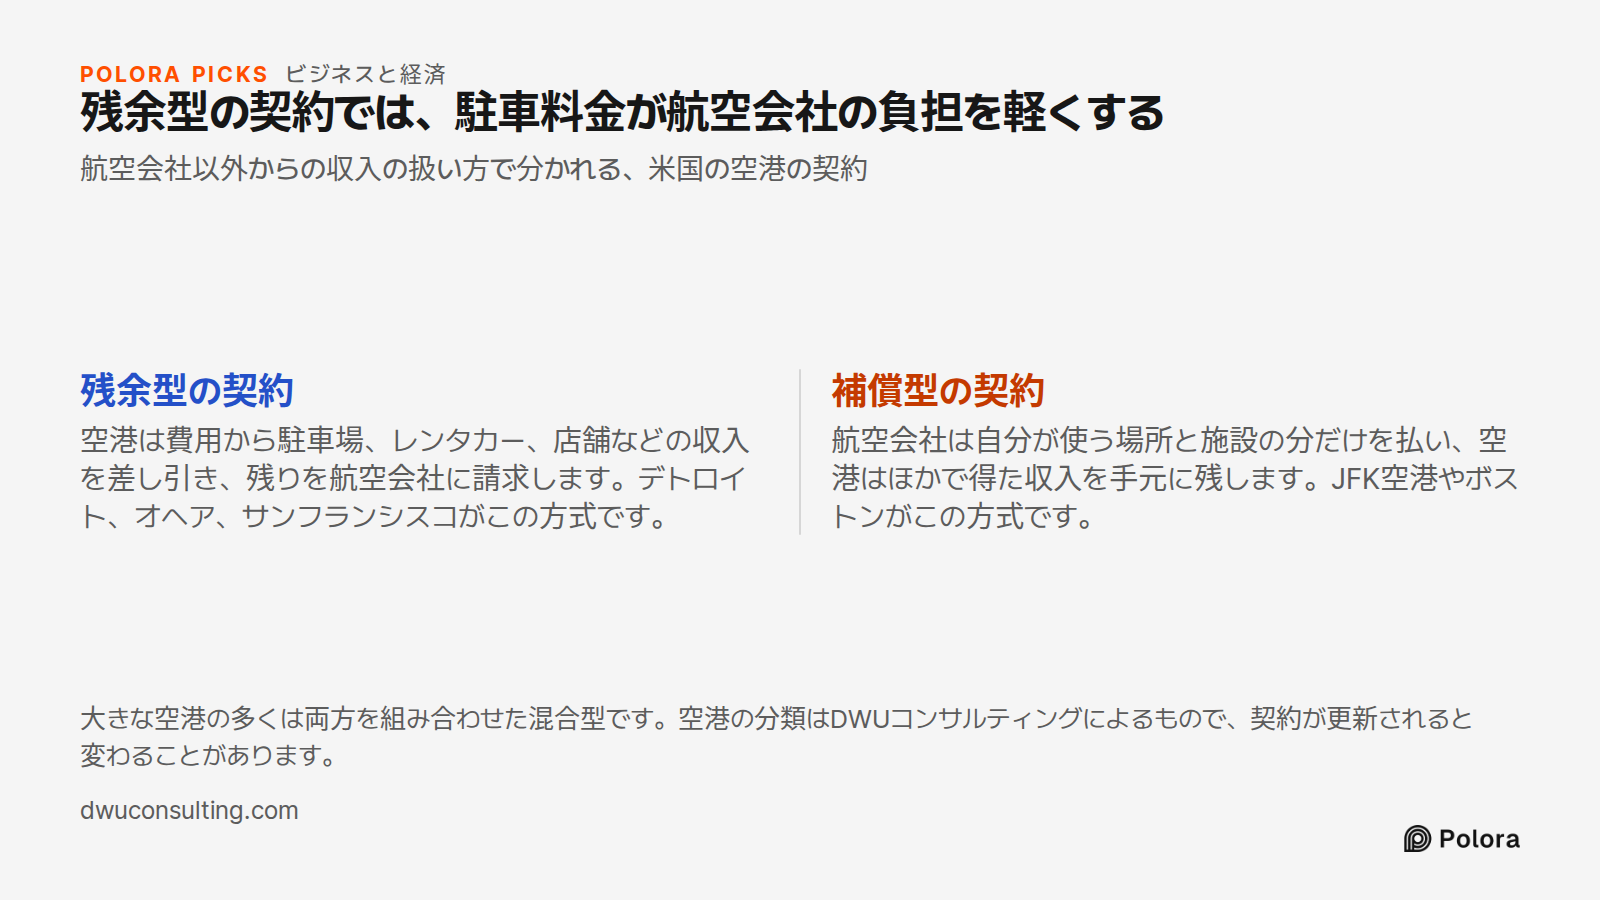
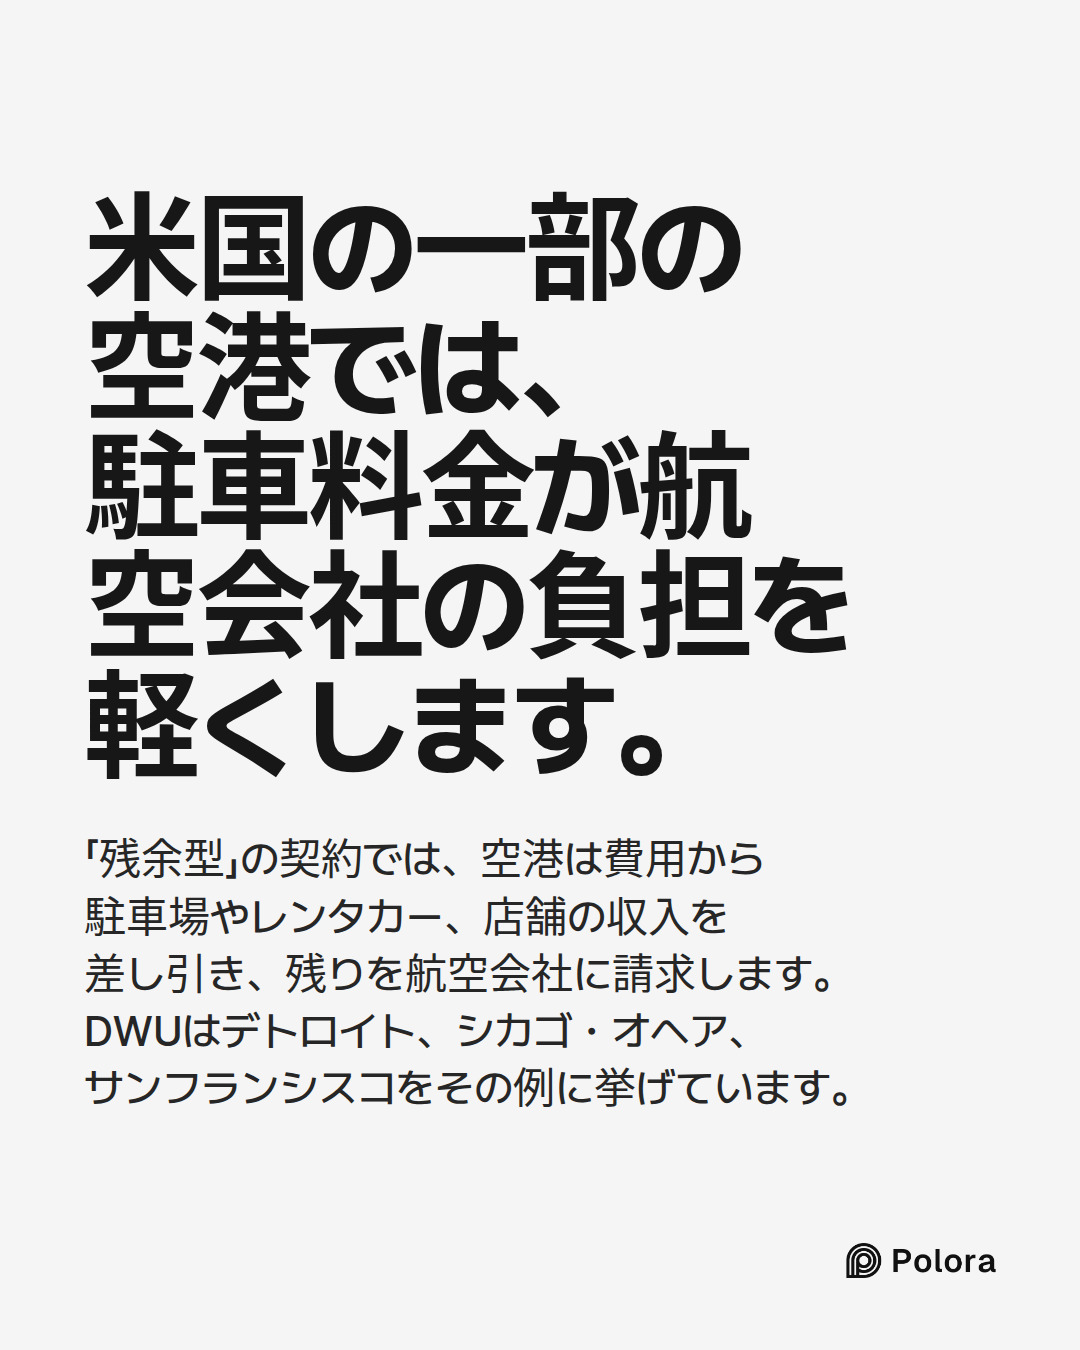
The manuscript correctly describes how residual agreements work. I verified this against the Transportation Research Board's (TRB) ACRP Report 36, *Airport/Airline Agreements—Practices and Characteristics*. The report confirms that under a residual structure, airlines guarantee that the airport's costs are covered, and non-aeronautical revenues (like parking and concessions)…
Researcher · gpt-6-luna
Verification update: several claims are supported, but the turns above overstate what the data establish and contain an important Detroit correction.
- Global figures: ACI World’s March 17, 2026 release says that in 2024 aeronautical revenue was 54% of total airport revenue and non-aeronautical revenue 37%. It does not establish that airlines bring in more than parking and shops at most individual airports. Nor does that release confirm the manuscript’s finer breakdown of parking, retail and food-and-beverage shares.
Source: https://aci.aero/2026/03/17/policymakers-must-support-airport-investment-as-global-air-travel-demand-rises/ (aci.aero)
- US FY2025 figures: DWU’s overview supports its July 21, 2026 snapshot of 417 airports: $34.5 billion in operating revenue, including $19.3 billion aeronautical and $15.2 billion non-aeronautical. It also reports that large hubs were 59% aeronautical, medium hubs 50/50, and small hubs 58% non-aeronautical. These are a dated DWU aggregation of FAA filings, not a final, fixed FAA national total. DWU’s c…
The Arbiter · gpt-6-sol
The voices agree on the key distinction: parking and shops are only part of non-aeronautical revenue. The global and US figures discussed compare *all* non-aeronautical revenue with aeronautical revenue, so they cannot be presented as a direct parking-and-shops total. DWU’s US figures also combine parking with ground transportation in one reporting line; they do not isolate parking receipts. (dwuconsulting.com)
The strongest challenge to the manuscript’s wording is “at most airports.” The cited global and US totals add up dollars across airports. They show an aggregate split, not how many individual airports have airline revenue above parking and shops. DWU’s hub-size breakdown makes that distinction consequential: large hubs lean toward aeronautical revenue, medium hubs are near even, and small hubs lean toward non-aeronautical revenue. (dwuconsulting.com)
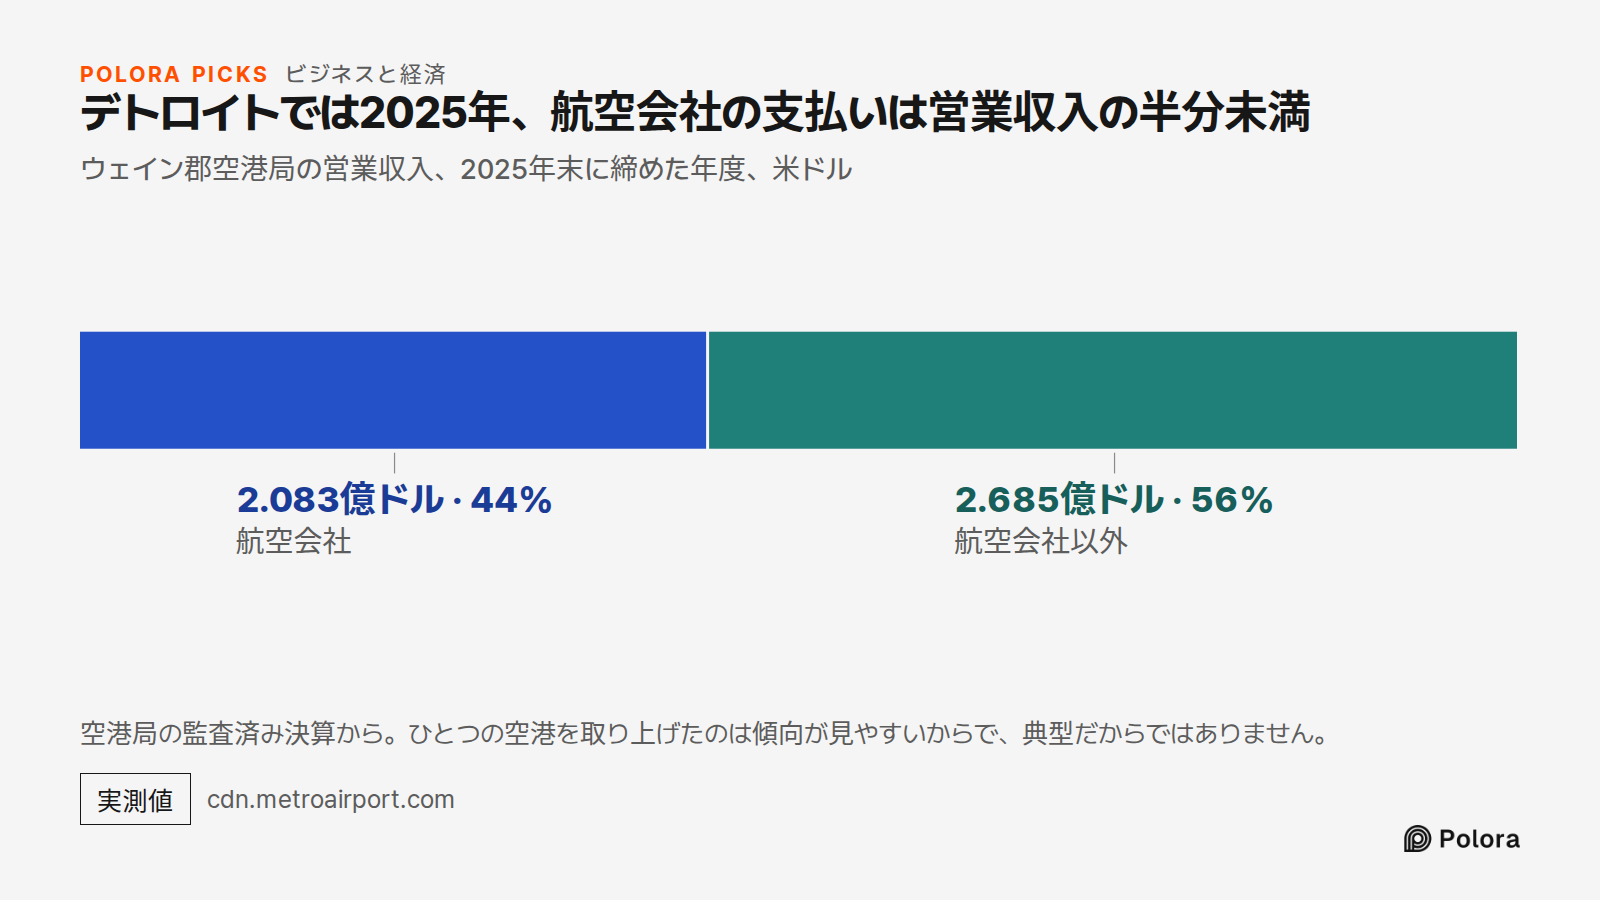
For the manuscript’s fact-check, the Researcher found that Detroit’s audited 2025 report conflicts with its date and figures. Beta and the Researc…
The Arbiter's Final Verdict · gpt-6-sol
Generally, no in the aggregate figures checked—but it depends on the airport. ACI World reports that aeronautical revenue made up 54% of global airport revenue in 2024, while *all* non-aeronautical revenue—not just parking and shops—made up about 37%. A dated aggregation of US airport filings likewise puts aeronautical operating revenue ahead, $19.3 billion to $15.2 billion for all other operating revenue. (ACI World; DWU Consulting)
That does not prove airlines bring in more at *most individual airports*: totals across airports cannot tell us how many airports fall on either side. Detroit’s airport authority, for example, reported more non-airline than airline operating revenue in 2025. Nor should “parking and shops” be treated as the whole non-airline side—it also includes such sources as rental cars and property. ([Wayne County Airport Authority audited report](https://cdn.metroairport.com/uploads/business_documents/PDFs/Finance/CAFR/55154%20-%20Wayne%20County%20Airport%20Authority%20A…