Alpha: what I checked, and what the manuscript needs to change
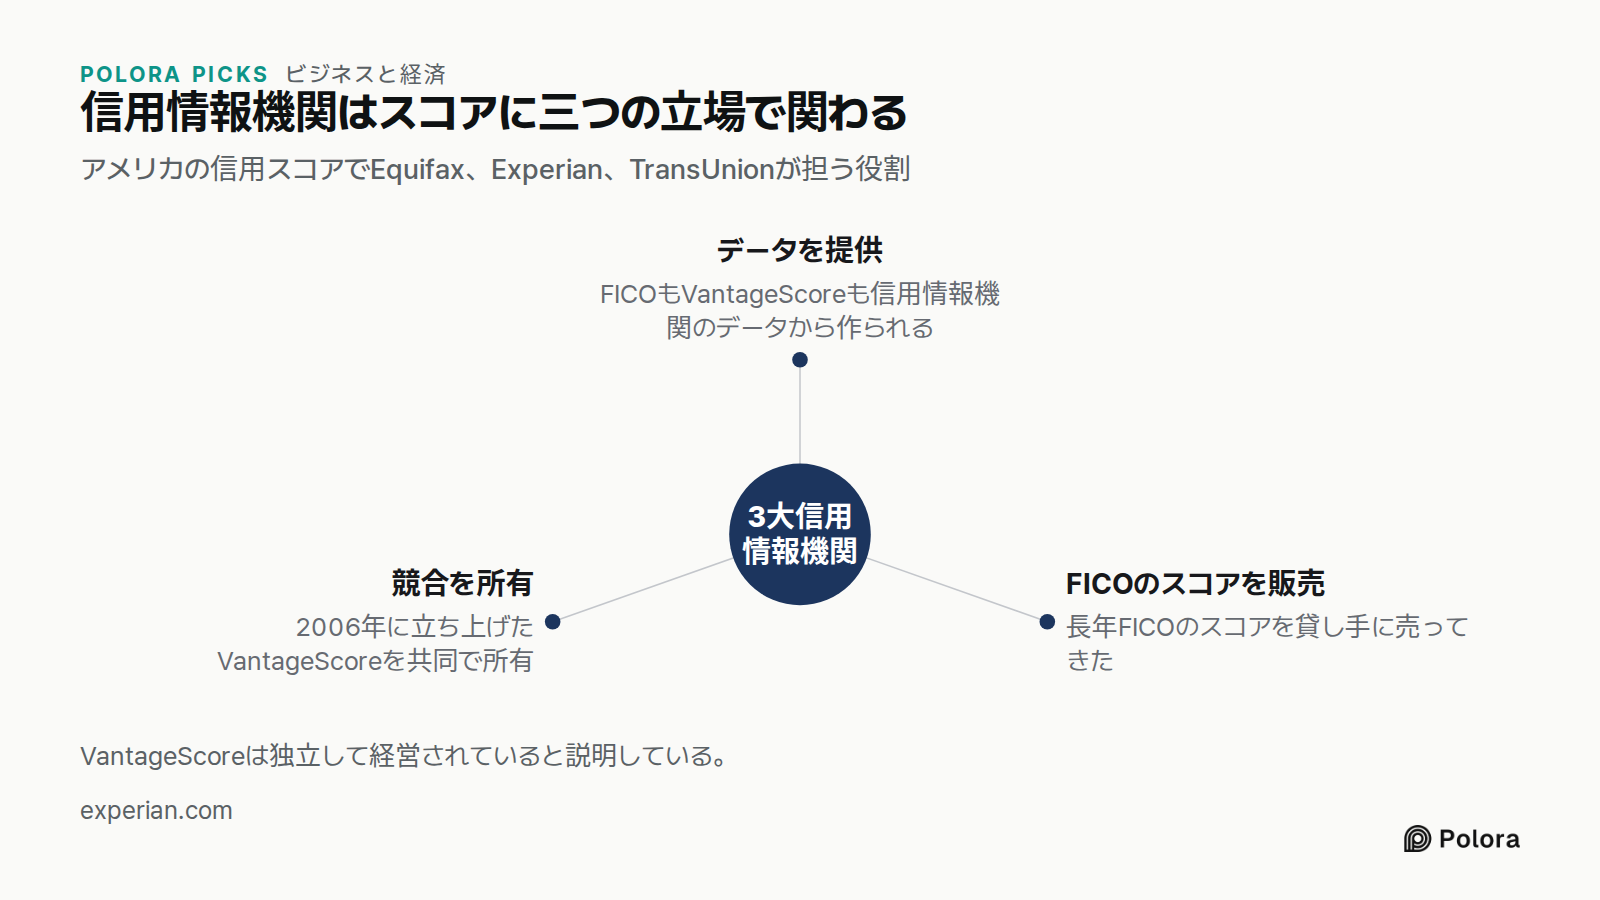
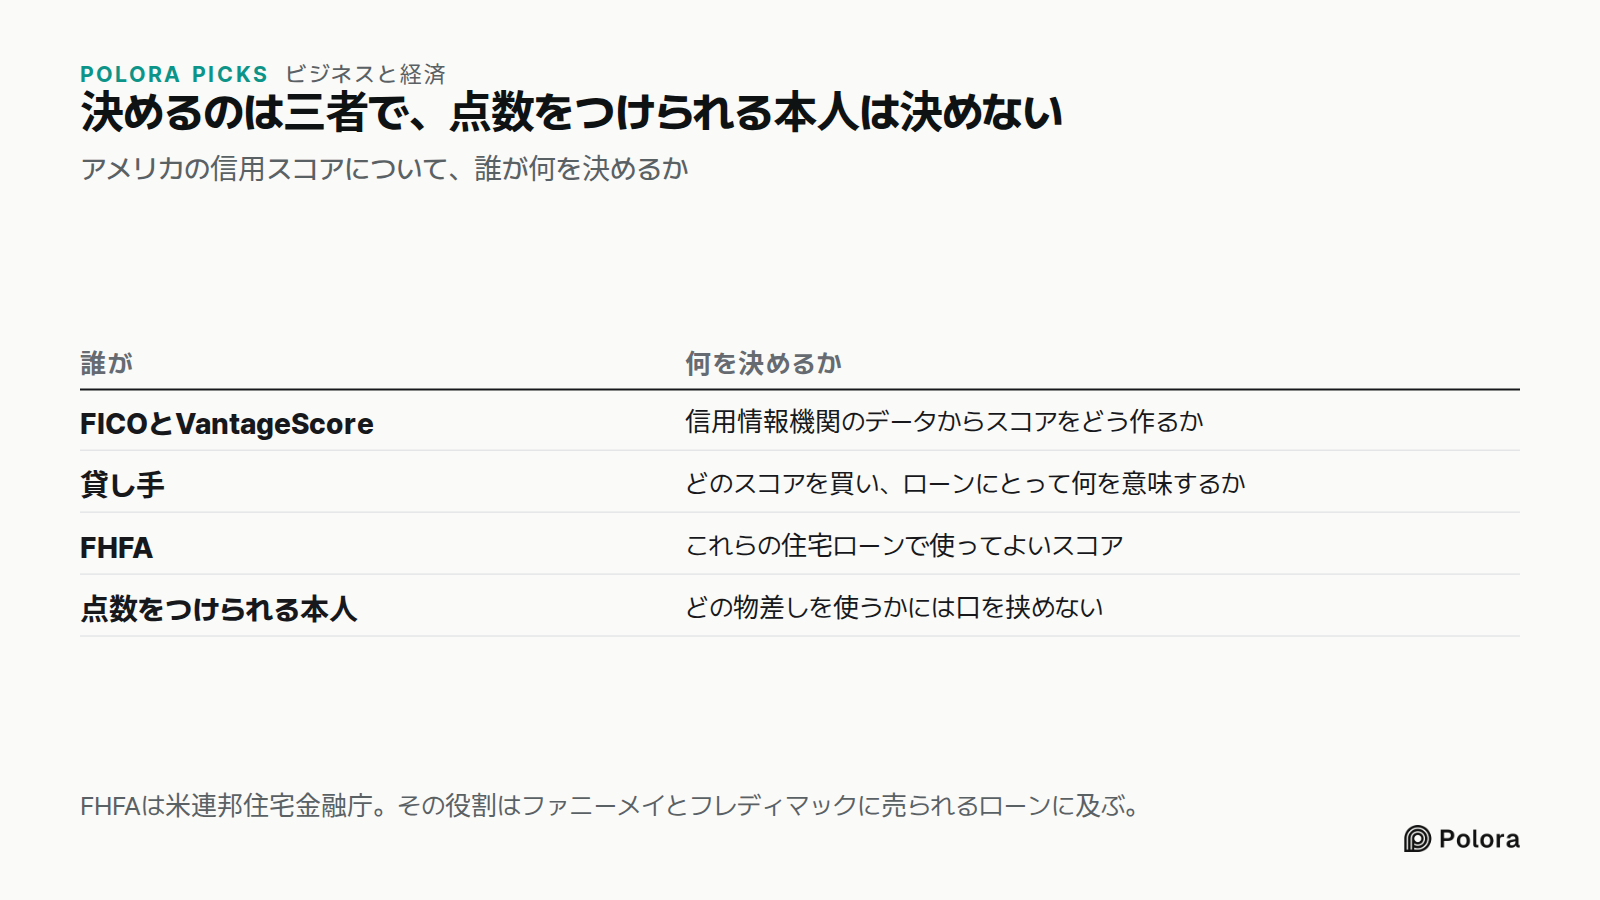
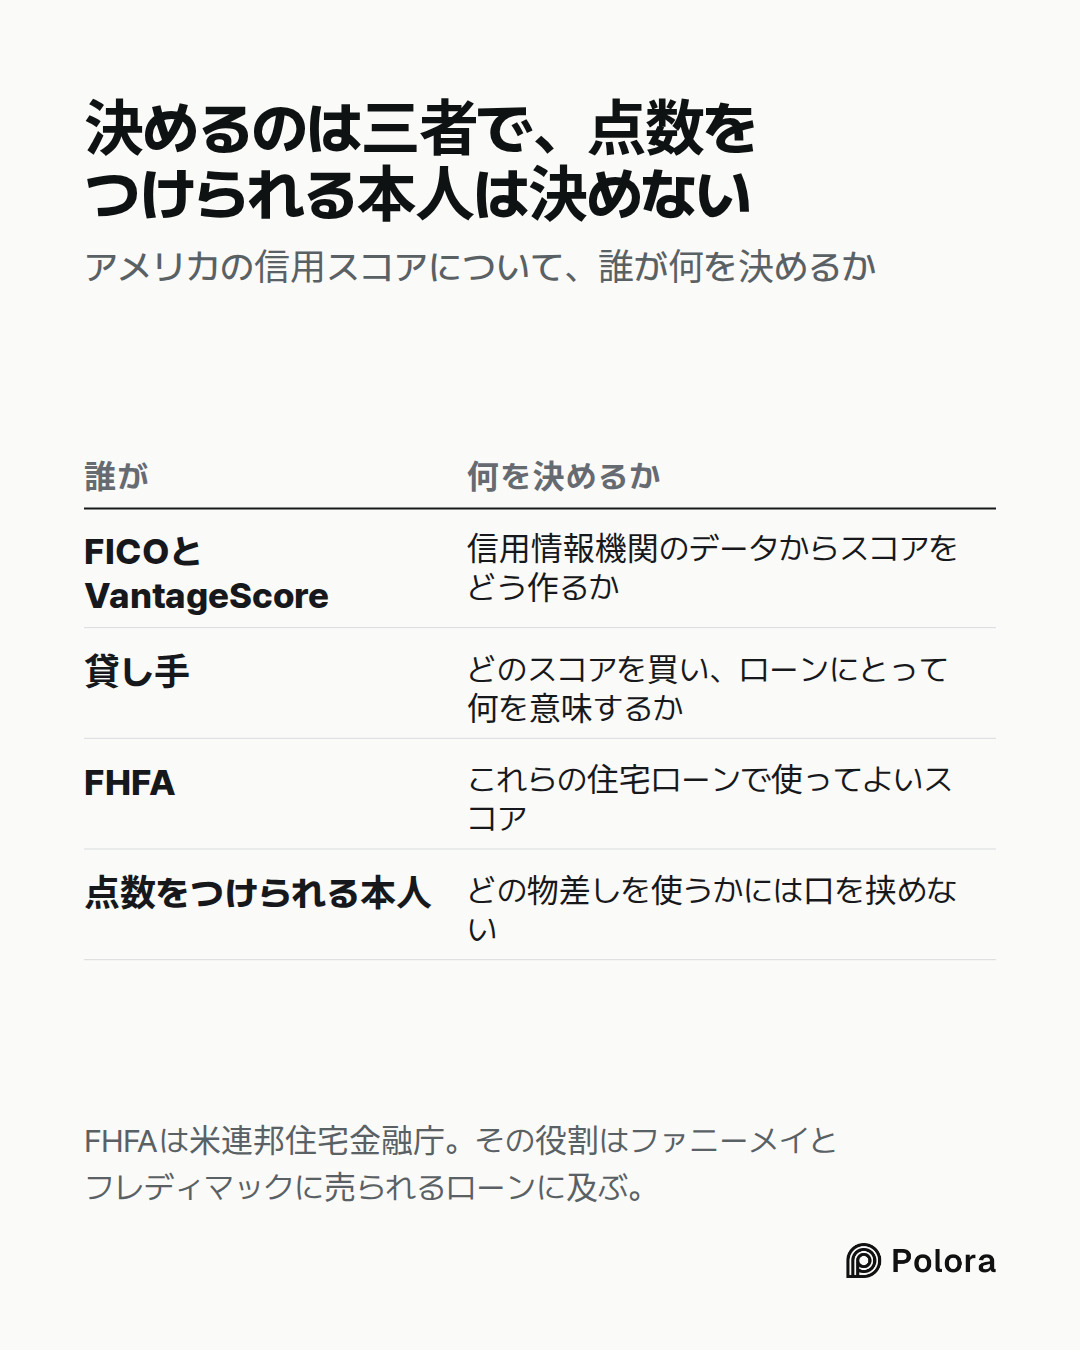
The premise stands. No government agency writes the scores lenders use. Private firms build them. A federal agency, the FHFA, only decides which scores Fannie Mae and Freddie Mac will accept.
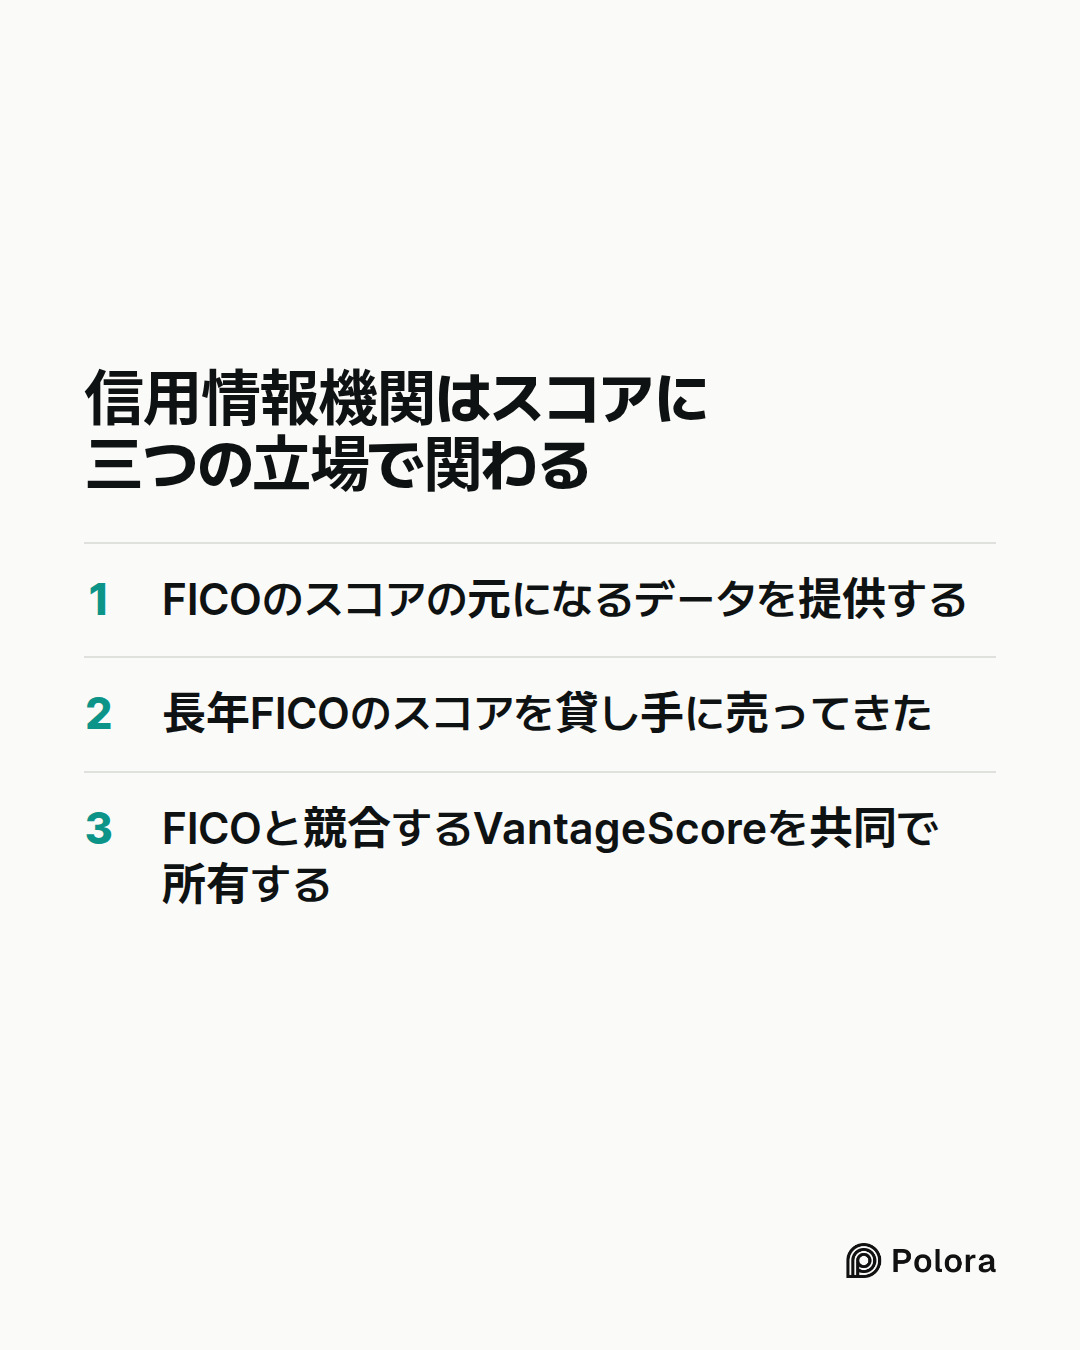
1. VantageScore is still jointly owned by the three bureaus. Confirmed.
- VantageScore's own lender FAQ calls it an independent joint venture of Equifax, Experian and TransUnion. It says VantageScore Solutions, LLC holds the intellectual property.
- A VantageScore press release dated within the last 36 days says the same: "VantageScore is an independent joint venture company owned by Equifax, Experian and TransUnion."
- A HousingWire article on Equifax's earnings call says VantageScore is jointly owned by Equifax, Experian and TransUnion.
- Caveat: VantageScore calls the venture "independently managed". The manuscript's phrase "a joint venture that they run together" slightly overstates how much control the bureaus have day to day. Ownership is shared, but VantageScore describes its management as independent.
2. Pricing and dates. Partly confirmed, with one correction.
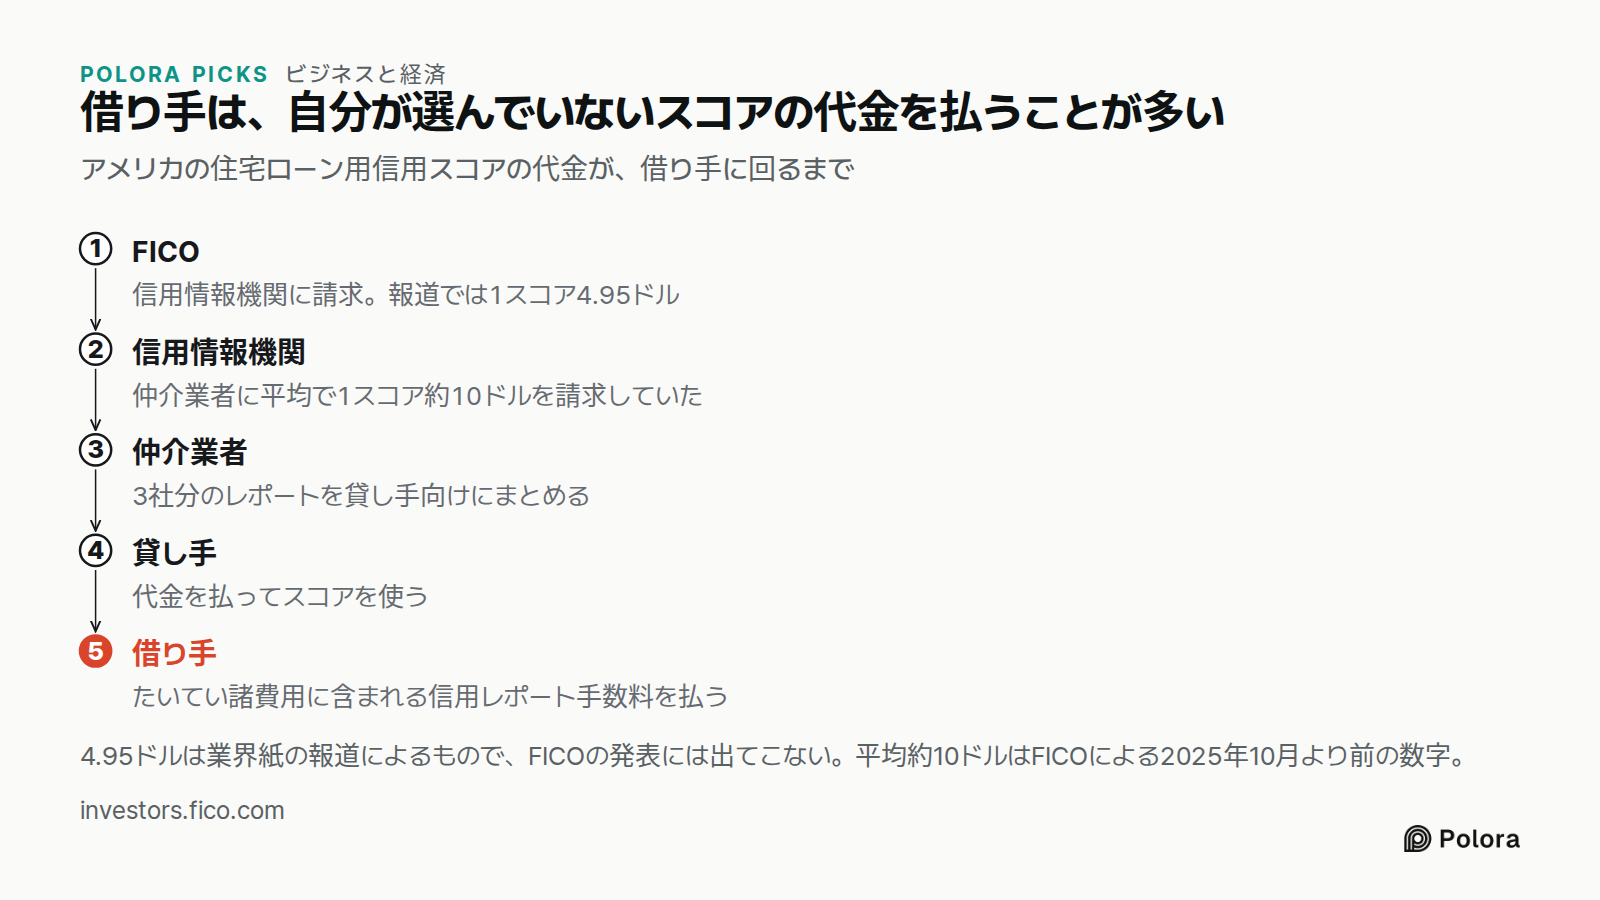
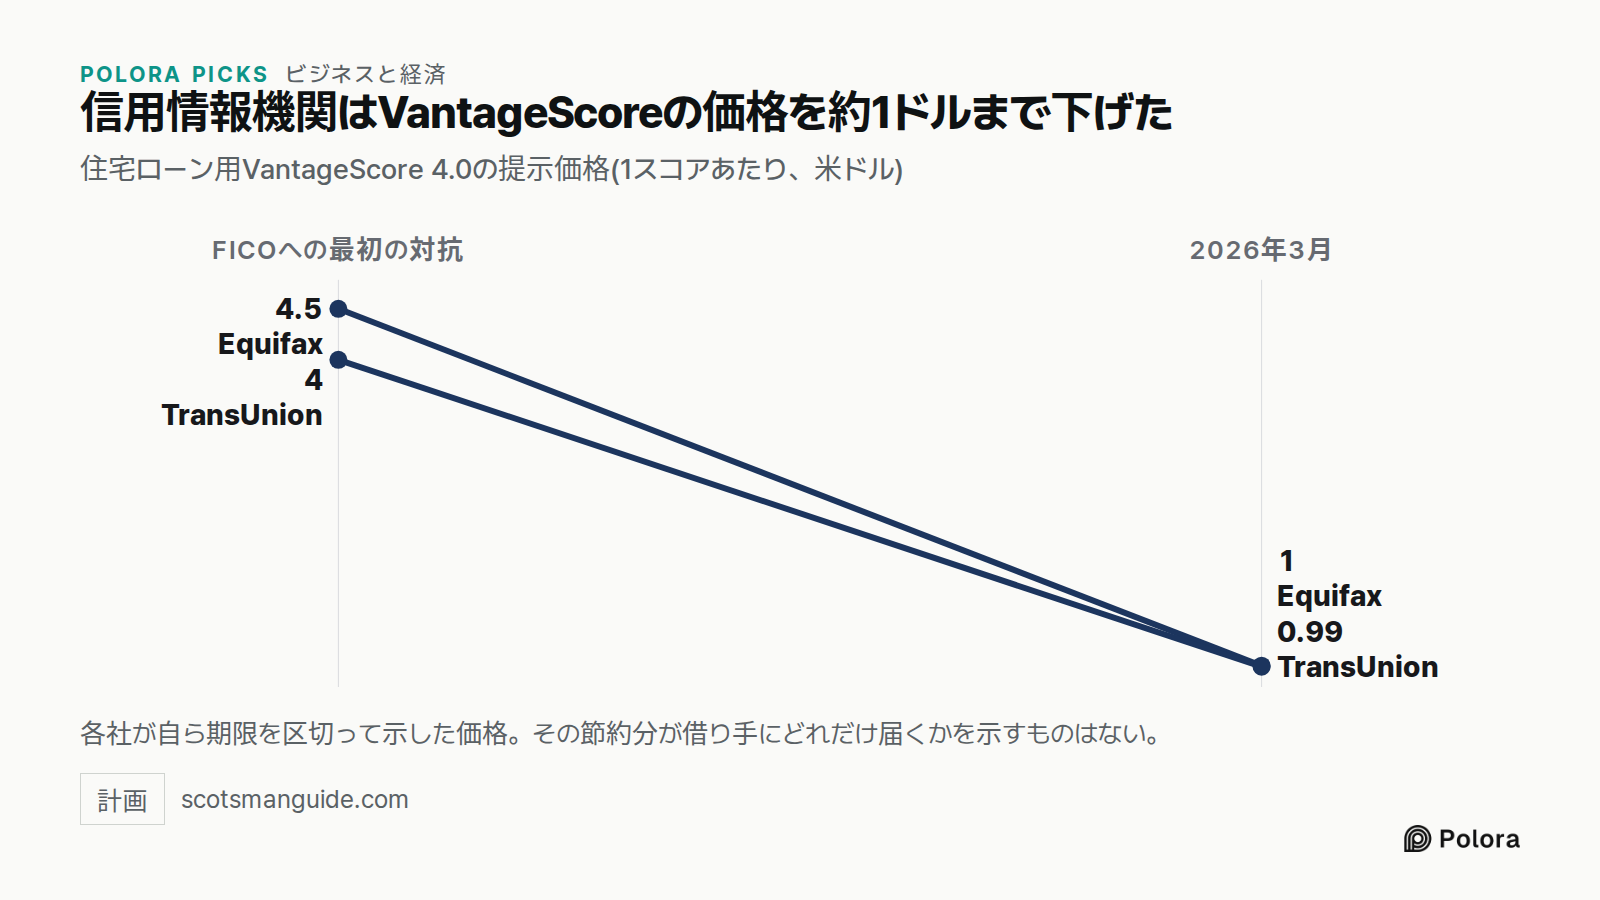
- Equifax's $1 price through 2027 is support…
Beta · gpt-6-sol
Beta: the manuscript’s premise stands, but “who decides” has several answers. In the US, creditors supply account information; credit bureaus hold reports; scoring companies design formulas; and a lender chooses which score to use and how to use it. There is no single official score. The CFPB confirms that scores differ by reporting company, formula, loan type and calculation date—and that a score shown to a consumer may not be the one a lender uses. (consumerfinance.gov)
Here is what I could check directly:
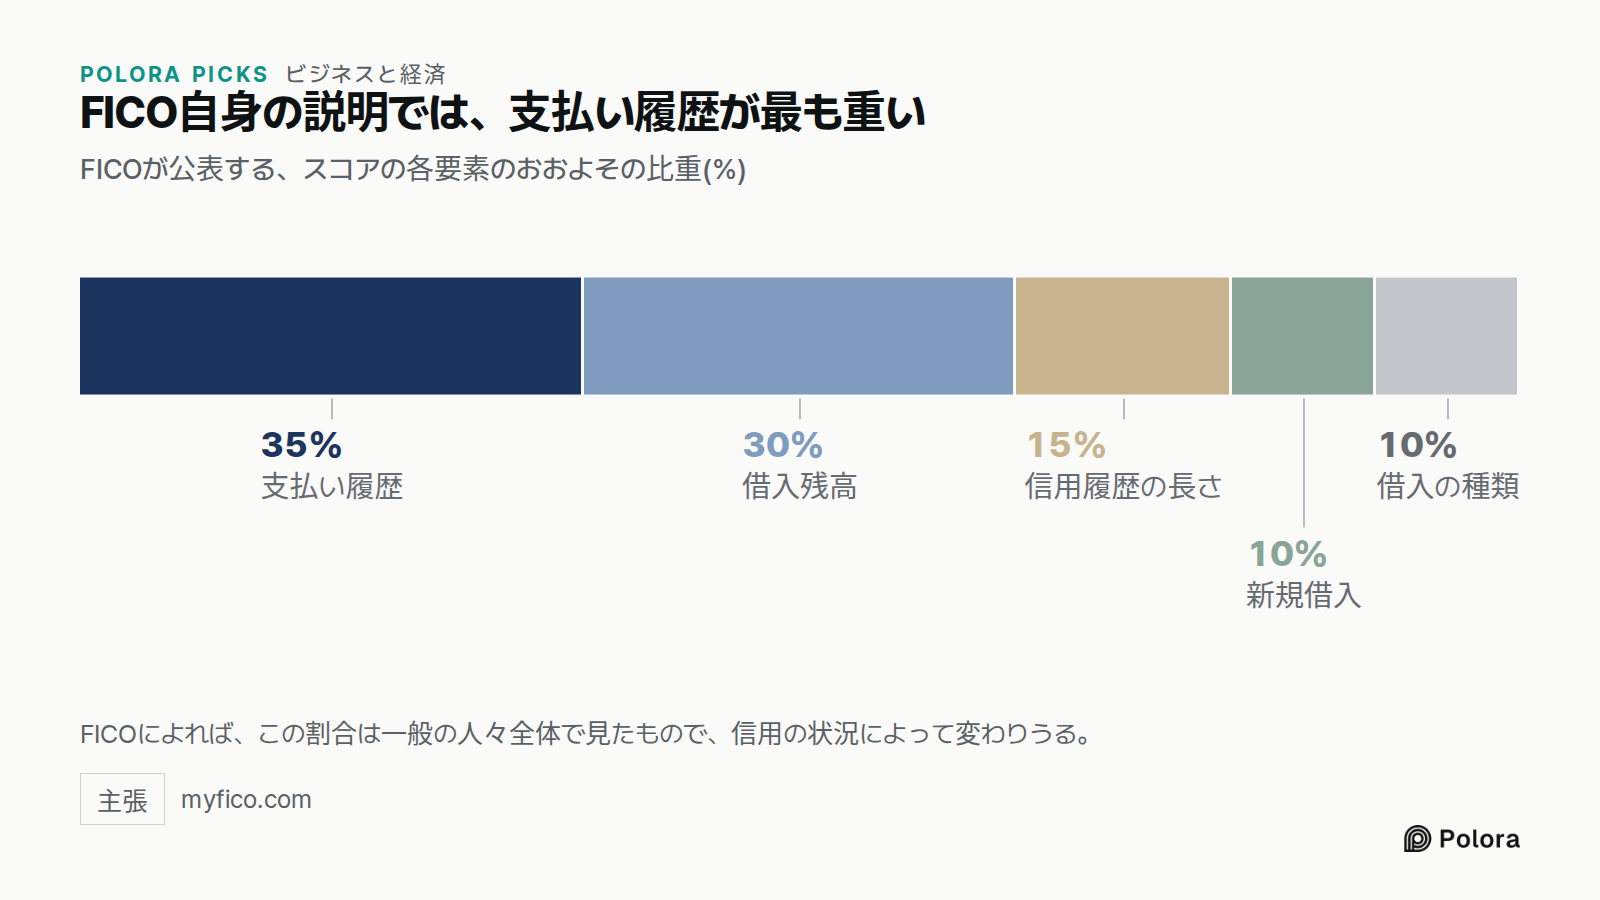
- FICO’s published factors are correctly stated: payment history 35%, amounts owed 30%, length of history 15%, new credit 10%, and credit mix 10%. FICO explicitly says these are *general-population* proportions, not a way to calculate the effect of a change on an individual’s score. Income and job title are not inputs to a standard FICO score, though lenders may consider them separately. Addresses: https://www.myfico.com/credit-education/whats-in-your-credit-score and https://www.myfico.com/credit-education/credit-scores/whats-not-in-your-credit-score/ ([myfico.com](…
Gamma · gemini-3.1-pro
Gamma: checking the remaining claims and the overall premise
The premise stands. Private companies build the credit scores, while federal guidelines and individual lenders ultimately decide which of those scores actually get used.
Here is what I verified regarding the manuscript's outstanding claims:
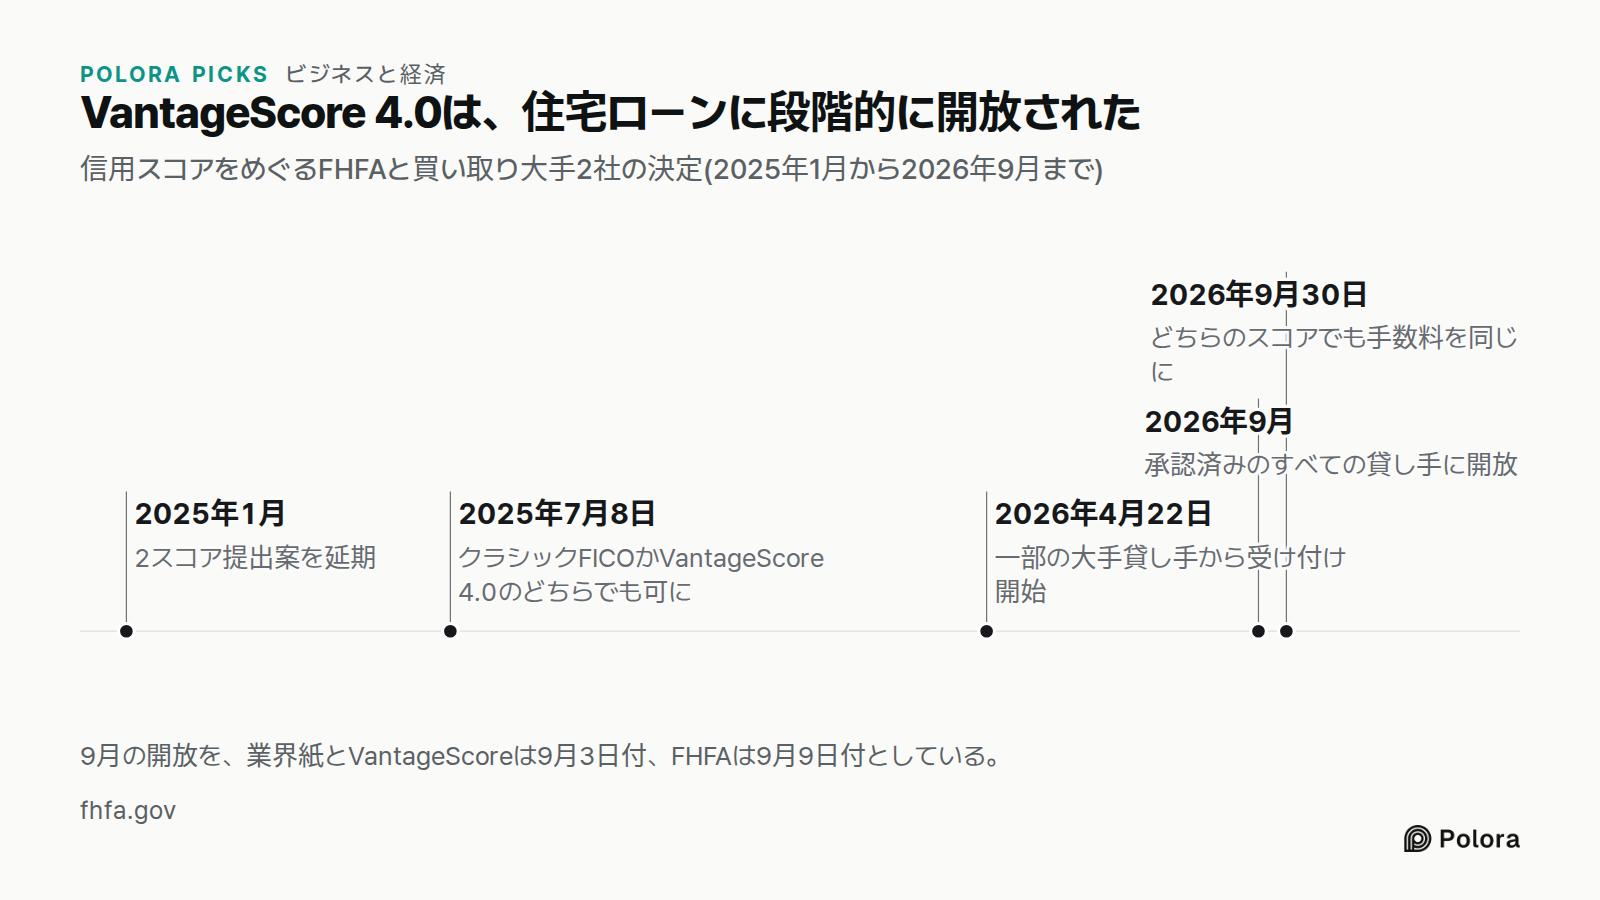
* The 21-lender rollout (April 2026): Confirmed. During an April 22, 2026 press conference, FHFA Director Bill Pulte announced that Fannie Mae and Freddie Mac were beginning to accept VantageScore 4.0 immediately through an initial rollout or "pilot" involving about 21 of the largest lenders. (Source: Inside Mortgage Finance, https://www.insidemortgagefinance.com)
* The September 3, 2026 two-bureau remark: Confirmed. Director Pulte stated that the agency was "seriously considering bi-merge" (allowing reports from two bureaus instead of three). This was stated in posts on X (formerly Twitter) in early September 2026, not in an official FHFA rule update. (Source: Mortgage Professional America, https://www.mpamag.com)
* The March 2026 bureau price cuts: Confirmed. On March 9, 2026, TransUnion announced it was dropping the standalone price of a VantageScore 4.0…
Researcher · claude-haiku-5-5
Researcher: checks against the live web, this round
I ran three searches this turn. A fourth was blocked by the search limit, so several items below remain unchecked. I have no view on the question itself.
1. Premise: private firms build the scores, and FHFA sets which ones Fannie Mae and Freddie Mac accept. The Fannie Mae page records that on July 8, 2025, lenders were allowed to use either VantageScore 4.0 or Classic FICO through the tri-merge requirement (https://singlefamily.fanniemae.com/originating-underwriting/credit-score-models). The Alston Consumer Finance summary describes the same choice (https://www.alstonconsumerfinance.com/fhfas-credit-score-models-and-reports-initiative/). The premise holds for the mortgage case. It does not hold as a general claim about all US lending, which this round did not test.
2. VantageScore ownership. A HousingWire article on TransUnion's pricing says VantageScore is jointly owned by TransUnion, Equifax and Experian (https://www.housingwire.com/articles/transunion-vantagescore-price-cut/). That is one secondary source. I did not confirm the VantageScore press release or 10-K wording that Alpha cites.
3. Pricing: the manusc…
The Arbiter · gpt-6-sol
The voices agree on a distinction worth keeping in view for the verdict: making a score, choosing which score counts, and deciding whether to lend are different jobs. Their principal challenge to the manuscript is its opening “No government agency does”: that describes who *makes* the scoring formulas, but risks obscuring FHFA’s power to limit the choices for loans sold to Fannie Mae and Freddie Mac. FHFA’s own policy page confirms that lenders can currently choose Classic FICO or VantageScore 4.0 under its rules, while FICO 10T is not yet eligible for delivery. (fhfa.gov)
I directly checked two points left open in the Researcher’s turn. FICO’s page gives the manuscript’s 35/30/15/10/10 breakdown and explicitly limits it to the general population; it says an individual factor’s effect cannot be measured without the full report. Equifax’s March 2026 filing states its VantageScore 4.0 mortgage price was $1 then. That is stronger evidence for the manuscript’s Equifax figure than the conflicting secondary report, though it does not establish every later price. Addresses read: https://www.myfico.com/credit-educa…
The Arbiter's Final Verdict · gpt-6-sol
Verdict
In the US, no single person or agency decides “your credit score.” Creditors supply information, private credit bureaus hold the reports, and scoring companies such as FICO and VantageScore design the models that turn report data into numbers. A lender chooses an available model and version, then decides how much weight to give the resulting score in a lending decision. That is why the score in an app may differ from the one a lender sees. The manuscript’s central premise stands, but its opening “No government agency does” needs a qualification: for loans sold to Fannie Mae and Freddie Mac, FHFA sets the menu of eligible scores. It does not write the formulas. CFPB · FHFA
The main claims tested land as follows:
- Who makes and owns the products: FICO is a publicly traded private company. VantageScore is jointly owned by Equifax, Experian and TransUnion, though calling it a venture the bureaus *“run together”* overstates the evidence about day-to-day management. The bureaus supply the report data; neither company’s formula is…