Alpha's assessment
The manuscript's central arithmetic holds up well under checking, with a few precision points worth flagging.
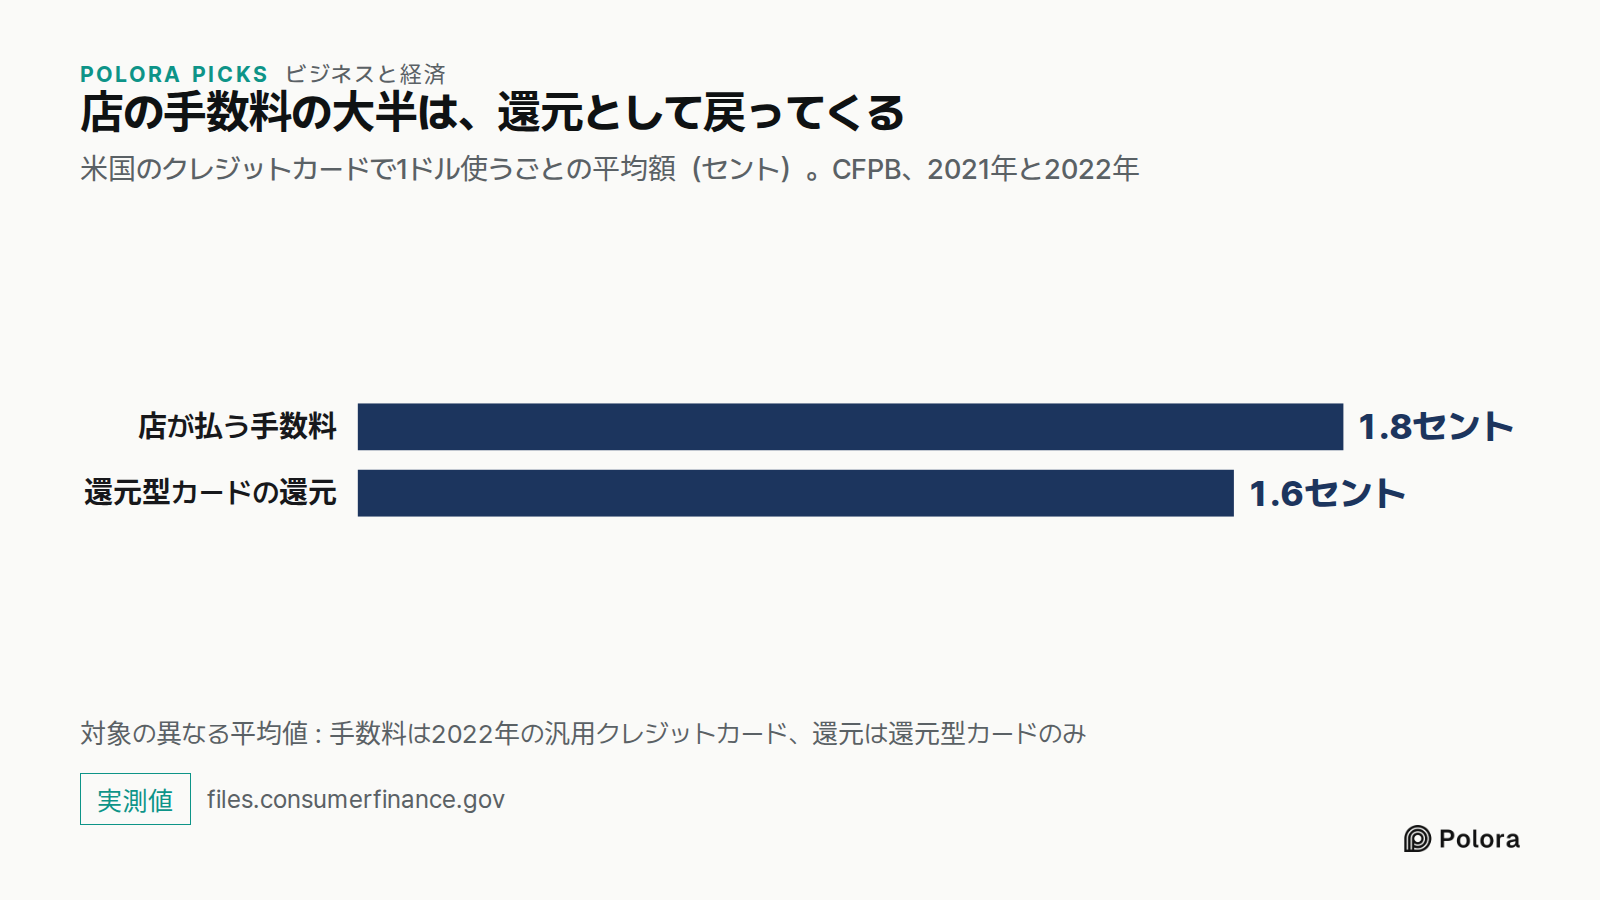
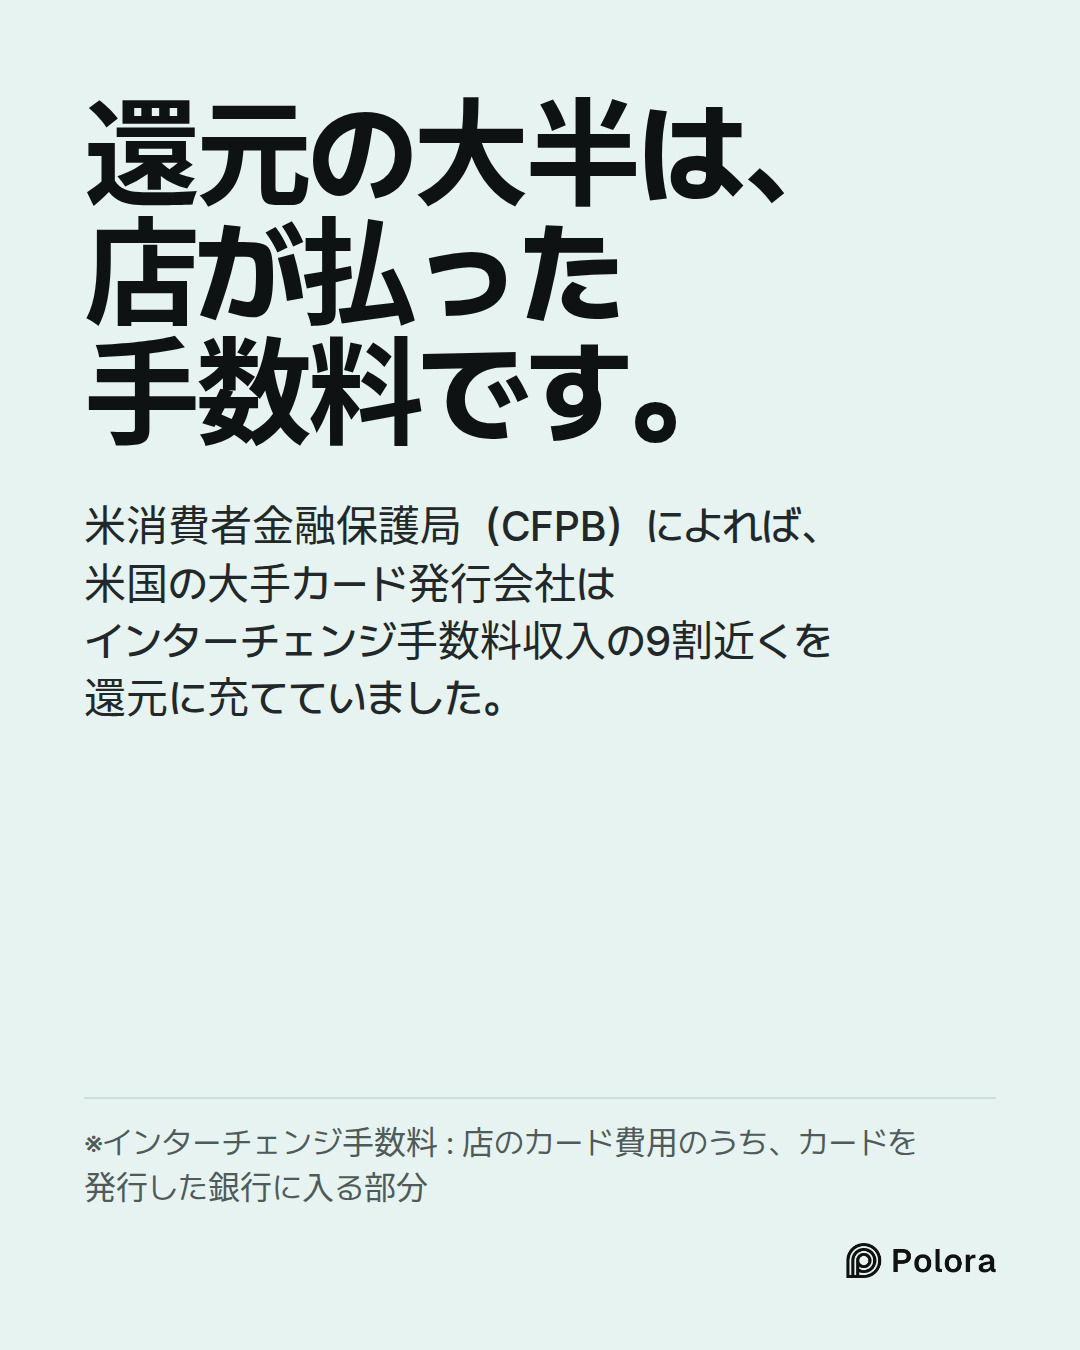
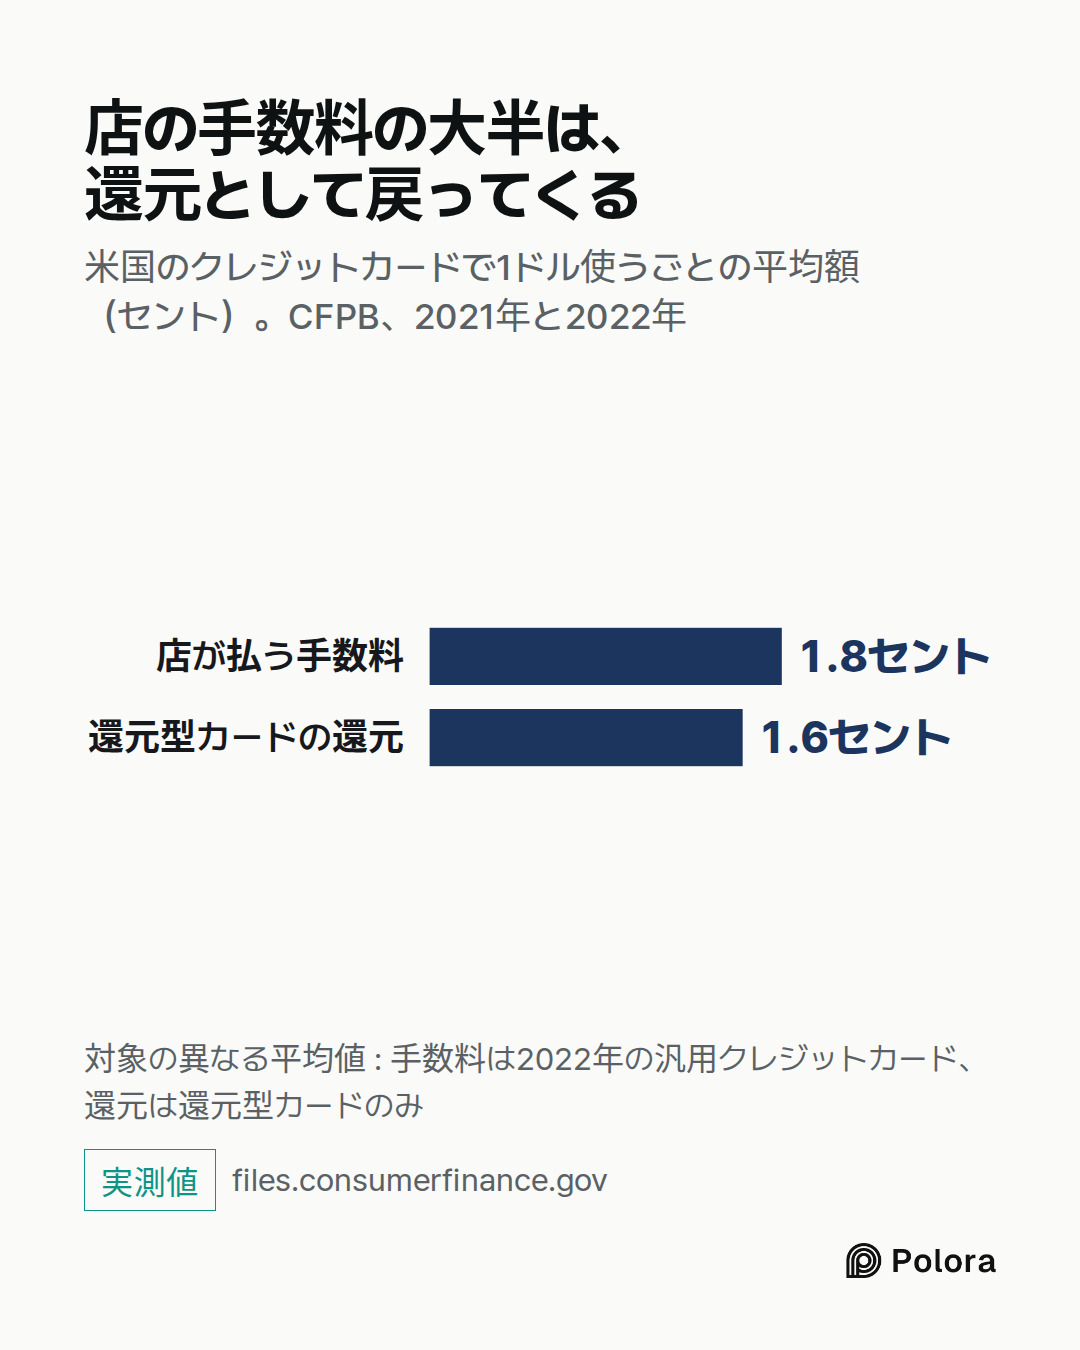
The CFPB numbers check out, with a nuance. The 2023 CFPB report does state what the manuscript claims. Searching corroborates this independently: a 2026 New York Fed staff paper on credit card banking found banks' interchange income is 1.82% of purchase volume on average, while rewards costs are 1.57% — essentially the same 1.8%/1.6% split the manuscript cites, from a different dataset covering 90% of the market. That's a genuine independent confirmation, not just an echo of the same CFPB report. The nuance: CFPB's own 2023 report frames net economics slightly differently than "issuers keep a slice" implies — it describes a net interchange rate of 1.1 percent of average receivables (or 0.3 percent of annual purchase volume), calculated after both interchange expense and rewards expense are netted out, which is a more conservative framing than simply subtracting 1.6 from 1.8. The directional claim — issuers earn more in interchange than they spend on rewards — is confirmed by the source itself.
New, stronger evidence has emerged since the manus…
Beta · gpt-6-sol
The premise stands, but the manuscript makes the funding chain sound more exact than the evidence permits. A merchant pays to accept a credit-card purchase; interchange is the portion received by the card issuer, not necessarily the merchant’s entire card-acceptance charge. Issuers commonly use that revenue to fund rewards. When a merchant charges customers the same price regardless of payment method, cash and debit customers can bear part of the cost without receiving the credit-card reward. Borrowers who carry balances supply another important stream of issuer revenue. None of this means the bank simply takes *the fee on your particular purchase* and returns most of it to you. (files.consumerfinance.gov)
Here is what I could check against sources, rather than against the manuscript’s assertions:
| Manuscript claim | Finding and condition |
|---|---|
| 1.8% interchange; rewards nearly nine-tenths of it; 1.6 cents per dollar | Supported for the CFPB’s reported populations and years. Its 2023 report gives 1.8% average interchange for general-purpose cards…
Gamma · gemini-3.1-pro
As Gamma, I have reviewed the manuscript, Alpha and Beta's evaluations, and run live searches to verify the outstanding claims—especially those concerning the 2026 legislative and legal events that Beta could not definitively clear.
Here is what I found regarding the open questions in the editor's brief, fully verifying the 2026 timeline:
The Visa/Mastercard Settlement Timeline and Objections
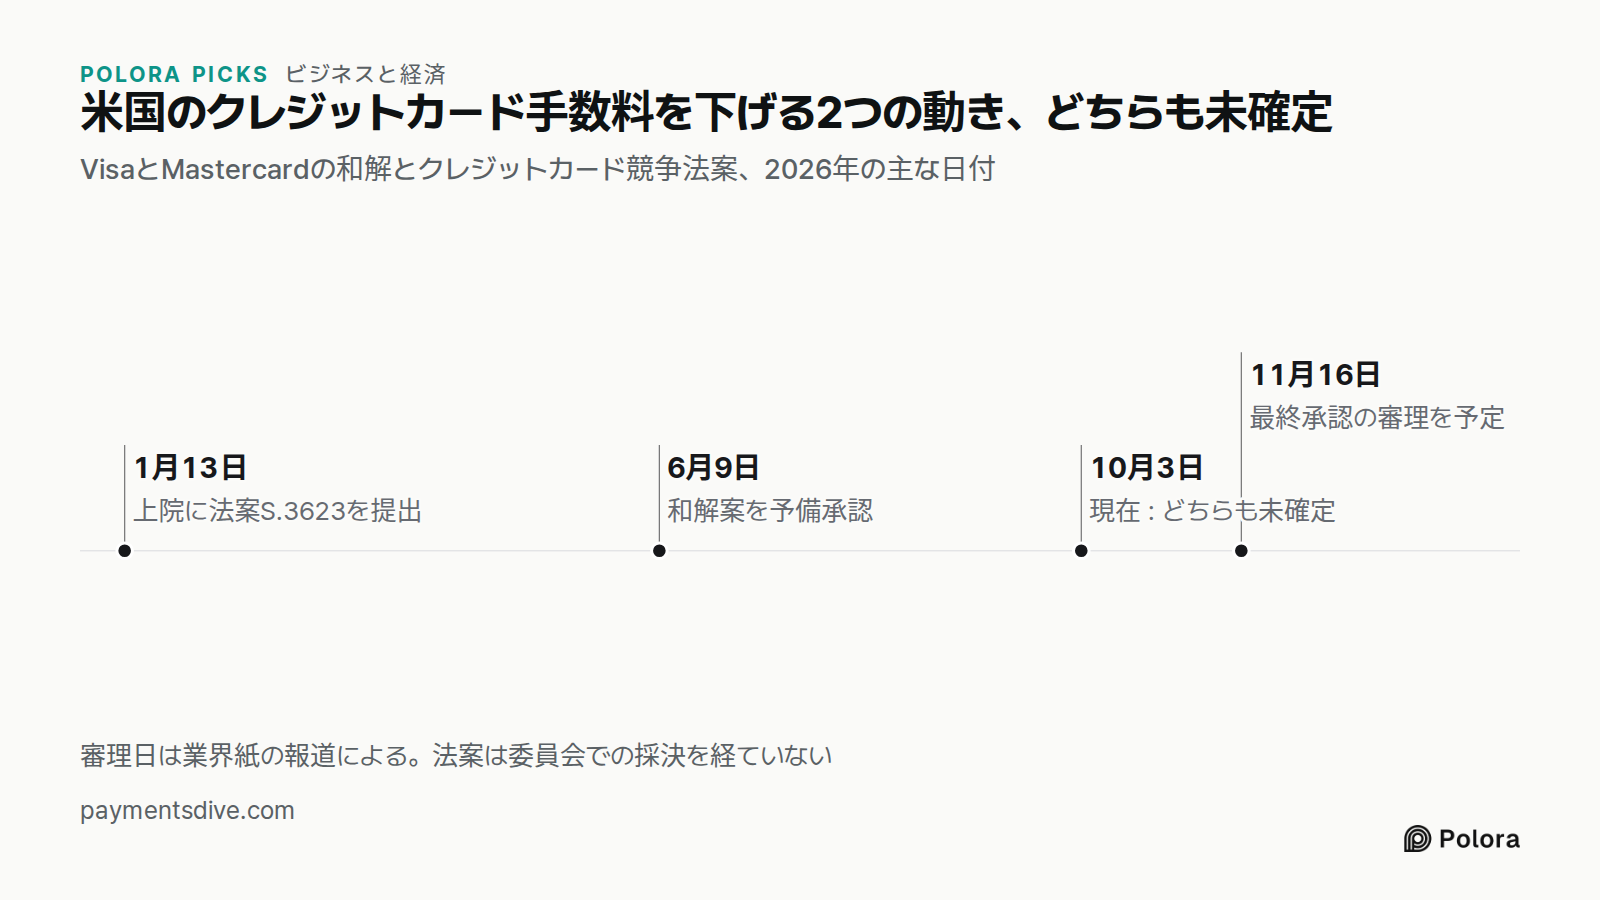
* Preliminary Approval Date: The manuscript's assertion of "June 2026" is correct but imprecise. I confirmed via contemporary trade press (Payments Dive, June 9, 2026) that U.S. District Judge Brian Cogan granted preliminary approval on June 9, 2026. The manuscript should be updated to this exact date.
* Final Approval Hearing and Objectors: The manuscript is completely accurate here. The final fairness hearing is indeed scheduled for November 16, 2026. Furthermore, on September 15, 2026, Walmart along with roughly 900 other merchants and trade groups (including the National Retail Federation and the National Restaurant Association) filed formal objections to the settlement, asking the court to reject it or allow them to opt out.
* NACS Appeal Pledge: The manus…
Researcher · gemini-3-7-flash
Research Verification & Fact-Check
Below is the verification of the specific claims made in the manuscript and debater briefs against live primary and secondary sources.
---
1. Verification of Manuscript Claims & Numbers
* CFPB Interchange and Rewards Numbers (1.8% interchange, 1.6% rewards earn rate, ~90% spent on rewards):
* Status: Supported as market/portfolio averages.
* Source: CFPB Consumer Credit Card Market Report (2023) & CFPB (2025/2024 update).
* Nuance: The CFPB reports that across general-purpose credit cards at major Y-14+ issuers, average interchange revenue was approximately 1.8% of purchase volume, and rewards expenses accounted for almost 90% of interchange revenue. The 1.6 cents per dollar ($0.016 / 1.6%) reflects the average earn rate specifically on *rewards cards*, not an entitlement on every individual general-purpose transaction.
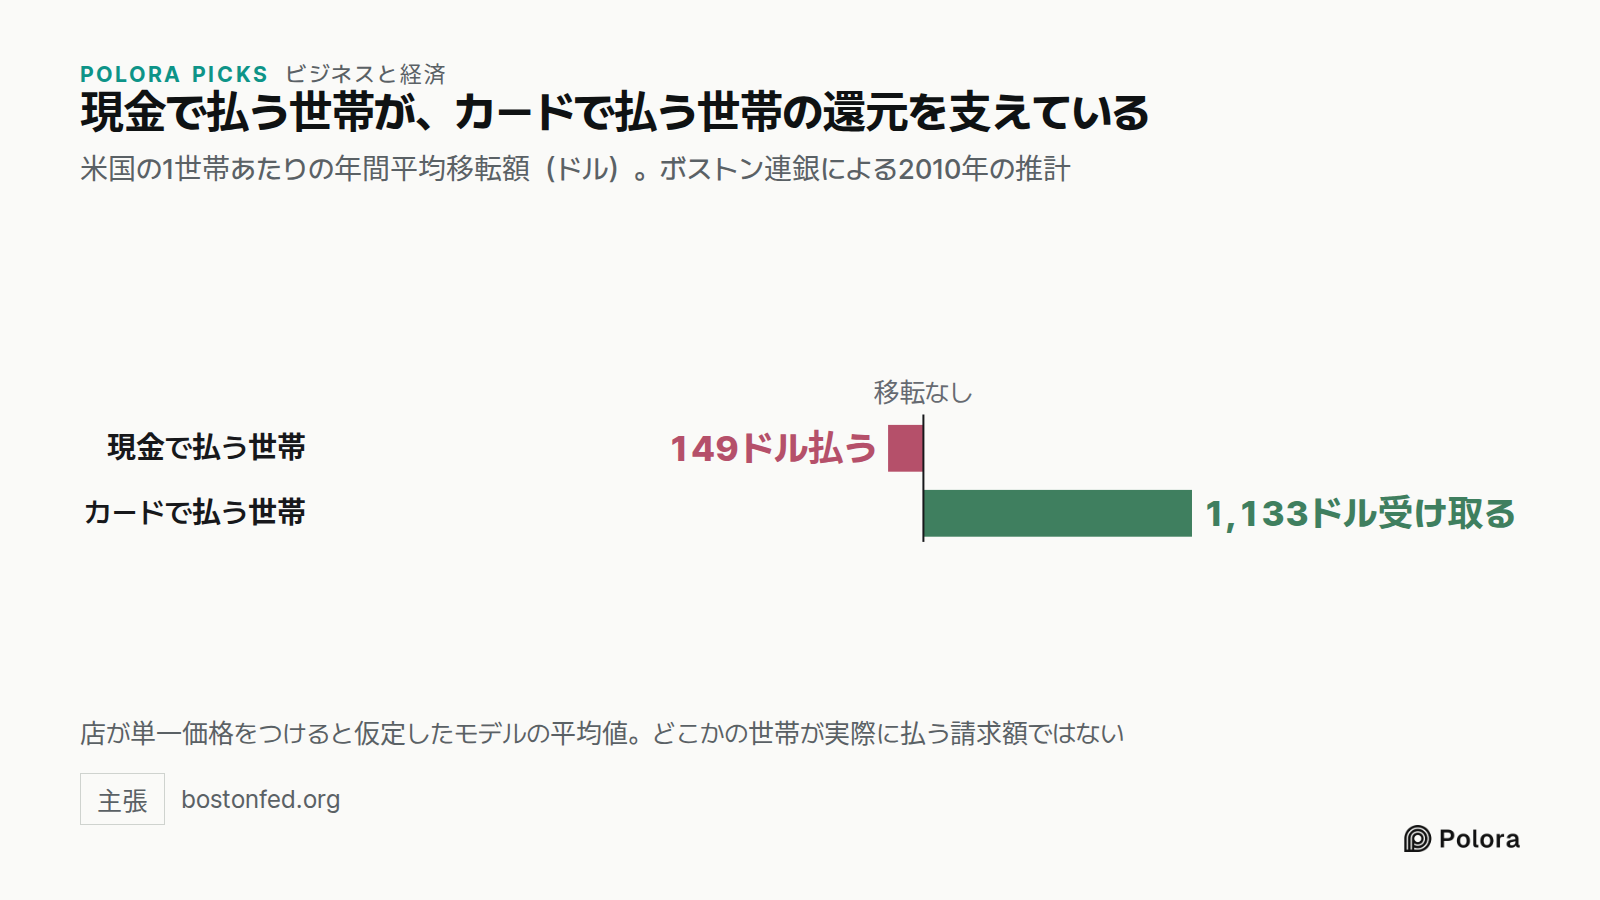
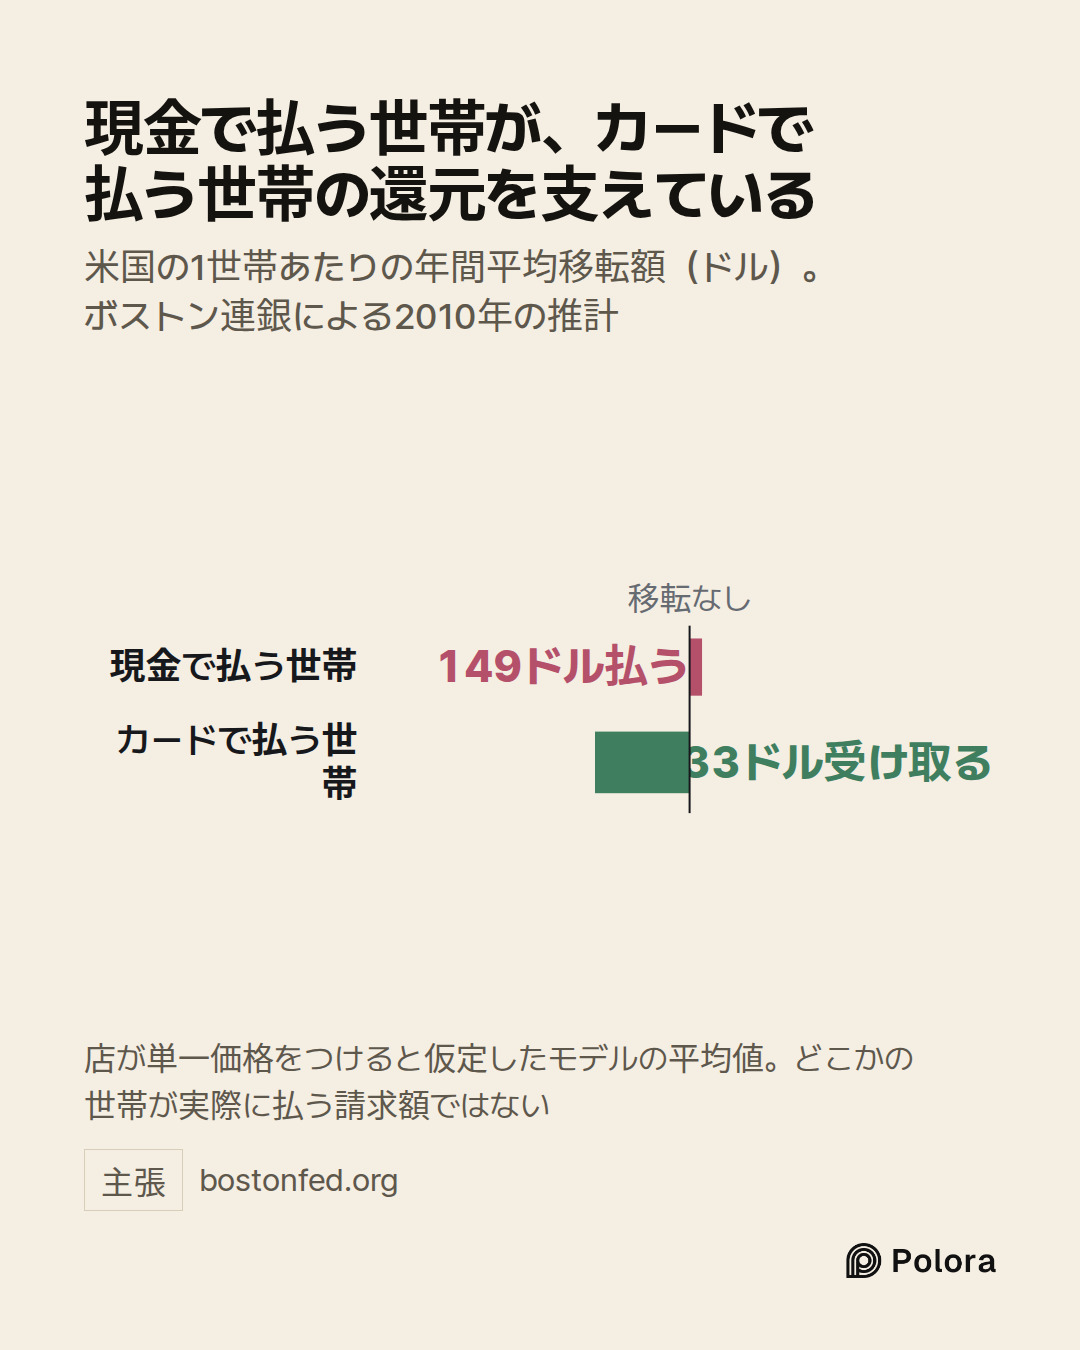
* Boston Fed Study on Cash-to-Card Cross-Subsidy ($149, $1,133, $21, $750):…
The Arbiter · gpt-6-sol
Round record
The central finding is shared, but the size and route of the subsidy need care. Alpha, Beta, Gamma, and the Researcher agree that interchange paid by merchants is a major source of credit-card rewards. They also agree that customers who do not receive rewards can bear some of that cost when merchants use a common price. Beta’s important distinction is that interchange is the issuer’s portion of card-acceptance costs, not necessarily the merchant’s entire fee, and that a reward is not a refund traceable to the fee on one particular purchase.
- CFPB arithmetic: Alpha and the Researcher confirm the manuscript’s roughly 1.8% interchange, nearly nine-tenths spent on rewards, and 1.6 cents earned per dollar figures in the CFPB’s 2023 report. Beta identifies a consequential mismatch in the manuscript’s illustrative dollar: 1.8% averages *general-purpose card purchases*, whereas 1.6 cents averages spending *on rewards cards*. Neither is a promise about the reader’s transaction. Beta also disputes that the difference can simply be called a slice the ba…
The Arbiter's Final Verdict · gpt-6-sol
Your cash back is mainly funded by merchants’ card fees—but who ultimately bears the cost depends on how stores set prices. When you buy something with a credit card, the merchant pays a card-acceptance fee; its interchange portion goes to your card issuer. Issuers use interchange revenue to help fund rewards. The bank is not simply giving money away, but neither can a particular reward be traced to the fee on your particular purchase.
The CFPB’s 2023 report puts average issuer interchange revenue at about 1.8% of general-purpose credit-card purchase volume and says rewards expense was almost 90% of interchange revenue. Its 1.6 cents earned per dollar figure applies to *rewards-card spending*. Those are different averages, so “the store pays 1.8 cents and you get 1.6 cents” is a useful illustration, not transaction-by-transaction accounting. Any remainder is not automatically bank profit.
When a store charges everyone the same price, some card-acceptance cost can be built into that price. Cash and debit customers may then help fund rewards they do not receive. A […