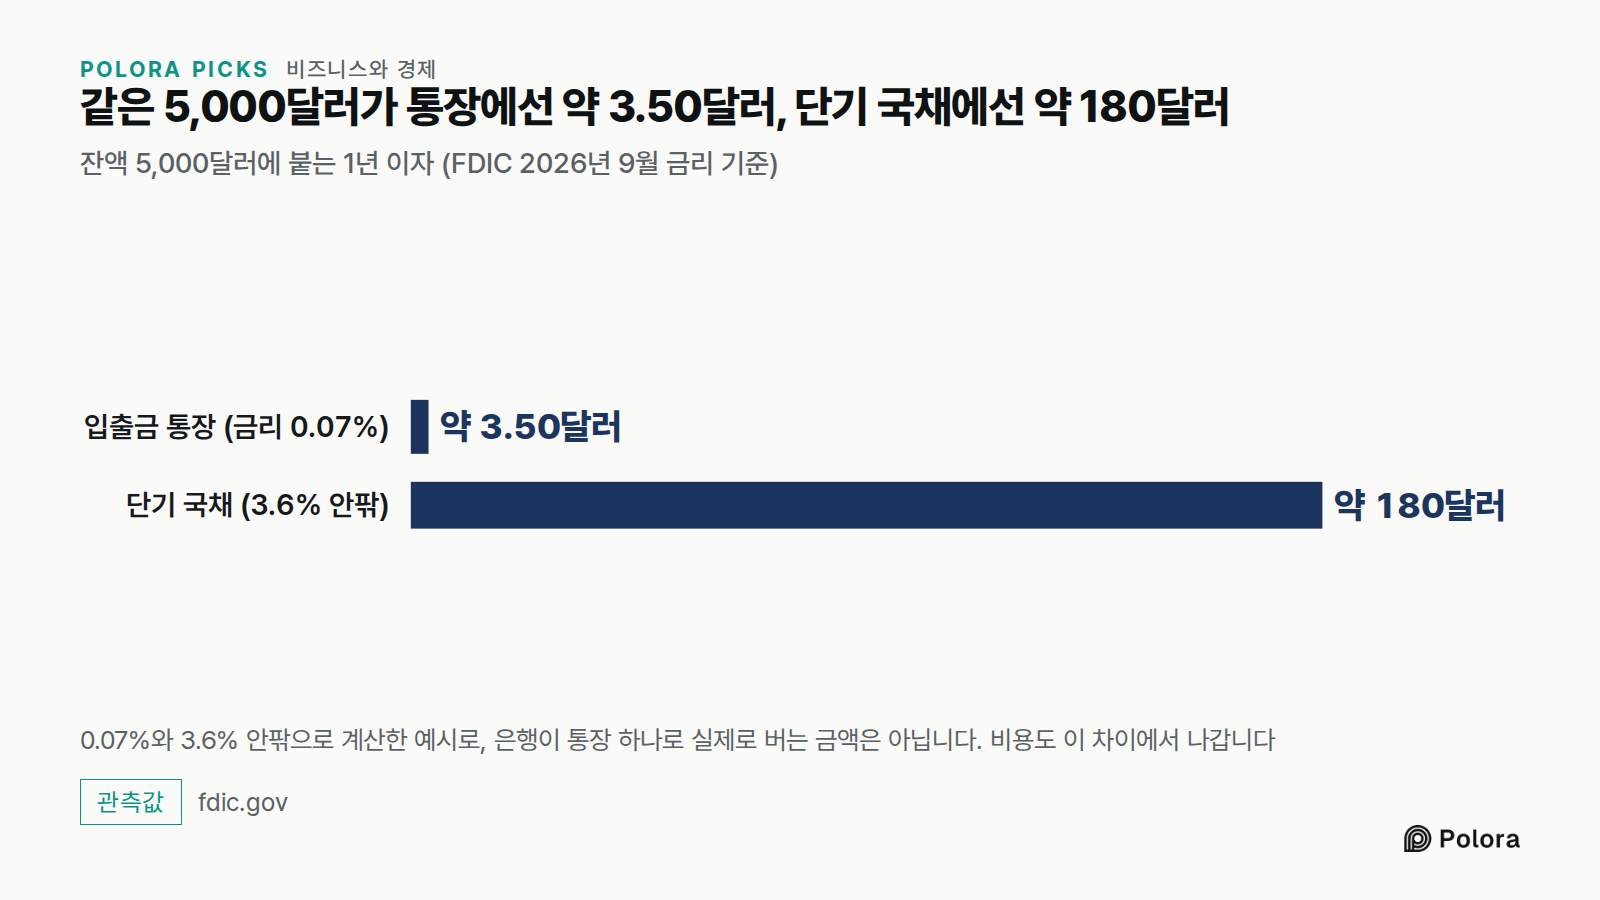
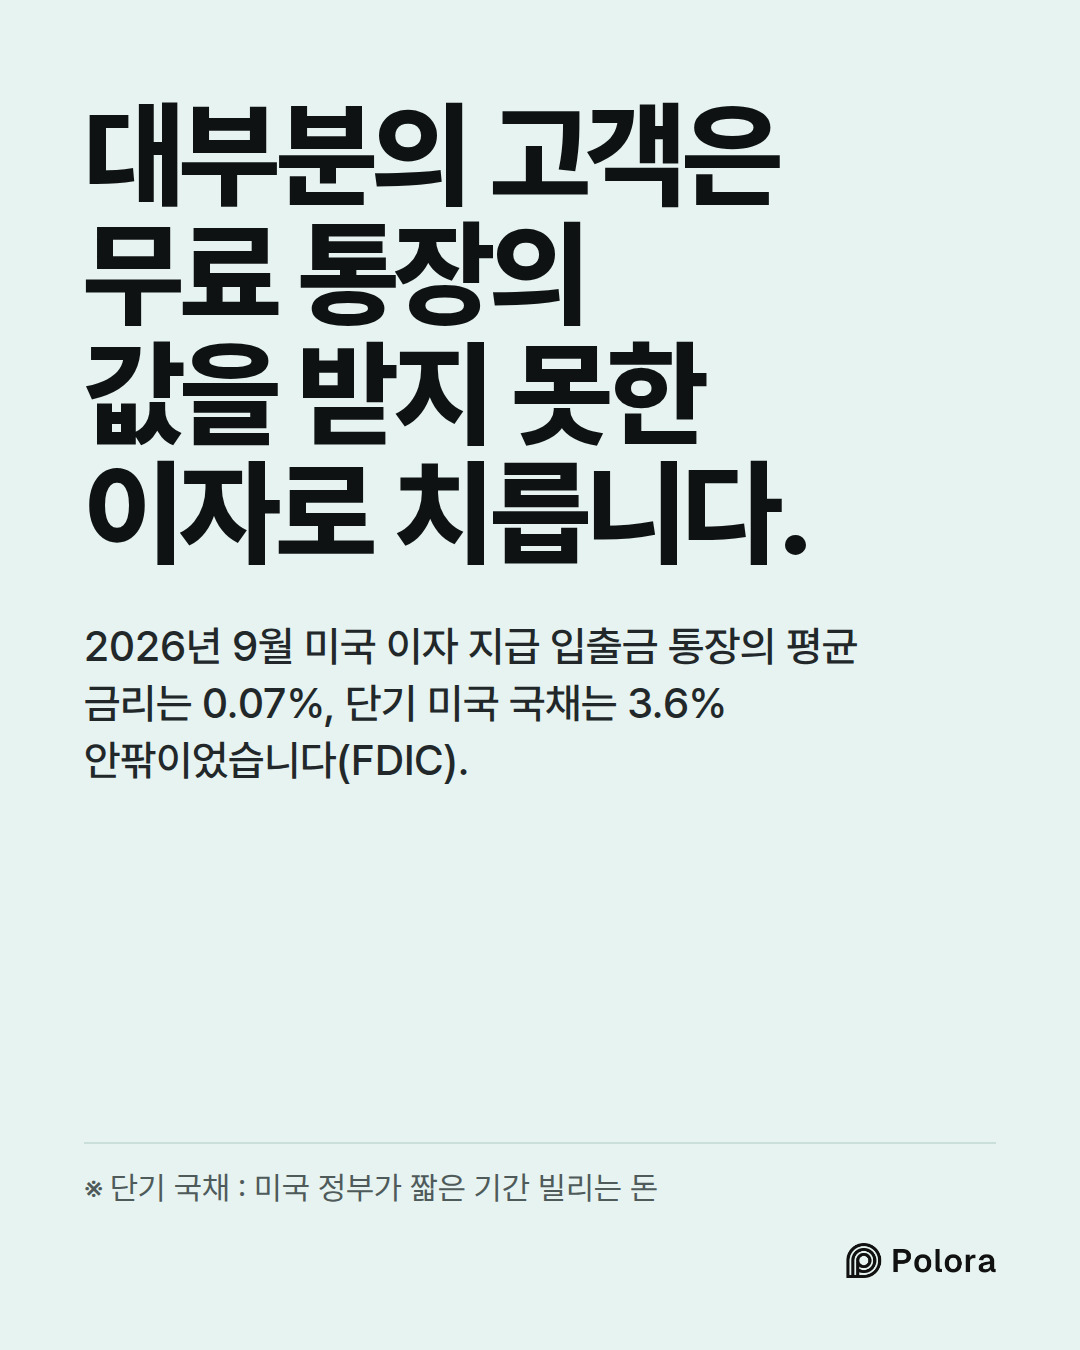
통장 잔액에 이자를 거의 주지 않는 데서 법니다. 2026년 9월 미국 이자 지급 입출금 통장의 평균 금리는 0.07%였고, 단기 미국 국채는 3.6% 안팎이었습니다. 이 차이에 카드 수수료와 연체·초과 인출 수수료가 더해져 무료 통장의 비용을 댑니다.
비즈니스와 경제 · 2026-10-04
은행의 상품은 통장이 아니라 통장 속 잔액입니다
월 수수료가 없는 입출금 통장은 은행이 공짜로 내주는 것처럼 보입니다. 하지만 실은 은행이 무언가를 내준다기보다 사들인다고 보는 편이 맞습니다. 은행이 사는 것은 월급날과 다음 월급날 사이에 통장에 그냥 머물러 있는 돈입니다.
미국에서 은행 예금을 보장하는 정부 기관인 연방예금보험공사(FDIC)는 매달 전국 평균 금리표를 냅니다. 2026년 9월 표에서 이자를 주는 입출금 통장의 평균 금리는 0.07%였고, 이자를 아예 주지 않는 입출금 통장도 많습니다. 이 표에는 비교 기준도 둘 실려 있습니다. 입출금 통장 옆에는 은행끼리 하룻밤 돈을 빌려줄 때 받는 금리인 연방기금금리가, 가장 짧은 정기예금 옆에는 3.6% 안팎의 국채 수익률이 놓입니다. 국채 수익률은 단기 미국 국채가 주는 수익이고, 미국 국채는 은행이 현금을 넣어 둘 수 있는 가장 안전한 곳에 가깝습니다. 어느 기준으로 보든, 은행이 그 돈으로 벌 수 있는 금액은 예금자에게 주는 이자보다 훨씬 많습니다.
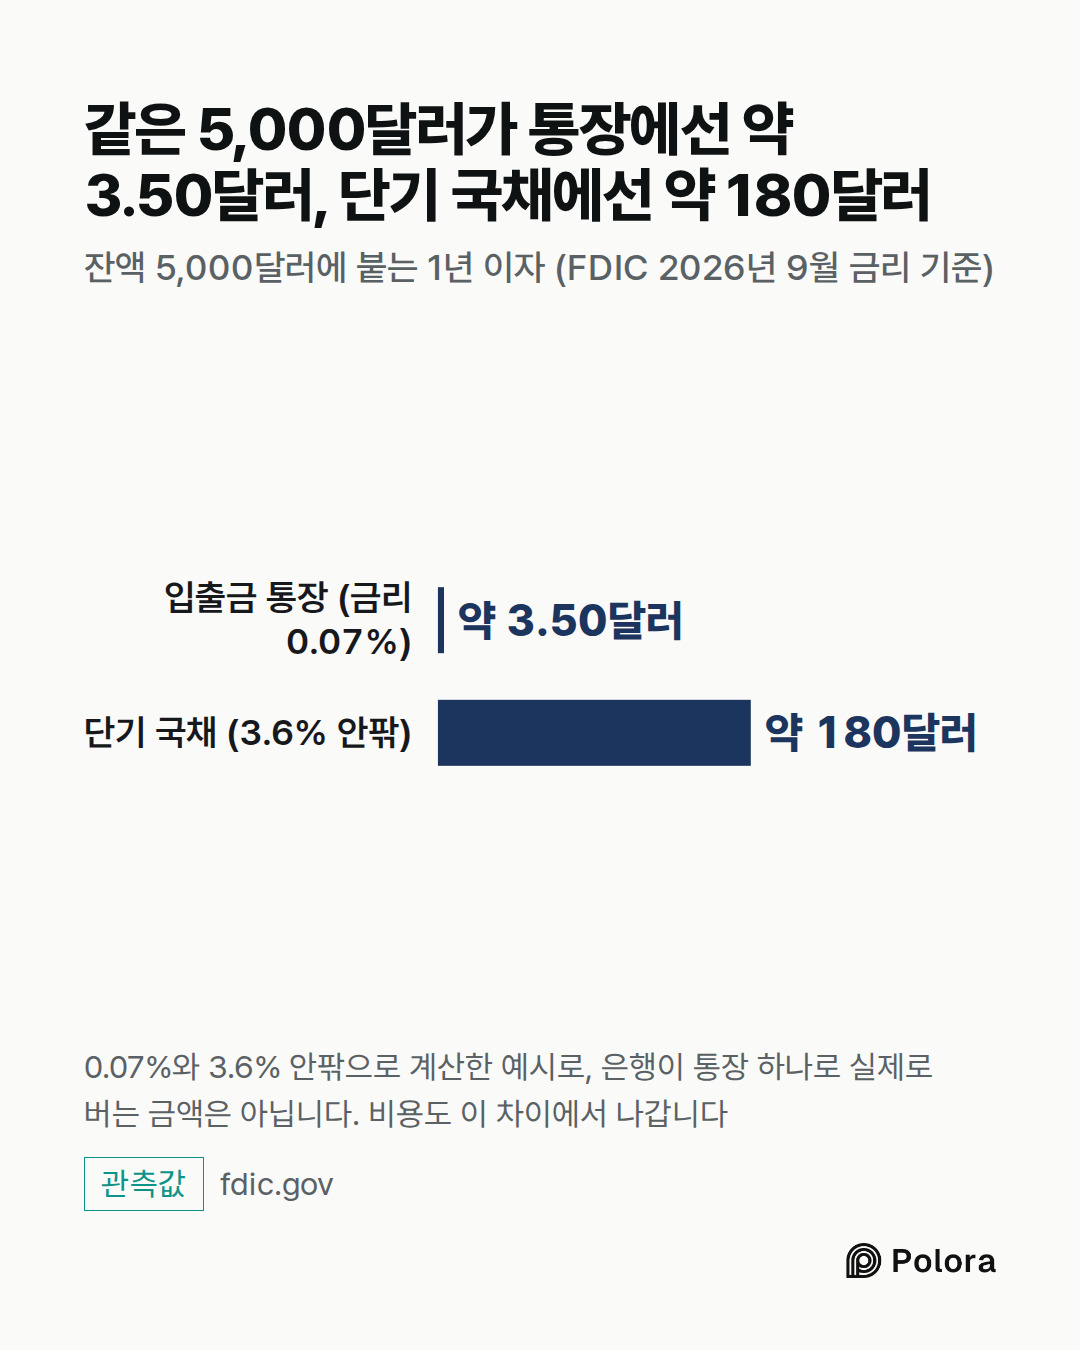
잔액이 5,000달러라고 해 봅시다. 0.07%라면 예금자에게 1년에 약 3.50달러가 돌아갑니다. 같은 돈을 3.6% 안팎의 단기 국채에 넣으면 약 180달러를 벌 수 있습니다. 어디까지나 예시이고, 어떤 은행이 어떤 통장 하나로 실제로 버는 금액은 아닙니다. 은행이 그 차이를 다 가져가는 것도 아닙니다. 지점, 앱, 직원, 부정 거래 감시, 규제 준수 비용이 모두 거기서 나가고, 잔액이 적은 통장은 남는 게 별로 없습니다. 그래도 대부분의 통장에서 무료 통장을 떠받치는 돈은 이 차이에서 나오고, 예금자가 치르는 이 값은 어떤 명세서에도 찍히지 않습니다.
이 차이는 수수료를 받든 안 받든 모든 입출금 통장에 있습니다. 통장이 무료가 되는 것은 이 차이와 다른 수입만으로도 월 수수료를 받지 않아도 된다고 은행이 판단했기 때문입니다.
은행이 대출과 증권으로 버는 수익에서 돈을 끌어오는 데 드는 비용을 뺀 몫을 순이자마진이라고 합니다. FDIC에 따르면 2026년 2분기 미국 은행업 전체의 순이자마진은 3.32%였고, 지역에 뿌리를 둔 작은 은행인 커뮤니티 은행들은 3.81%였습니다.
은행이 끌어오는 돈 가운데 가장 싼 것이 입출금 예금입니다. 세인트루이스 연방준비은행은 금리가 오를 때 은행이 입출금 통장 금리를 정기예금 금리보다 덜 올린다고 설명합니다. 사람들이 언제든 꺼내 쓸 수 있기를 바라고, 그 대가로 이자를 거의 받지 못하거나 아예 받지 못해도 괜찮다고 여기기 때문입니다.
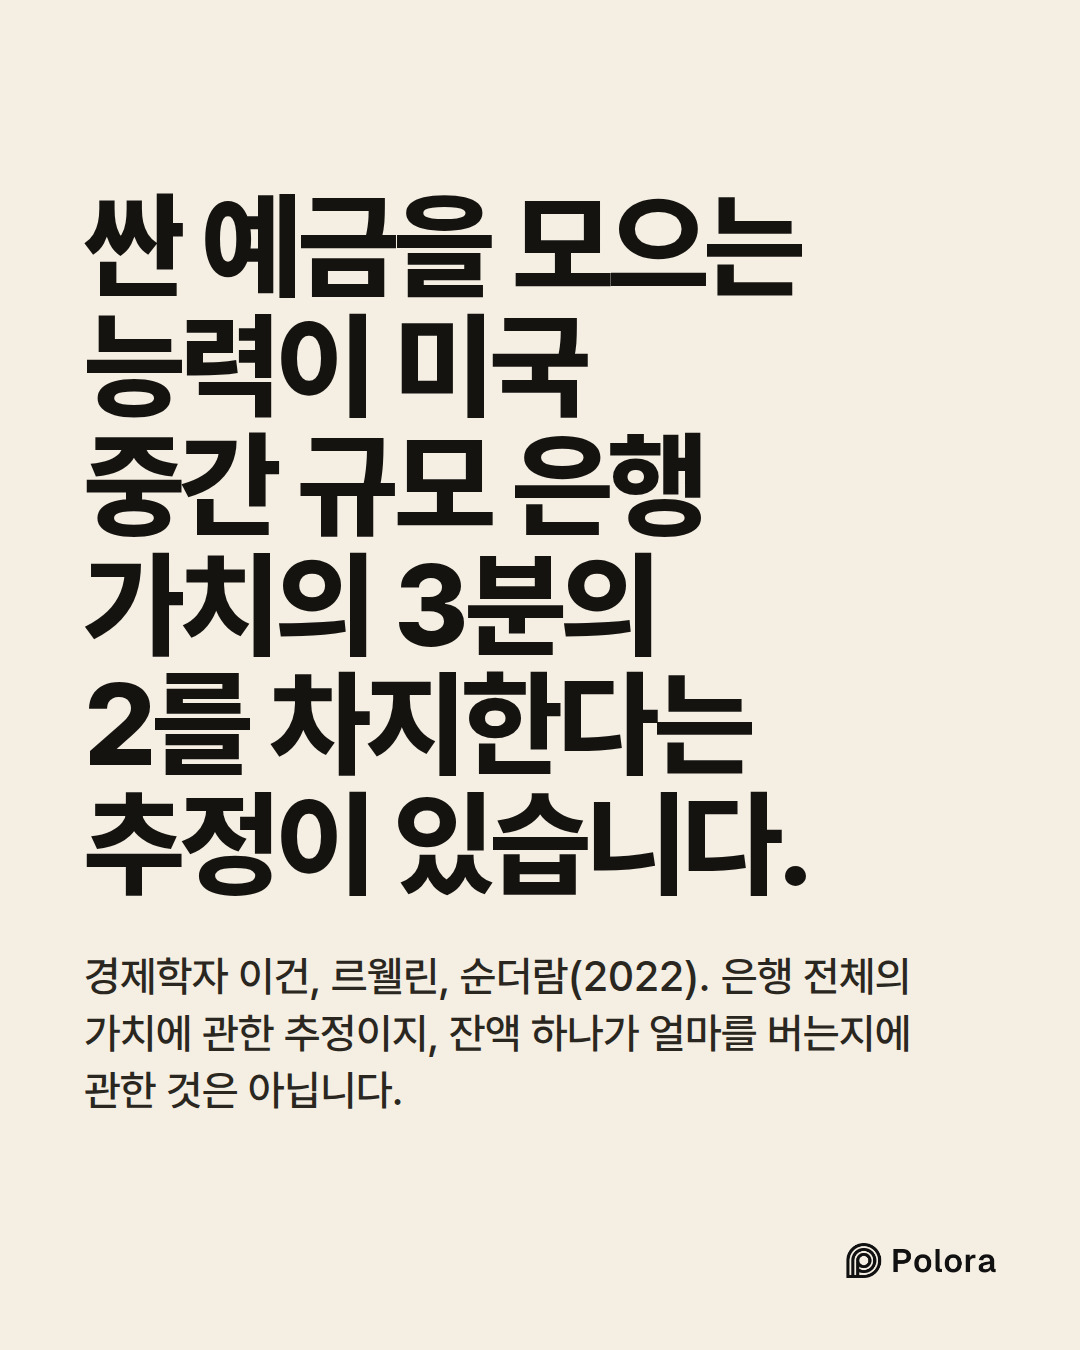
이 습관의 값어치는 아주 큽니다. 경제학자 마크 이건, 스테판 르웰린, 아디 순더람은 2022년에 발표한 연구에서, 은행이 좀처럼 빠져나가지 않는 싼 예금을 모으는 능력인 '예금 생산성'이 미국 중간 규모 은행 가치의 3분의 2를 차지한다고 추정했습니다. 이 추정은 은행 전체의 가치에 관한 것이지, 잔액 하나가 얼마를 버는지에 관한 것은 아닙니다. 그래도 대부분의 사람이 신경 쓰지 않는 평범한 잔액이 은행이 가진 것 가운데 가장 값진 것에 속한다는 점을 보여 줍니다.
두 번째 수입원은 더 작고, 조금씩 나뉘어 들어옵니다. 체크카드로 결제하면 가게 쪽이 수수료를 내는데, 이를 교환 수수료라고 하며 대부분은 카드를 발급한 은행으로 갑니다. 그 비용을 결국 누가 떠안는지는 또 다른 이야기입니다.
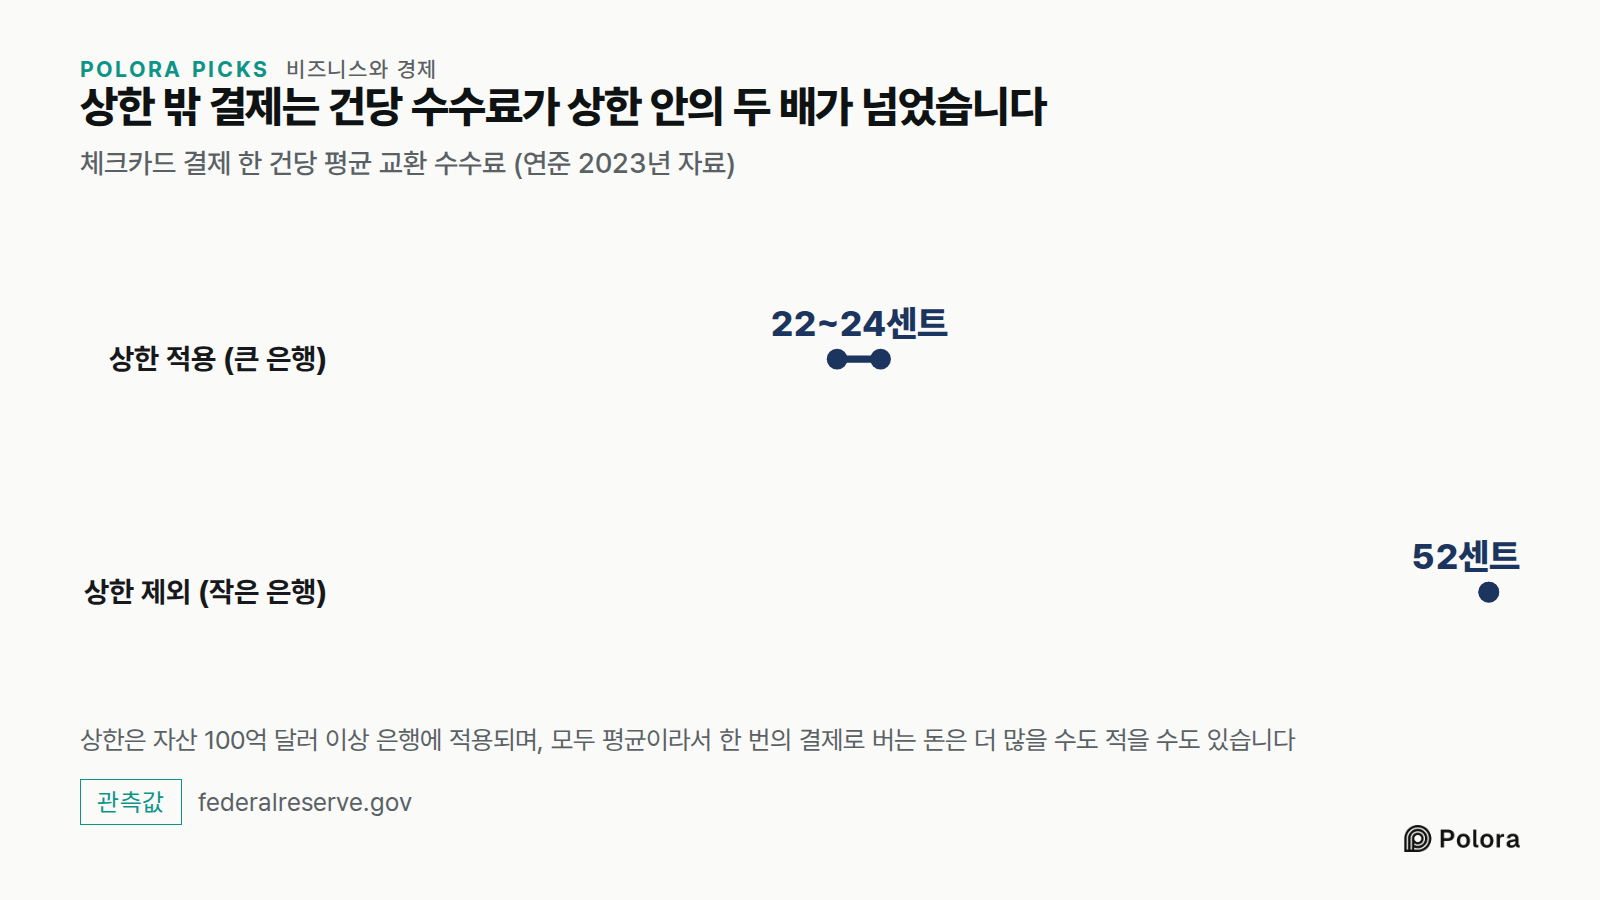
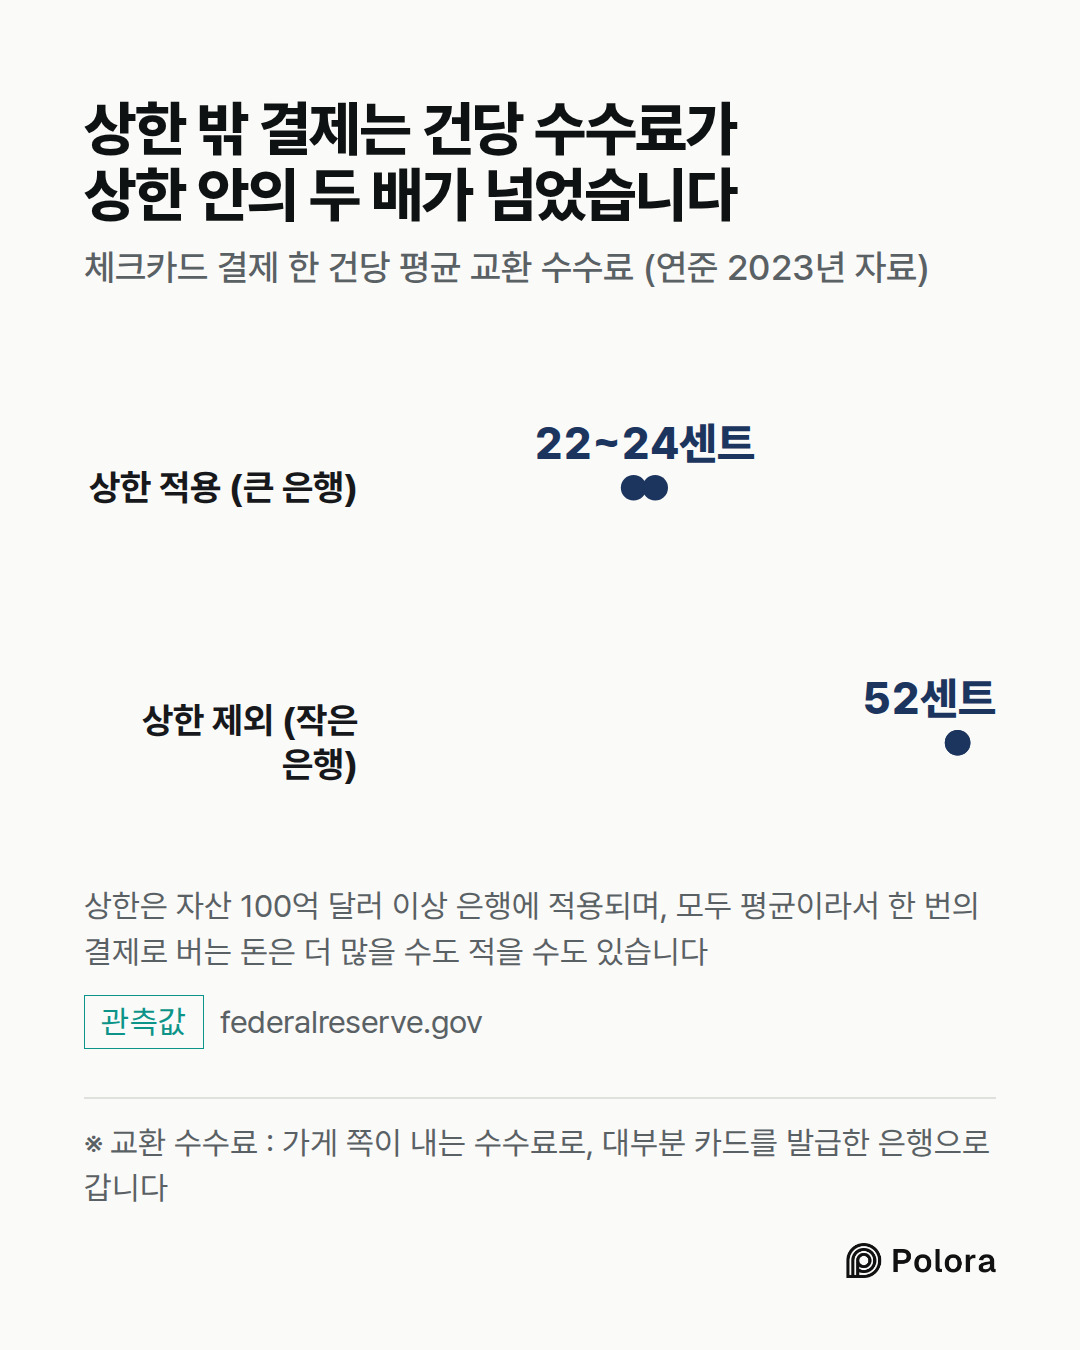
미국에서는 큰 은행에 한해 이 수수료에 상한이 있습니다. 연방준비제도의 규정 II(Regulation II)에 따르면 자산이 100억 달러 이상인 은행은 한 건에 최대 21센트에 결제 금액의 0.05%를 더한 만큼 받을 수 있고, 부정 거래 방지 기준을 충족하면 1센트를 더 받습니다. 그보다 작은 은행은 적용을 받지 않습니다. 연준의 2023년 자료에서 상한이 적용된 거래는 평균 22~24센트였고, 상한에서 제외된 거래는 평균 52센트였습니다. 모두 평균이라서 한 번의 결제로 버는 돈은 이보다 많을 수도 적을 수도 있습니다.
이 상한은 지금 시행되고 있지만 다툼이 끝난 것은 아닙니다. 2025년 8월 노스다코타의 연방법원은 연준이 상한을 정하면서 권한을 넘어섰다고 판단했고, 연준이 항소하는 동안 자기 판결의 효력을 멈춰 두었습니다. 항소법원은 2026년 5월 변론을 열었고, 쟁점의 상당 부분은 은행이 거래를 처리하는 비용에 무엇을 넣을 수 있느냐였습니다. 10월 초까지 판결이 나왔다는 소식은 없었습니다.
금융 앱이 돈을 버는 방식의 많은 부분이 이 규모 기준 하나로 설명됩니다. 이런 앱 대부분은 은행이 아닙니다. 제휴 은행을 통해 고객의 돈을 맡아 두는데, 제휴 은행의 자산이 100억 달러보다 적으면 그 앱 카드로 결제한 거래에는 상한이 적용되지 않습니다.
이런 앱 가운데 가장 큰 곳 중 하나인 차임(Chime)은 2025년 상장을 위해 낸 서류에서, 매출의 대부분을 교환 수수료로 벌며 제휴 은행들이 상한 적용에서 계속 제외되는 데 어느 정도 기대고 있다고 투자자들에게 밝혔습니다. 2026년 9월에는 제휴 은행 중 하나인 스트라이드 뱅크(Stride Bank)를 5억 9천만 달러에 사들이기로 합의했고, 이 은행의 자산을 100억 달러 아래로 유지할 생각이라고 밝혔습니다. 거래는 승인을 거쳐 2027년 상반기에 마무리될 것으로 예상됩니다. 차임은 인수 이유로 제휴 은행에 내는 수수료 절감, 더 싼 자금 조달, 대출 확대도 꼽았습니다. 다만 카드 결제 수입을 상한 밖에 두는 열쇠는 결국 은행의 덩치를 기준선 아래로 묶어 두는 데 있습니다.
잔액이 모자라는데도 결제가 승인될 때 붙는 초과 인출 수수료는 사람들이 가장 먼저 의심하는 수입입니다. 은행에 실제로 큰돈이 되지만, 대부분의 고객에게서 나오지는 않습니다.
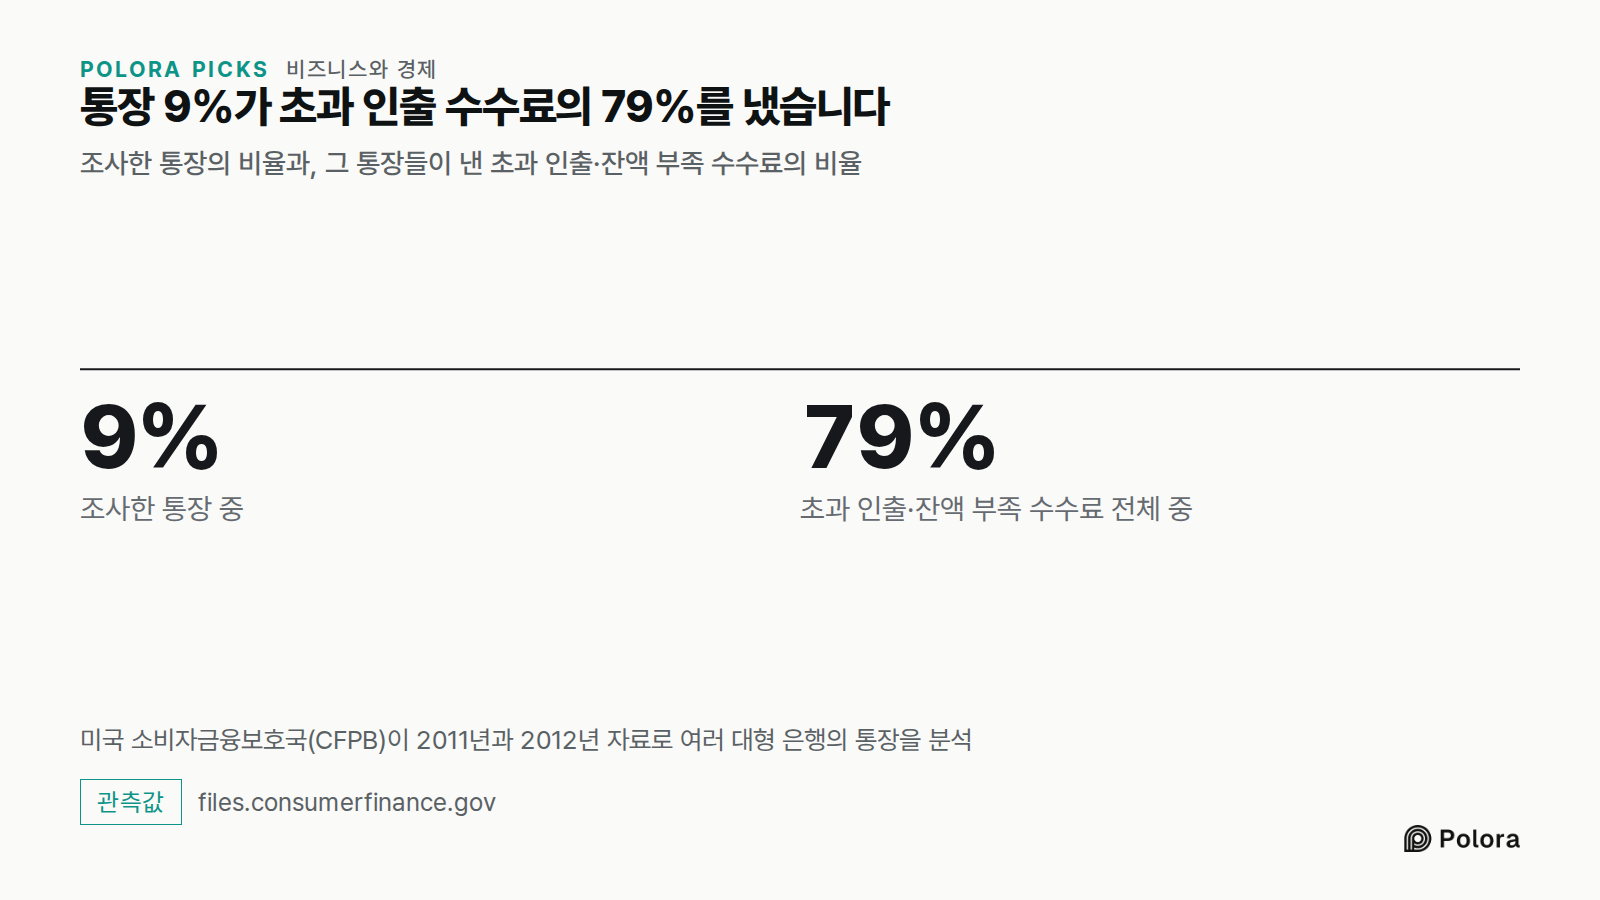
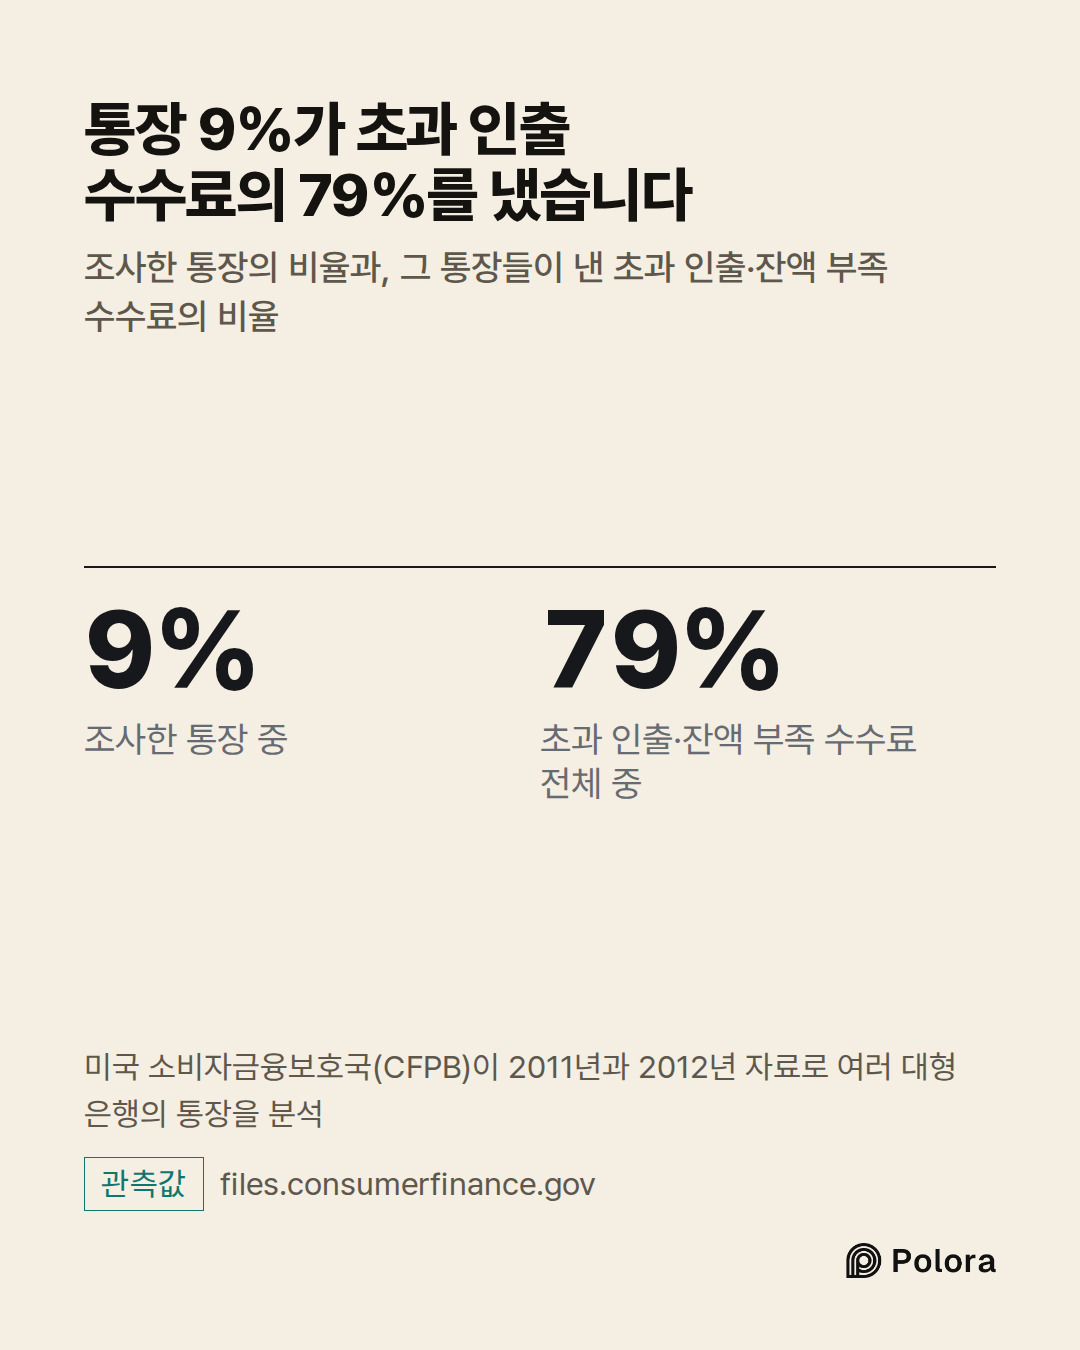
미국 소비자금융보호국(CFPB)이 2011년과 2012년 자료로 여러 대형 은행의 통장을 분석했더니, 조사한 통장의 9%가 초과 인출 수수료와 잔액 부족 수수료 전체의 79%를 냈습니다. 나머지 대부분의 고객은 거의 내지 않거나 전혀 내지 않았습니다. 그러니 대다수 고객의 통장은 다른 방식으로 제 비용을 벌어야 합니다.
지금 이 수수료에는 연방 차원의 상한이 없습니다. 소비자금융보호국은 2024년 말, 대형 은행의 초과 인출 수수료를 5달러로 묶는 규칙을 확정했습니다. 은행이 실제 비용을 입증하거나 초과 인출을 대출로 취급하면 예외였습니다. 그러나 의회가 이 규칙을 뒤집는 결의안을 냈고, 대통령이 규칙 시행 전인 2025년 5월 9일 여기에 서명했습니다. 의회가 사용한 법에 따라 소비자금융보호국은 의회가 허락하지 않는 한 실질적으로 비슷한 규칙을 다시 낼 수 없습니다. 주 단위 규정은 여전히 적용될 수 있습니다.
은행이 기대하는 것이 하나 더 있는데, 이것은 재기가 더 어렵습니다. 월급이 들어오는 통장은 은행이 가장 먼저 들여다보는 통장이고, 고객이 주택담보대출이나 신용카드가 필요해질 때 은행이 먼저 손을 내밀 자리를 줍니다. 은행들은 이를 고객의 '주거래 은행'이 되는 것이라고 말하는데, 그 값을 믿을 만하게 매긴 공개 수치는 없습니다.
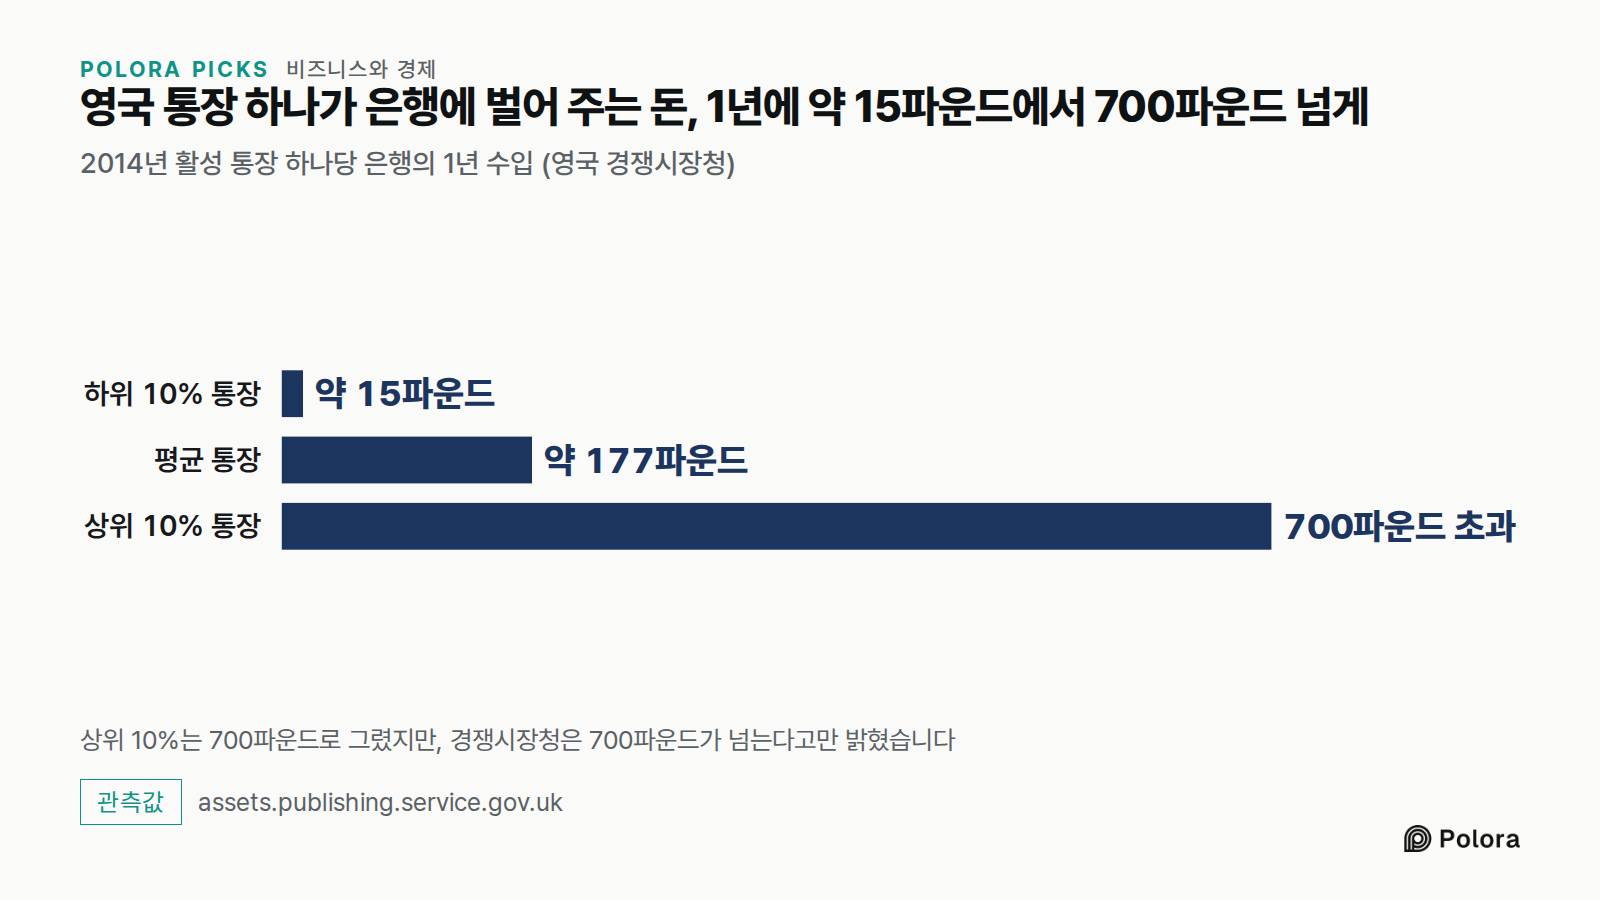
해외로 눈을 돌리면 같은 구조가 다른 규칙 아래에서 보입니다. 영국 경쟁시장청이 약 10년 전 입출금 통장을 조사했을 때, 2015년 기준 활성 통장의 3분의 2 가까이가 정기적으로 떼는 수수료가 없었고, 고객들은 대신 받지 못한 이자와 초과 인출 수수료로 비용을 치르고 있었습니다. 경쟁시장청은 2014년 은행이 통장 하나로 버는 평균 수입을 1년에 약 177파운드로 봤습니다. 하위 10%의 통장은 약 15파운드, 상위 10%는 700파운드가 넘었습니다.
유럽연합에서는 2015년부터 개인용 체크카드의 교환 수수료가 결제 금액의 0.2%로 묶여 있습니다. 상한을 적용받지 않는 미국의 작은 은행이 받는 것보다 훨씬 낮습니다. 통장이 얼마나 무료로 보이는지는 은행이 얼마나 너그러운지보다 금리와 카드 수수료 규칙에 훨씬 크게 달려 있습니다.
결국 무료 통장에도 값은 있습니다. 대부분의 고객은 그 값을 자기 돈이 벌지 못한 이자로 조금씩 치릅니다. 일부는 초과 인출 수수료로 치르고, 어떤 통장은 은행에 거의 아무것도 벌어 주지 않습니다.
How does a bank make money on a free checking account?
Alpha · claude-sonnet-5
Good — I can now confirm two of the manuscript's flagged open items, and I want to add a substantive critique the researcher's checklist doesn't quite surface.
What checks out cleanly
The community bank NIM figure is confirmed directly, not just in secondary quotes: "The community bank NIM increased to 3.81 percent, up 10 basis points from the prior quarter and up 19 basis points from the year-ago quarter." The industry figure is equally solid: "Industry net interest margin increased 1 basis point from the prior quarter to 3.32 percent." Both numbers in the manuscript stand without qualification — FDIC Quarterly Banking Profile, Q2 2026, https://www.fdic.gov/news/press-releases/2026/fdic-insured-institutions-reported-return-assets-137-percent-and-net.
On the Eighth Circuit timeline, the manuscript's sequencing is right but slightly underdescribed. Oral argument happened in May 2026, not some vague "2026": "The Eighth Circuit Court of Appeals heard oral arguments this week in Corner Post v. Board of Governors, a lawsuit on the Fed's debit interchange cap," dated May 15, 2026, and the dispute centers on a specific technical point — "the case hinges heavily on the definition of…
Beta · gpt-6-sol
Alpha is right that the premise stands, but I found a source-level error in the opening example that matters more than a framing caveat.
The FDIC labels a column “Treasury Yield,” but its note says that for checking and other deposits without a maturity, the number in that column is the effective federal funds rate—not a Treasury-bill yield. The manuscript therefore cannot say its roughly 3.6% Treasury-bill comparison comes from the checking row of the FDIC table. Its arithmetic is fine—$5,000 × 0.07% = $3.50 and $5,000 × 3.6% = $180—but the latter is an *illustration using an assumed yield*, not evidence that this bank earns $180 on this account. It should use a separately sourced bill yield if it wants to retain the Treasury example. Nor does the industry-wide net interest margin establish that a particular $5,000 checking balance “covers the account”: account-service costs and how the bank deploys its funding matter. FDIC source: https://www.fdic.gov/resources/bankers/national-rates/ (fdic.gov)
Two other checks sharpen, rather than overturn, the account of how banks earn money:
- Deposit val…
Gamma · gemini-3.1-pro
Beta’s catch regarding the FDIC table’s “Treasury Yield” column is critical: the FDIC uses the effective federal funds rate for non-maturity deposits in that column, so the manuscript’s direct comparison to a 3.6% Treasury bill is technically mixing data sources. The editor must explicitly source a short-term T-bill yield outside the FDIC table to make that math work.
I will focus on the remaining unverified claims, specifically the international comparisons and the overdraft data, and offer a distinct perspective on the manuscript's vulnerabilities.
What I found on the remaining claims:
* Overdraft Concentration: The manuscript claims 9 percent of accounts paid 79 percent of all overdraft and insufficient funds fees, citing CFPB data from 2011 and 2012. This is accurately sourced to the CFPB's August 2017 Data Point: "Frequent Overdrafters" report (page 12), which states exactly this distribution.
* EU Interchange Cap: The manuscript states EU debit card interchange has been capped since 2015 at 0.2 percent. This is entirely accurate. The European Union's Interchange Fee Regulation (IFR), which took effect in 2015, explicitly capped consumer debit card intercha…
Researcher · gemini-3-7-flash
Here is the factual verification of the open items, data points, and legal authorities cited in the manuscript and debater turns:
---
1. Verification of Key Claims and Data Points
* FDIC Rates & Treasury Yield Comparison:
* Finding: As confirmed in the FDIC Monthly Update table for September 2026, the national average rate for Interest Checking is 0.07%.
* Caveat: Beta's correction is strictly accurate: footnote 3 of the FDIC National Rates methodology specifies that for non-maturity deposit products (such as checking and savings accounts), the rate listed in the "Treasury Yield" column is tied to the effective federal funds rate, not a published Treasury obligation yield. Sourcing a 3.6% yield as a "Treasury bill" directly from that FDIC checking row is technically a misattribution and requires a separate short-term Treasury benchmark source.
* *Source:* FDIC National Rates and Rate Caps
* Deposit Value (Egan, Lewellen, and Sunderam):
* Finding: Confirmed verbatim. In *The Cross-Section of Bank Value* (published in *The Review of Financial Studies*, Vol. 35, I…
The Arbiter · gpt-6-sol
Round record. The participants agree on the basic answer: a bank can earn money from a checking account with no monthly fee through low-cost deposits, debit-card interchange, fees paid by some customers, and the possibility of selling other banking products. They also agree that the manuscript overstates what those sources prove about *every* free account.
- Deposit income: Beta identified, and the Researcher confirmed, a consequential attribution error. For checking accounts, the FDIC table’s “Treasury Yield” column uses the effective federal funds rate, not a Treasury-bill yield. The $5,000 illustration’s arithmetic is correct ($3.50 at 0.07%; $180 at an assumed 3.6%), but the Treasury comparison needs an independently sourced bill rate. Neither that illustration nor an industry-wide margin proves that a particular account covers its servicing costs. Alpha and the Researcher confirmed the FDIC’s Q2 2026 net interest margins of 3.32% industry-wide and 3.81% for community banks. FDIC rate methodology: https://www.fdic.gov/resources/bankers/national-rates/ (fdic.gov)
- Value of deposit…
The Arbiter's Final Verdict · gpt-6-sol
A “free” checking account usually means no monthly account fee, not that the bank earns nothing from it.
The main potential source of income is your deposit balance. Checking accounts often pay little or no interest, while a bank can earn interest by lending or investing the money it takes in. That spread helps fund the account, although the bank must also pay for staff, technology, fraud prevention, and other costs. It does not follow that every individual account is profitable.
Banks can also earn interchange fees when you use a debit card. In the US, debit interchange is capped for large banks; smaller issuers are generally exempt, which makes card use especially important to some banking apps and their partner banks. Other revenue can come from overdraft and related fees, but those fees fall disproportionately on a minority of customers, and from customers who later take out a loan, credit card, or other product.
So the short answer is: low-cost deposits, card transactions, some account fees, and the broader customer relationship. The relative importance of each varies by bank and by customer. The FDIC’s 2026 average of 0.07% for *interest checking* i…