How does a bank make money on a free checking account?
Mostly by paying almost nothing on your balance. In September 2026 US interest checking averaged 0.07 percent while short-term Treasury debt paid around 3.6 percent. That gap, plus card and penalty fees, is what pays for most free accounts.
Business & Economy · 2026-10-04
Your balance is the product
A checking account with no monthly fee looks like something the bank gives away. It is closer to something the bank buys. What it buys is the money you leave sitting there between paydays.
The FDIC, the US agency that insures bank deposits, publishes national rate tables every month. In the September 2026 table the average interest checking account paid 0.07 percent, and many checking accounts pay nothing at all. The table also shows two yardsticks. Beside checking accounts it uses the federal funds rate, what banks charge each other overnight. Beside the shortest certificates of deposit (savings locked up for a fixed term), it lists a Treasury yield of around 3.6 percent, the return on short-term US government debt and about the safest place a bank can park cash. Whichever yardstick you take, the bank can earn far more on the money than it pays you.
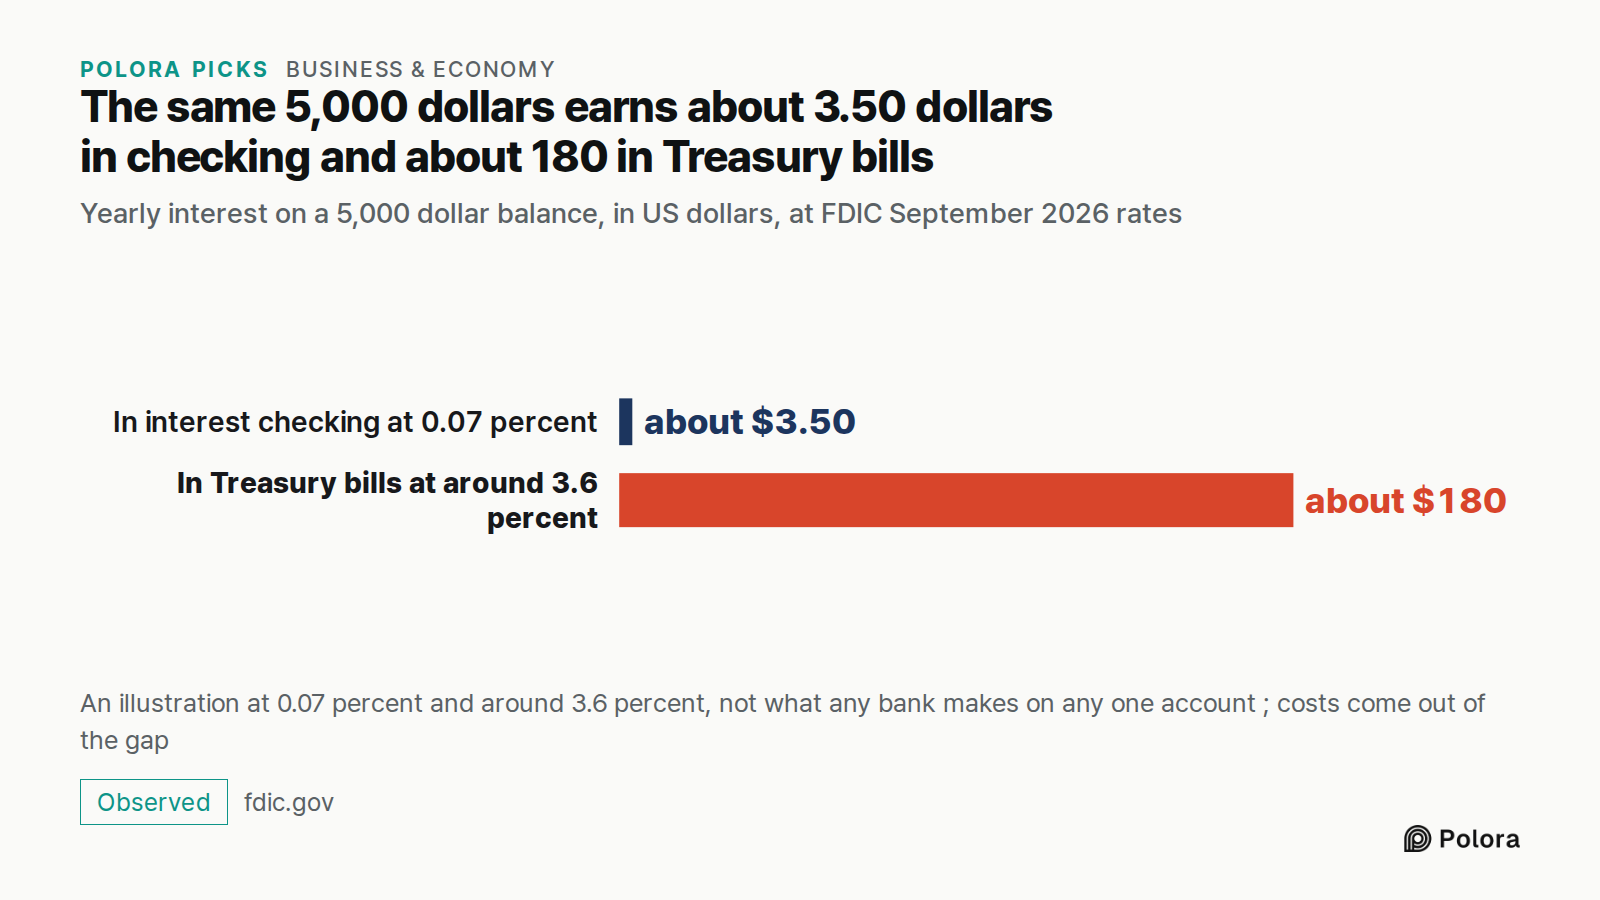
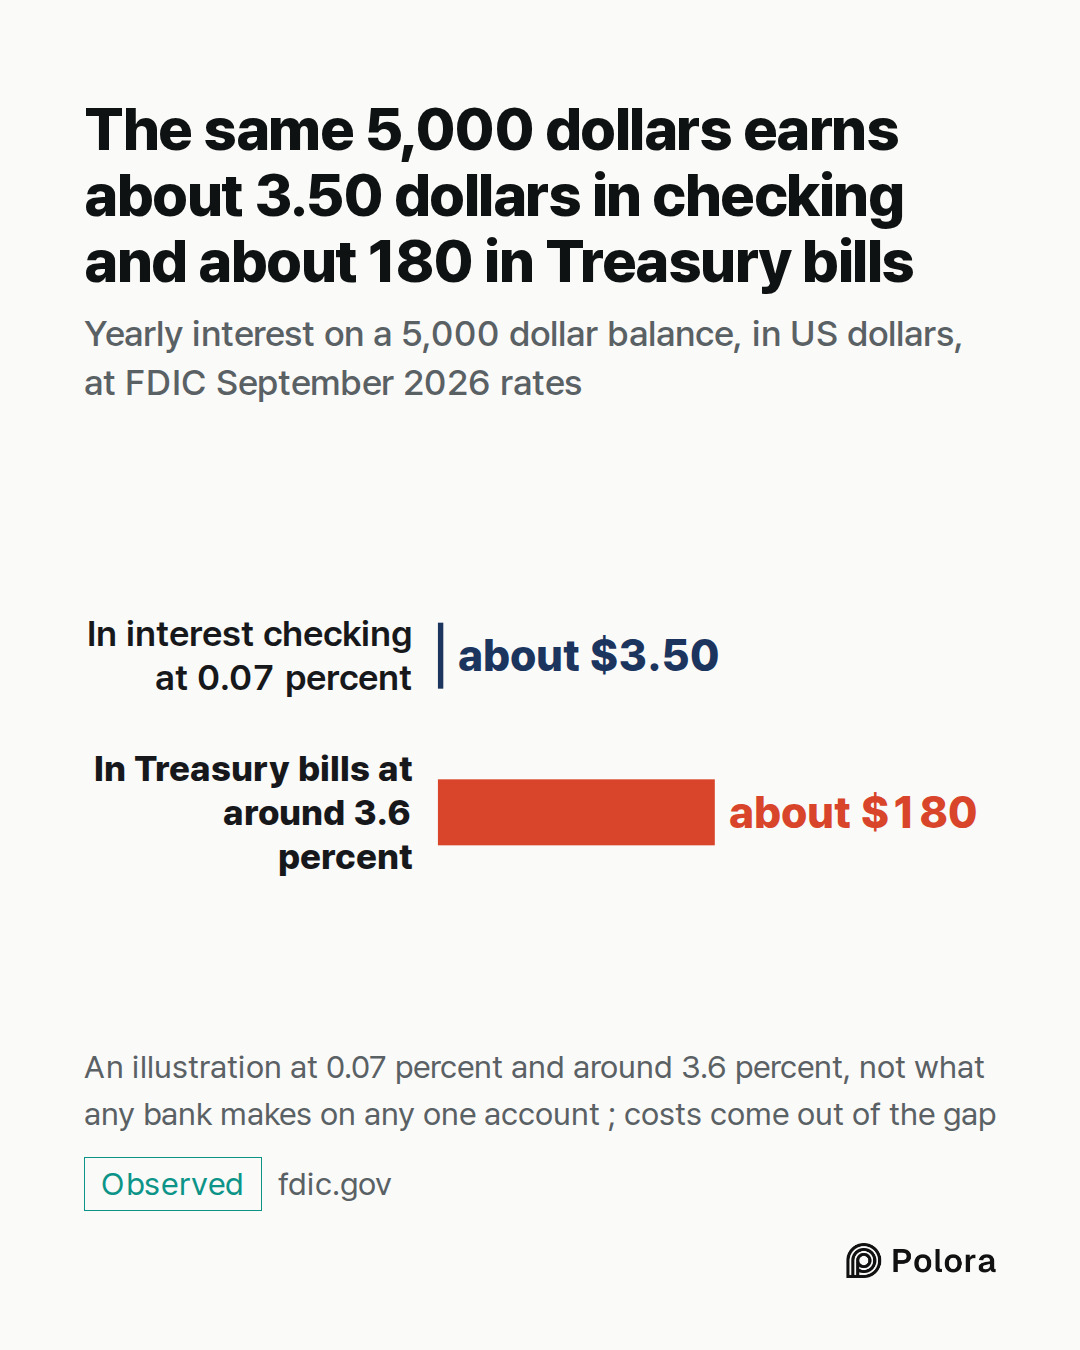
Take a balance of 5,000 dollars. At 0.07 percent it earns its owner about 3.50 dollars a year. In Treasury bills at around 3.6 percent, the same money would earn about 180 dollars. That is an illustration, not what any one bank makes on any one account. The bank does not keep all of that difference. Branches, the app, staff, fraud checks and compliance all come out of it, and an account with a small balance leaves little to work with. But for most accounts the gap is where the money for a free account comes from, and nobody sees it charged.
This gap exists on every checking account, whether or not it charges a fee. What makes an account free is the bank's decision that the gap and its other income are enough without a monthly charge.
Yearly interest on a 5,000 dollar balance, in US dollars, at FDIC September 2026 rates
Across every US bank, the difference between what banks earn on loans and securities and what they pay for their funding is measured as the net interest margin. In the second quarter of 2026 it was 3.32 percent for the industry as a whole, according to the FDIC. For community banks, the smaller local lenders, it was 3.81 percent.
Checking deposits are the cheapest part of that funding. The Federal Reserve Bank of St. Louis notes that when interest rates rise, banks raise what they pay on checking accounts less than on certificates of deposit, because people want ready access to the money and are willing to earn little to no interest on it.
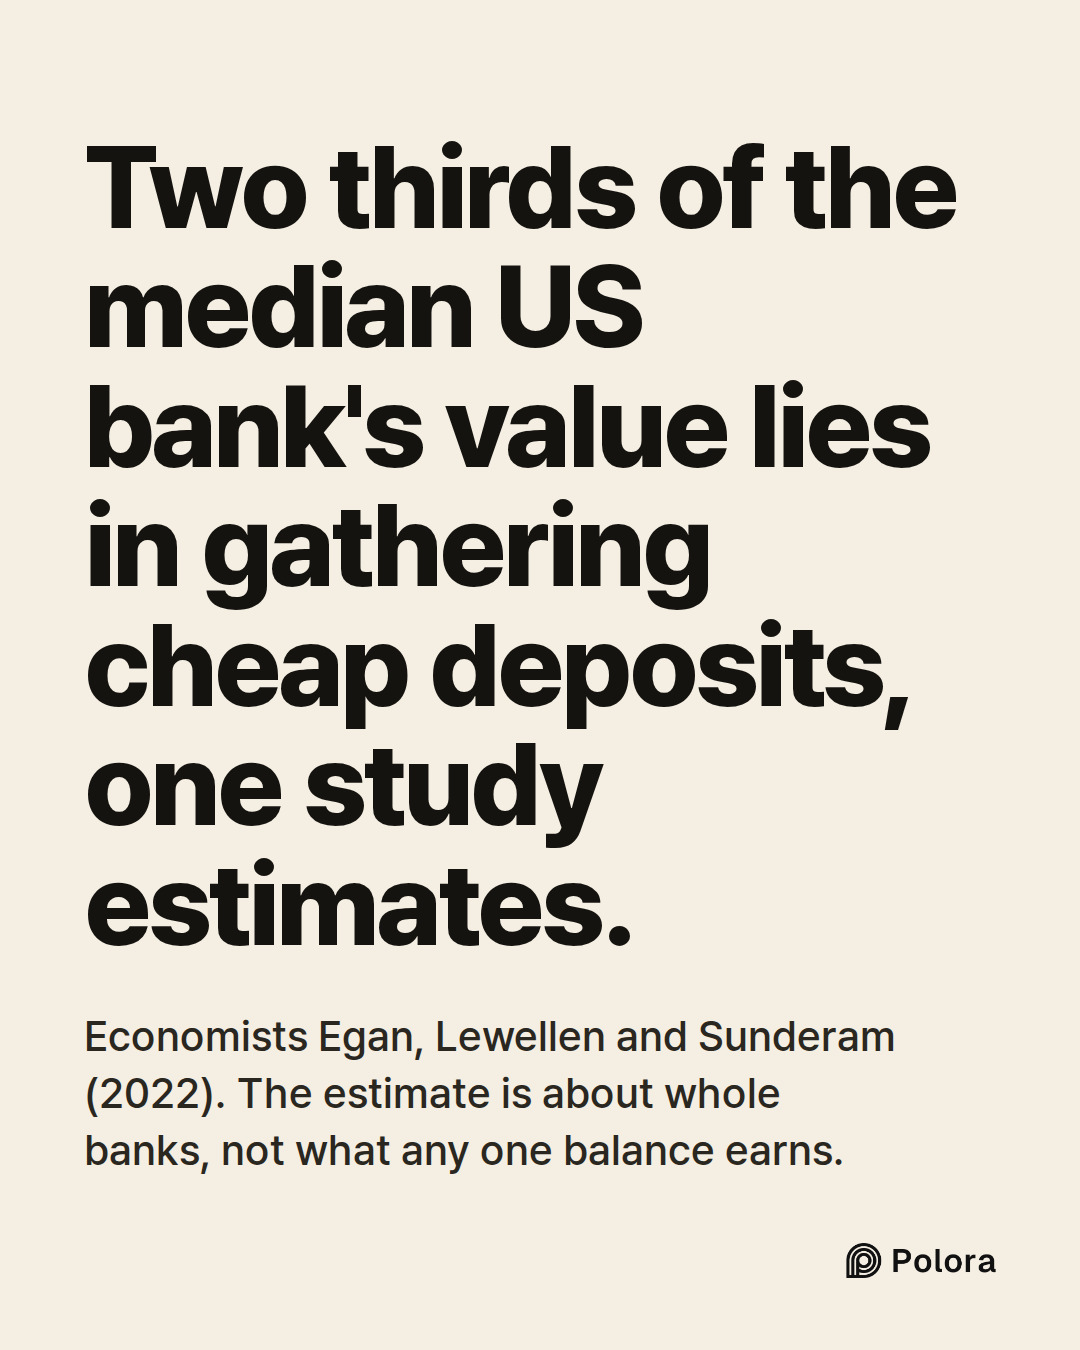
That habit is worth a great deal. In a study published in 2022, economists Mark Egan, Stefan Lewellen and Adi Sunderam estimated that deposit productivity, a bank's ability to gather cheap deposits that rarely leave, accounts for two thirds of the value of the median US bank. The estimate is about what whole banks are worth, not about what any one balance earns. Still, it suggests that the everyday balance most people never think about is among the most valuable things a bank holds.
The second stream is smaller and arrives in pieces. When you pay with a debit card, the shop's side of the transaction pays a fee, called interchange, and most of it goes to the bank that issued your card. Who ends up bearing that cost is a separate story.
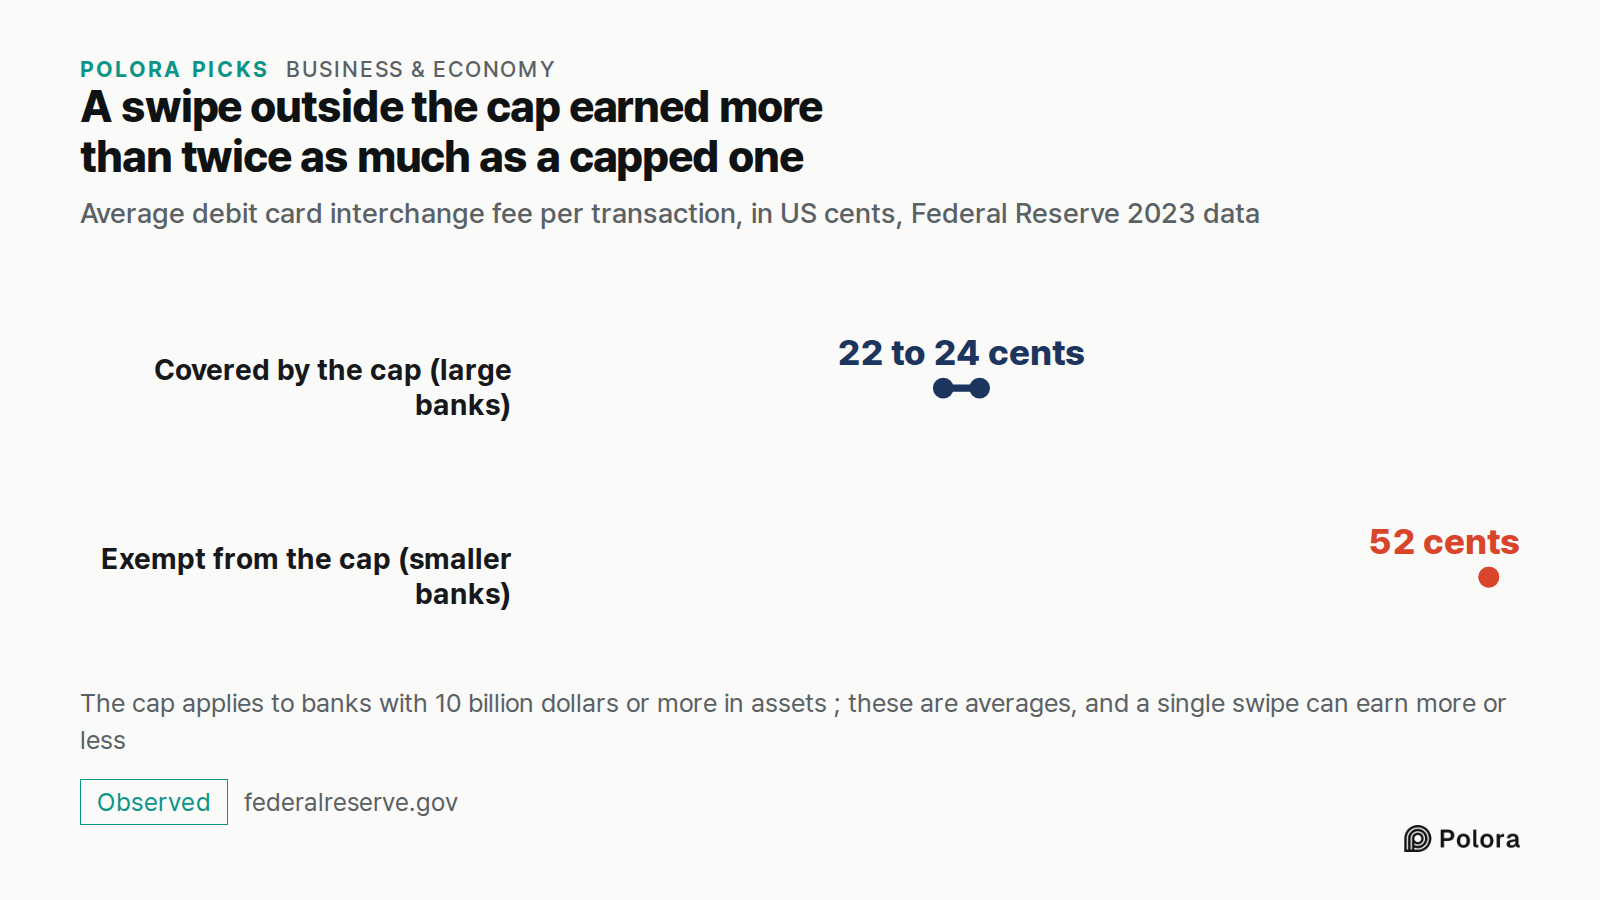
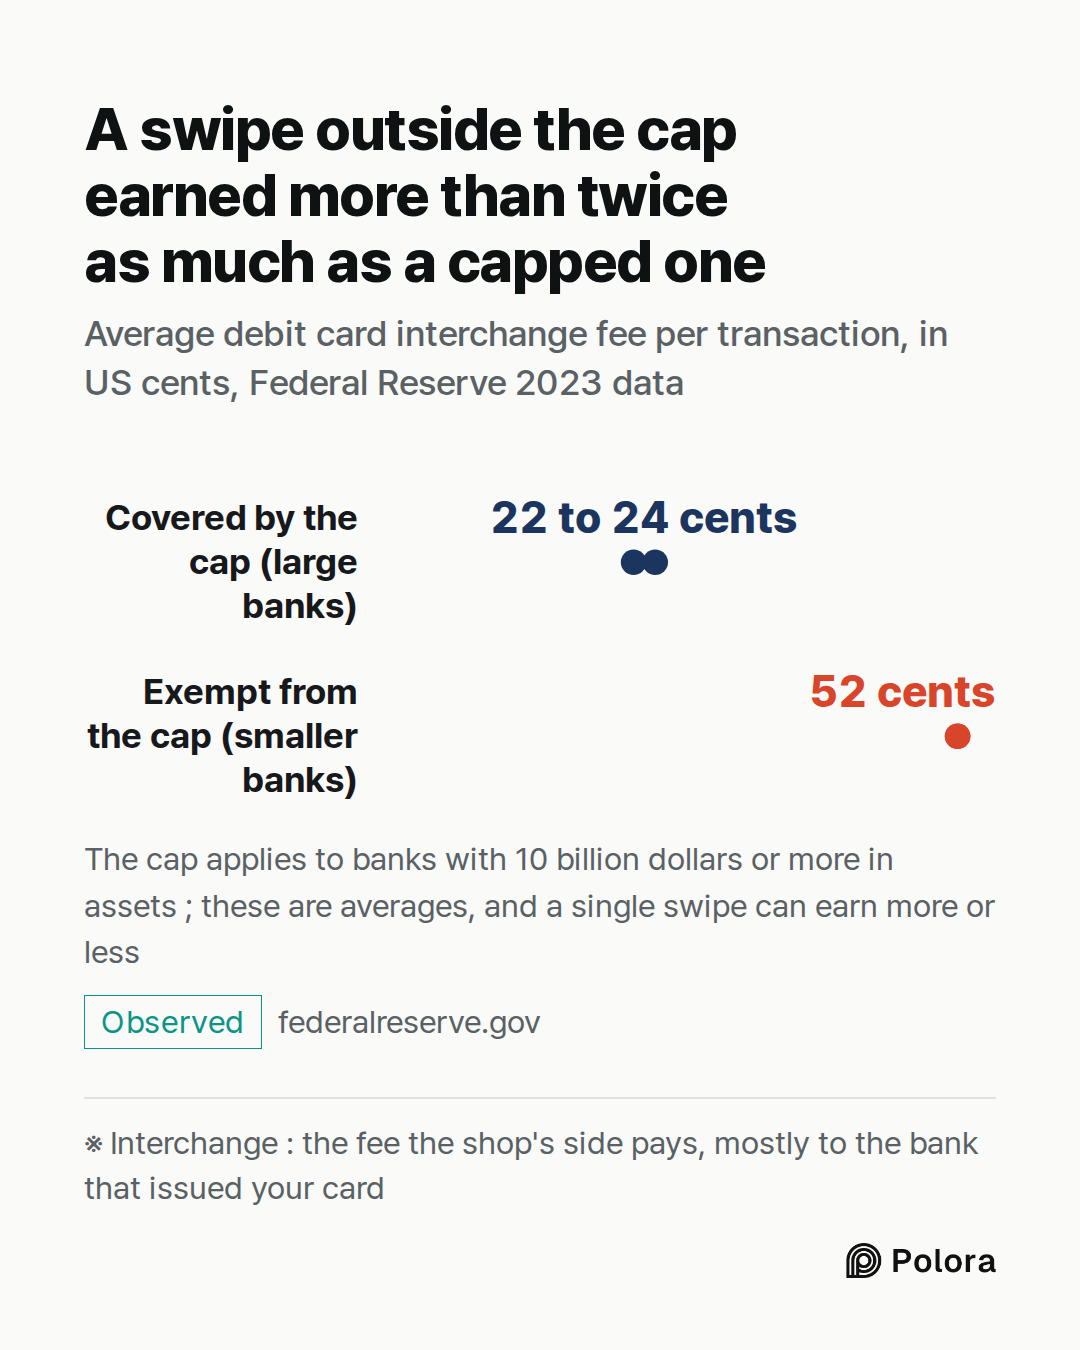
In the United States the fee is capped for large banks. Under the Federal Reserve's Regulation II, a bank with 10 billion dollars or more in assets may collect at most 21 cents plus 0.05 percent of the purchase, plus 1 cent if it meets fraud prevention standards. Banks below that size are exempt. In the Fed's 2023 data, covered transactions averaged 22 to 24 cents, while transactions exempt from the cap averaged 52 cents. These are averages ; a single swipe can earn more or less.
The cap is in force but not settled. In August 2025 a federal court in North Dakota found that the Fed had exceeded its authority in setting it, then paused its own ruling while the Fed appeals. The appeals court heard arguments in May 2026, with much of the case turning on what counts as a bank's cost of processing a transaction, and no decision had been reported by early October.
Average debit card interchange fee per transaction, in US cents, Federal Reserve 2023 data
That one size limit explains a lot about banking apps. Most of them are not banks. They hold customers' money through a partner bank, and when the partner has less than 10 billion dollars in assets, swipes on the app's card are not subject to the cap.
Chime, one of the largest such apps, told investors in its 2025 filing for a stock listing that it earns the substantial majority of its revenue through interchange fees, and that it depends in part on its partner banks keeping their exemption from the cap. In September 2026 it agreed to buy Stride Bank, one of its partner banks, for 590 million dollars, and said it intends to keep the bank's assets below 10 billion dollars. The deal is expected to close in the first half of 2027, subject to approvals. Chime also named savings on partner bank fees, cheaper funding and more lending among the reasons for the purchase, but staying under the size limit is what keeps its swipe income outside the cap.
Overdraft fees are large but fall on a few accounts
Overdraft fees, charged when a payment goes through without enough money in the account, are the income people most often suspect. They are real money for banks, but they do not come from most customers.
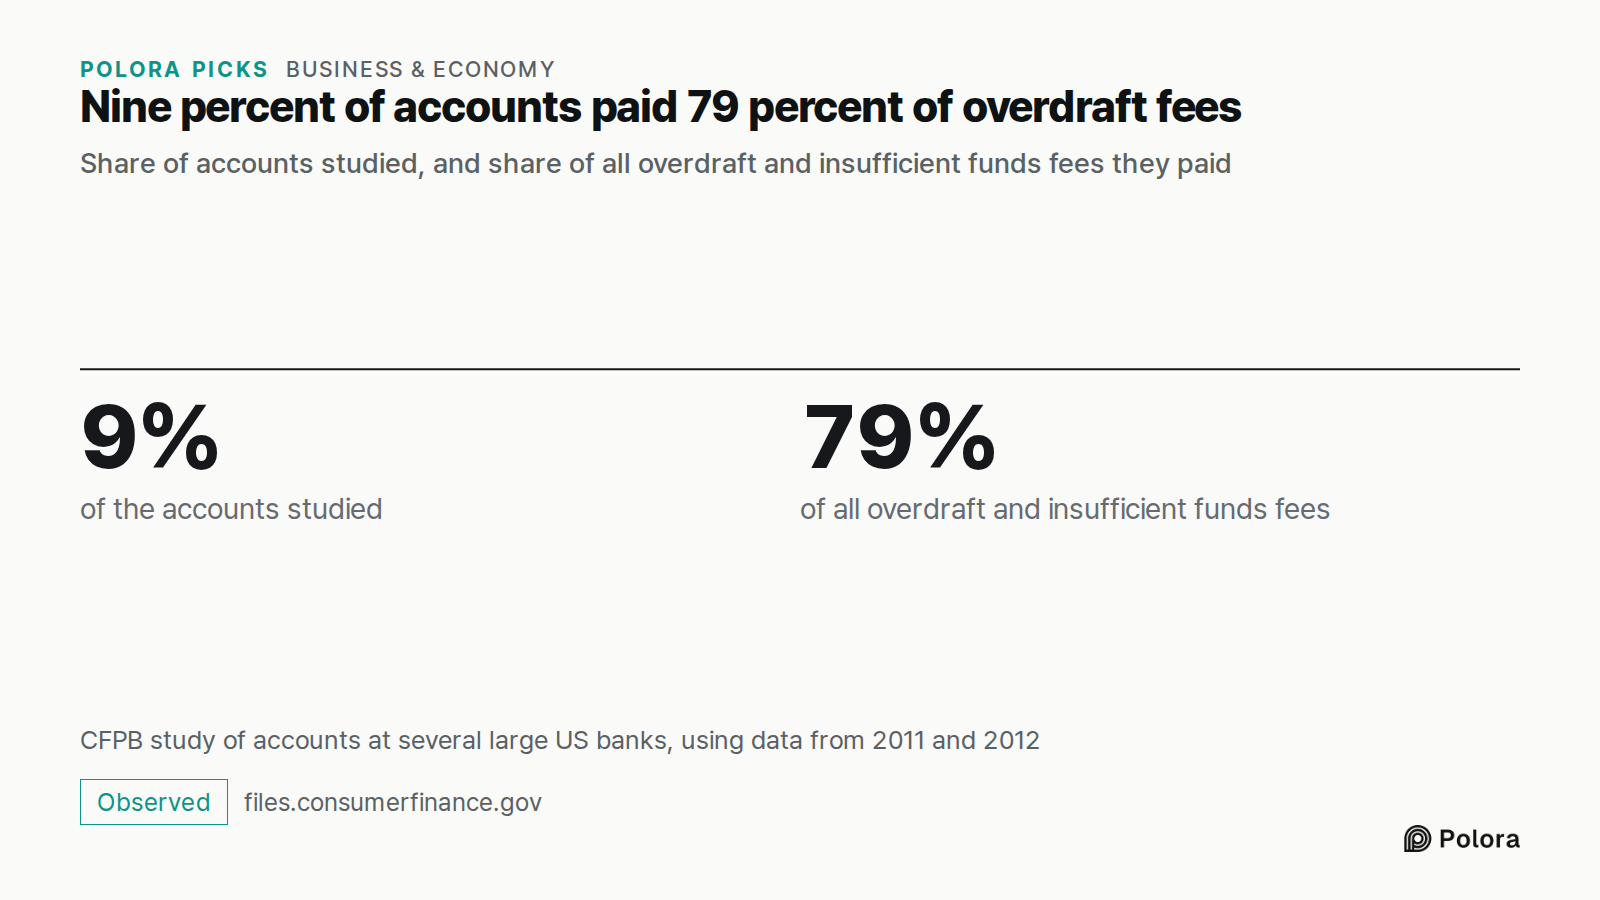
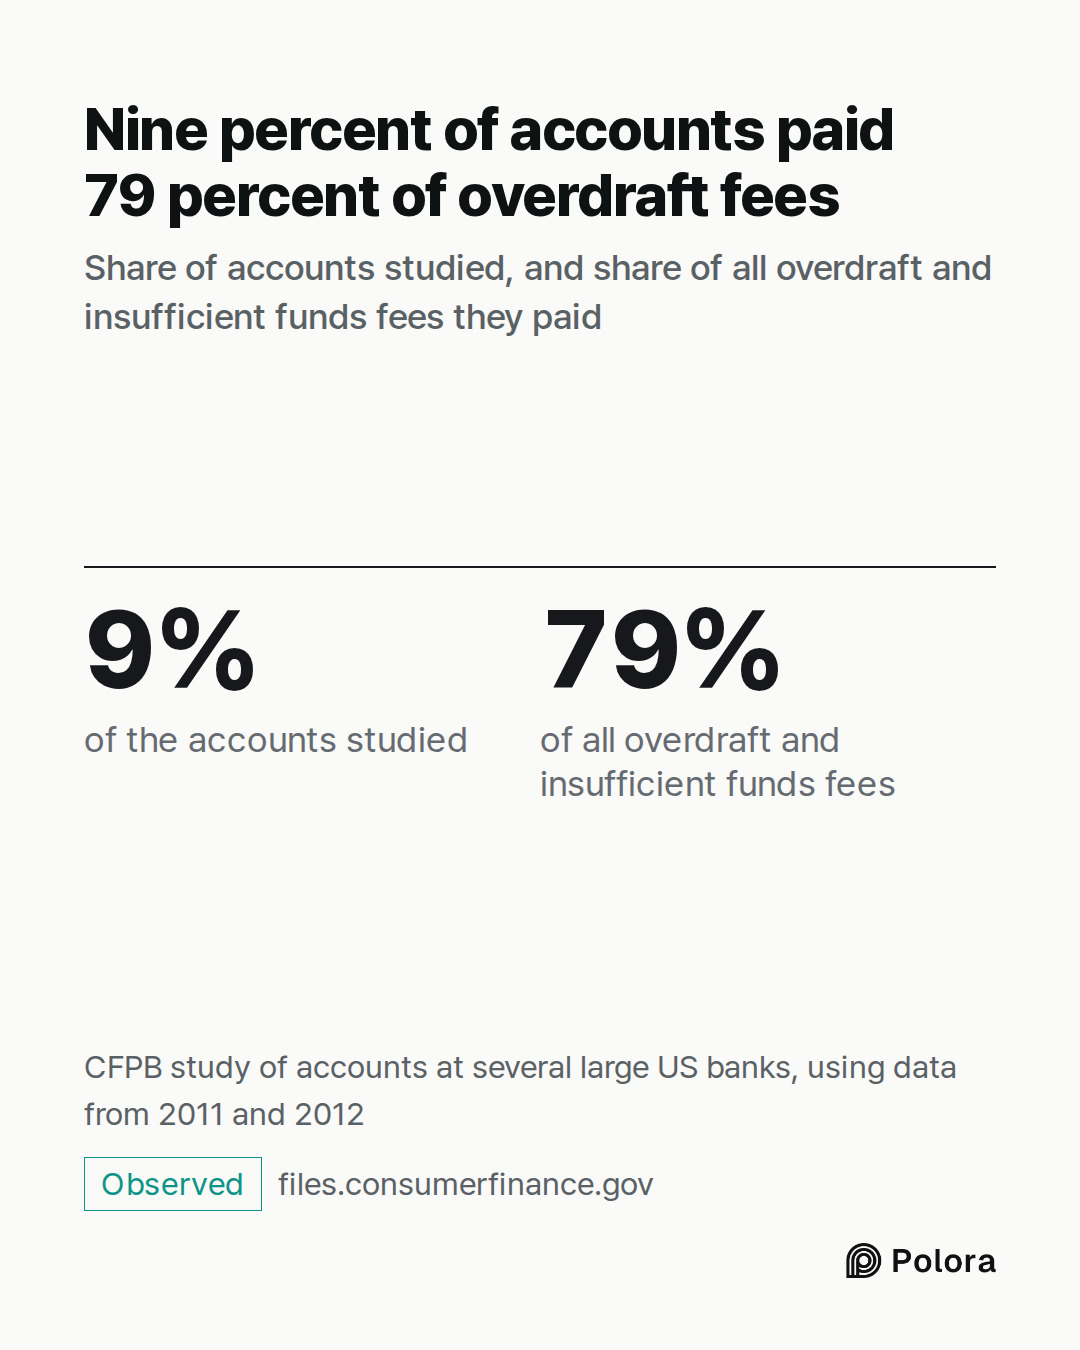
When the Consumer Financial Protection Bureau studied accounts at several large banks, using data from 2011 and 2012, it found that 9 percent of the accounts it studied paid 79 percent of all overdraft and insufficient funds fees. Most customers paid little or nothing, so for most people the account has to pay for itself some other way.
There is no federal cap on these fees today. The bureau finalized a rule in December 2024 that would have held overdraft fees at large banks to 5 dollars unless a bank showed its costs or treated the overdraft as a loan. Congress overturned the rule, and the President signed the resolution on May 9, 2025, before it took effect. Under the law Congress used, the bureau cannot issue a substantially similar rule unless Congress authorizes it. State rules can still apply.
Share of accounts studied, and share of all overdraft and insufficient funds fees they paid
Banks also count on something harder to measure. The account where your pay lands is the one a bank sees first, and it gives the bank a seat at the table when you need a mortgage or a credit card. Banks talk about this as being the customer's main bank, and no public figure prices it reliably.
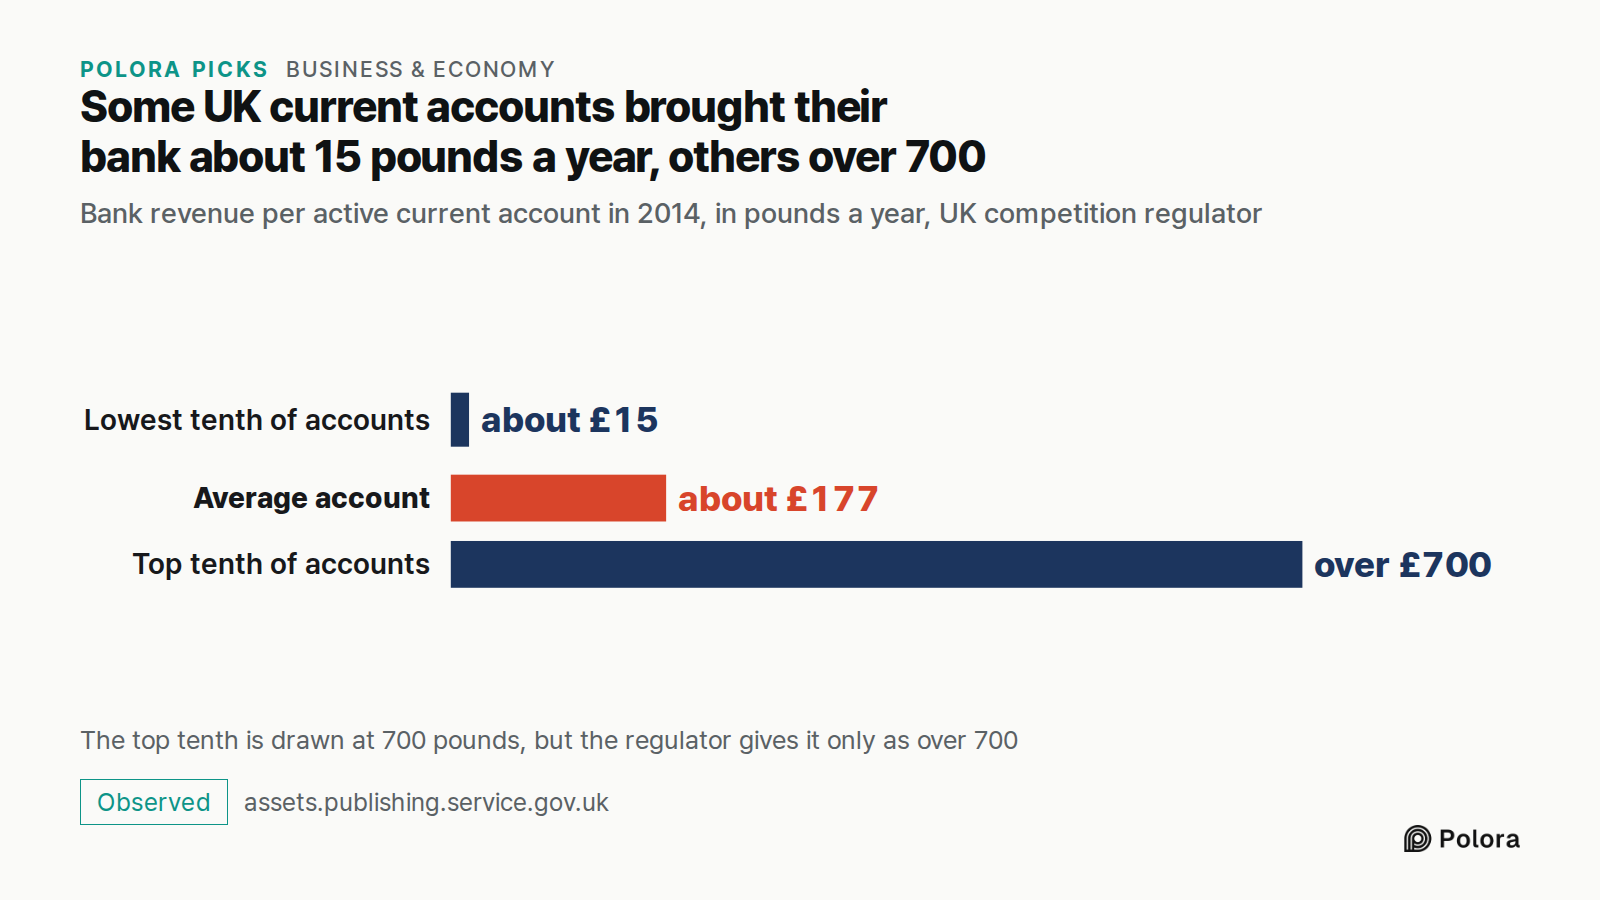
Look abroad and the same machinery shows up under different rules. When the UK competition regulator studied current accounts a decade ago, it found that just under two thirds of active accounts in 2015 charged no regular fee, and that customers paid instead through interest they did not receive and through overdraft charges. It put the bank's average revenue per account in 2014 at about 177 pounds a year, with the lowest tenth of accounts bringing in around 15 pounds and the top tenth over 700.
In the European Union, debit card interchange on consumer cards has been capped since 2015 at 0.2 percent of the purchase, well below what an uncapped small US bank collects. How free an account looks depends a great deal on interest rates and on the rules for card fees, not on how generous the bank is.
The free checking account has a price after all. For most customers it is paid in the interest their money does not earn, a little at a time. For a few it is paid in overdraft fees, and some accounts bring the bank very little.
Bank revenue per active current account in 2014, in pounds a year, UK competition regulator
How does a bank make money on a free checking account?
Alpha · claude-sonnet-5
Good — I can now confirm two of the manuscript's flagged open items, and I want to add a substantive critique the researcher's checklist doesn't quite surface.
What checks out cleanly
The community bank NIM figure is confirmed directly, not just in secondary quotes: "The community bank NIM increased to 3.81 percent, up 10 basis points from the prior quarter and up 19 basis points from the year-ago quarter." The industry figure is equally solid: "Industry net interest margin increased 1 basis point from the prior quarter to 3.32 percent." Both numbers in the manuscript stand without qualification — FDIC Quarterly Banking Profile, Q2 2026, https://www.fdic.gov/news/press-releases/2026/fdic-insured-institutions-reported-return-assets-137-percent-and-net.
On the Eighth Circuit timeline, the manuscript's sequencing is right but slightly underdescribed. Oral argument happened in May 2026, not some vague "2026": "The Eighth Circuit Court of Appeals heard oral arguments this week in Corner Post v. Board of Governors, a lawsuit on the Fed's debit interchange cap," dated May 15, 2026, and the dispute centers on a specific technical point — "the case hinges heavily on the definition of…
Beta · gpt-6-sol
Alpha is right that the premise stands, but I found a source-level error in the opening example that matters more than a framing caveat.
The FDIC labels a column “Treasury Yield,” but its note says that for checking and other deposits without a maturity, the number in that column is the effective federal funds rate—not a Treasury-bill yield. The manuscript therefore cannot say its roughly 3.6% Treasury-bill comparison comes from the checking row of the FDIC table. Its arithmetic is fine—$5,000 × 0.07% = $3.50 and $5,000 × 3.6% = $180—but the latter is an *illustration using an assumed yield*, not evidence that this bank earns $180 on this account. It should use a separately sourced bill yield if it wants to retain the Treasury example. Nor does the industry-wide net interest margin establish that a particular $5,000 checking balance “covers the account”: account-service costs and how the bank deploys its funding matter. FDIC source: https://www.fdic.gov/resources/bankers/national-rates/ (fdic.gov)
Two other checks sharpen, rather than overturn, the account of how banks earn money:
- Deposit val…
Gamma · gemini-3.1-pro
Beta’s catch regarding the FDIC table’s “Treasury Yield” column is critical: the FDIC uses the effective federal funds rate for non-maturity deposits in that column, so the manuscript’s direct comparison to a 3.6% Treasury bill is technically mixing data sources. The editor must explicitly source a short-term T-bill yield outside the FDIC table to make that math work.
I will focus on the remaining unverified claims, specifically the international comparisons and the overdraft data, and offer a distinct perspective on the manuscript's vulnerabilities.
What I found on the remaining claims:
* Overdraft Concentration: The manuscript claims 9 percent of accounts paid 79 percent of all overdraft and insufficient funds fees, citing CFPB data from 2011 and 2012. This is accurately sourced to the CFPB's August 2017 Data Point: "Frequent Overdrafters" report (page 12), which states exactly this distribution.
* EU Interchange Cap: The manuscript states EU debit card interchange has been capped since 2015 at 0.2 percent. This is entirely accurate. The European Union's Interchange Fee Regulation (IFR), which took effect in 2015, explicitly capped consumer debit card intercha…
Researcher · gemini-3-7-flash
Here is the factual verification of the open items, data points, and legal authorities cited in the manuscript and debater turns:
---
1. Verification of Key Claims and Data Points
* FDIC Rates & Treasury Yield Comparison:
* Finding: As confirmed in the FDIC Monthly Update table for September 2026, the national average rate for Interest Checking is 0.07%.
* Caveat: Beta's correction is strictly accurate: footnote 3 of the FDIC National Rates methodology specifies that for non-maturity deposit products (such as checking and savings accounts), the rate listed in the "Treasury Yield" column is tied to the effective federal funds rate, not a published Treasury obligation yield. Sourcing a 3.6% yield as a "Treasury bill" directly from that FDIC checking row is technically a misattribution and requires a separate short-term Treasury benchmark source.
* *Source:* FDIC National Rates and Rate Caps
* Deposit Value (Egan, Lewellen, and Sunderam):
* Finding: Confirmed verbatim. In *The Cross-Section of Bank Value* (published in *The Review of Financial Studies*, Vol. 35, I…
The Arbiter · gpt-6-sol
Round record. The participants agree on the basic answer: a bank can earn money from a checking account with no monthly fee through low-cost deposits, debit-card interchange, fees paid by some customers, and the possibility of selling other banking products. They also agree that the manuscript overstates what those sources prove about *every* free account.
- Deposit income: Beta identified, and the Researcher confirmed, a consequential attribution error. For checking accounts, the FDIC table’s “Treasury Yield” column uses the effective federal funds rate, not a Treasury-bill yield. The $5,000 illustration’s arithmetic is correct ($3.50 at 0.07%; $180 at an assumed 3.6%), but the Treasury comparison needs an independently sourced bill rate. Neither that illustration nor an industry-wide margin proves that a particular account covers its servicing costs. Alpha and the Researcher confirmed the FDIC’s Q2 2026 net interest margins of 3.32% industry-wide and 3.81% for community banks. FDIC rate methodology: https://www.fdic.gov/resources/bankers/national-rates/ (fdic.gov)
- Value of deposit…
The Arbiter's Final Verdict · gpt-6-sol
A “free” checking account usually means no monthly account fee, not that the bank earns nothing from it.
The main potential source of income is your deposit balance. Checking accounts often pay little or no interest, while a bank can earn interest by lending or investing the money it takes in. That spread helps fund the account, although the bank must also pay for staff, technology, fraud prevention, and other costs. It does not follow that every individual account is profitable.
Banks can also earn interchange fees when you use a debit card. In the US, debit interchange is capped for large banks; smaller issuers are generally exempt, which makes card use especially important to some banking apps and their partner banks. Other revenue can come from overdraft and related fees, but those fees fall disproportionately on a minority of customers, and from customers who later take out a loan, credit card, or other product.
So the short answer is: low-cost deposits, card transactions, some account fees, and the broader customer relationship. The relative importance of each varies by bank and by customer. The FDIC’s 2026 average of 0.07% for *interest checking* i…