What is being counted
When a company or a fund sells securities without registering them, under the exemptions of the SEC's Regulation D, it must file a short notice with the SEC called a Form D. The notice is due within 15 days of the first sale. A pooled investment fund ticks a box on it for what kind of fund it is. One of the boxes is "Venture Capital Fund". The SEC publishes the content of these notices as quarterly data sets.
This piece counts every new Form D notice whose issuer ticked "Venture Capital Fund", from the start of 2010 to the end of September 2026, by the quarter it was filed. Amendments to earlier notices are left out, so the count is of first notices, not of updates to them. It then splits those notices by the issuer's name. A name that contains "a series of", "SPV", "series" followed by another word or a number (as in "Series A"), or "co-invest" counts as a one-deal name. Every other name counts as an other name. A handful of notices were filed with a blank name; two of them take the name the same issuer used on its other notices, and the rest count as other names. The counts were checked against a second SEC publication, the EDGAR filing index, which lists each notice's date and name separately from the data sets. The two agree to within a few notices a quarter, mostly because the index cuts long names short. The index does not carry the fund-type box, so which notices count as venture funds rests on the data sets alone.
What a one-deal vehicle is
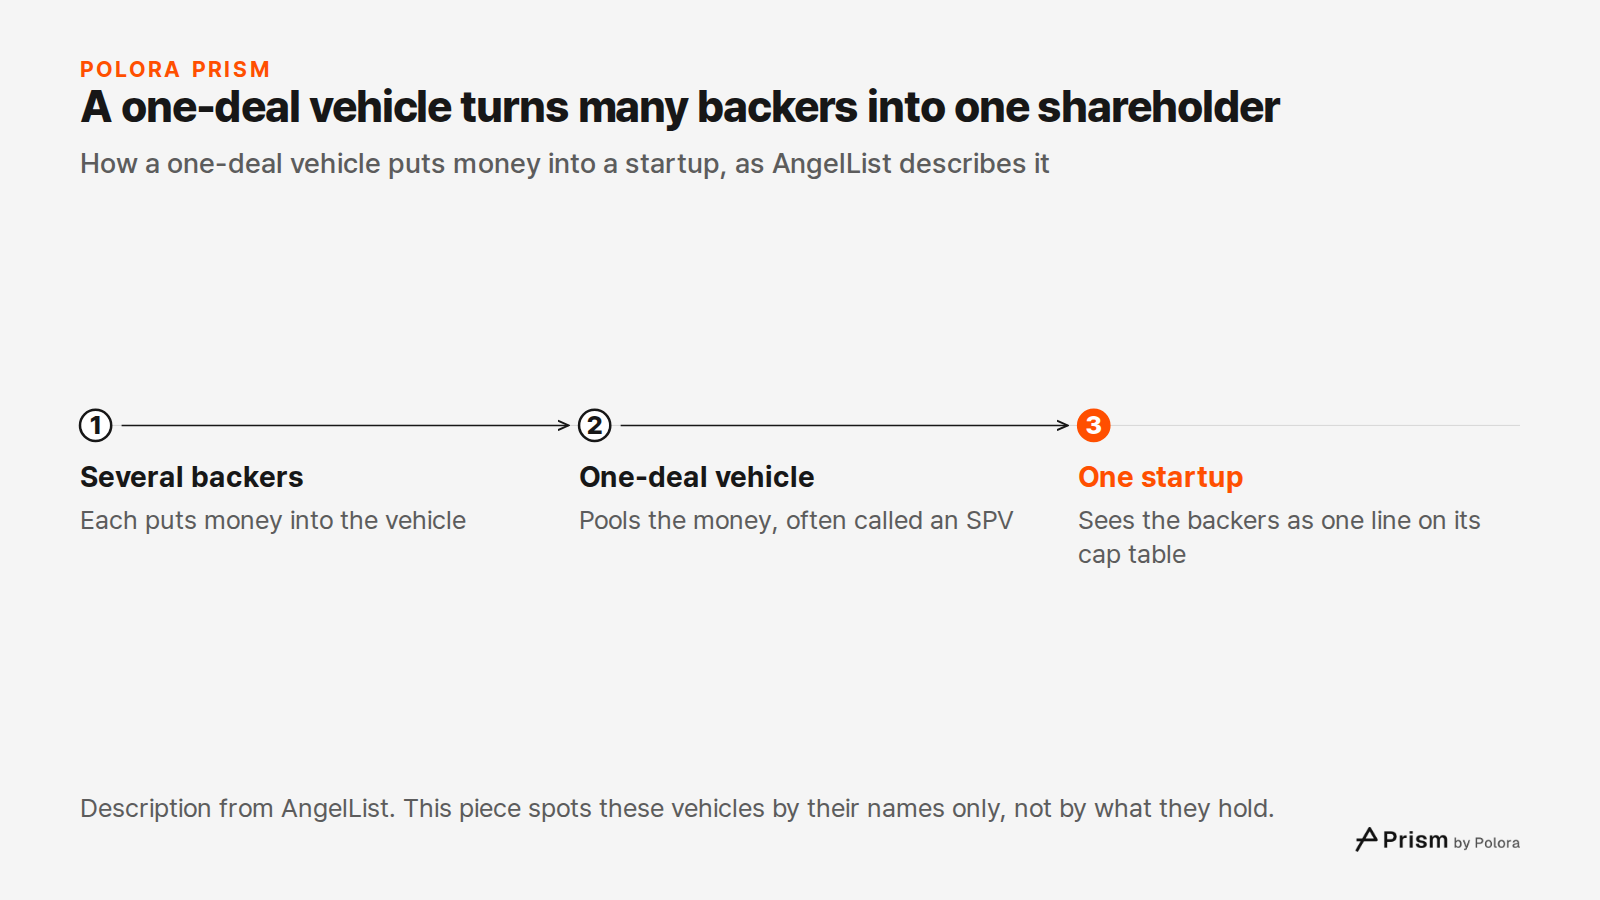
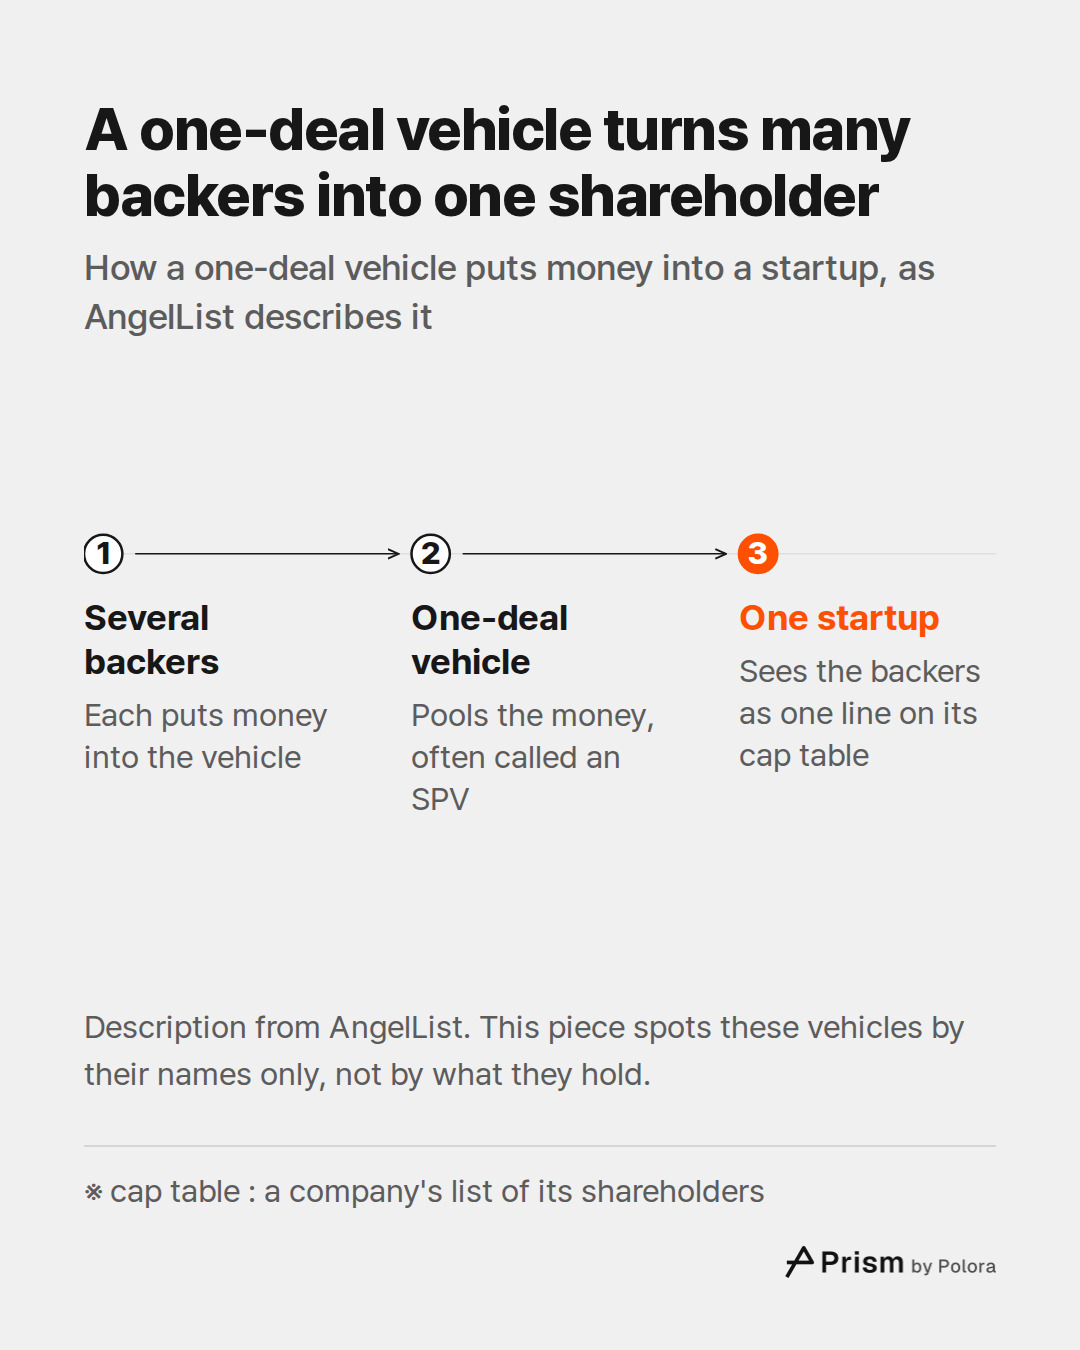
A one-deal vehicle pools money from several backers and puts it into a single startup. AngelList, the online platform for startup investors, describes how this looks from the company's side : investors follow a link, put money into a special purpose vehicle (SPV), and the vehicle then invests in the company, so the backers show up as one line on the company's list of shareholders, its cap table.
The names are the clue this piece uses to spot them. According to a guide to forming SPVs published by Hemrock, AngelList forms each deal as a series of one master Delaware limited partnership, and Sydecar uses series of one master LLC. That is why so many of these notices read like "XX Fund I, a series of" some master fund. The name rule catches that pattern, but it is a rule of thumb that can miss in either direction : a co-investment fund can hold several companies, "series" followed by a word can be part of a plain fund name, and a single-deal vehicle can carry a plain name. Nobody checked what each vehicle actually holds.
2010 to 2018 : a small share
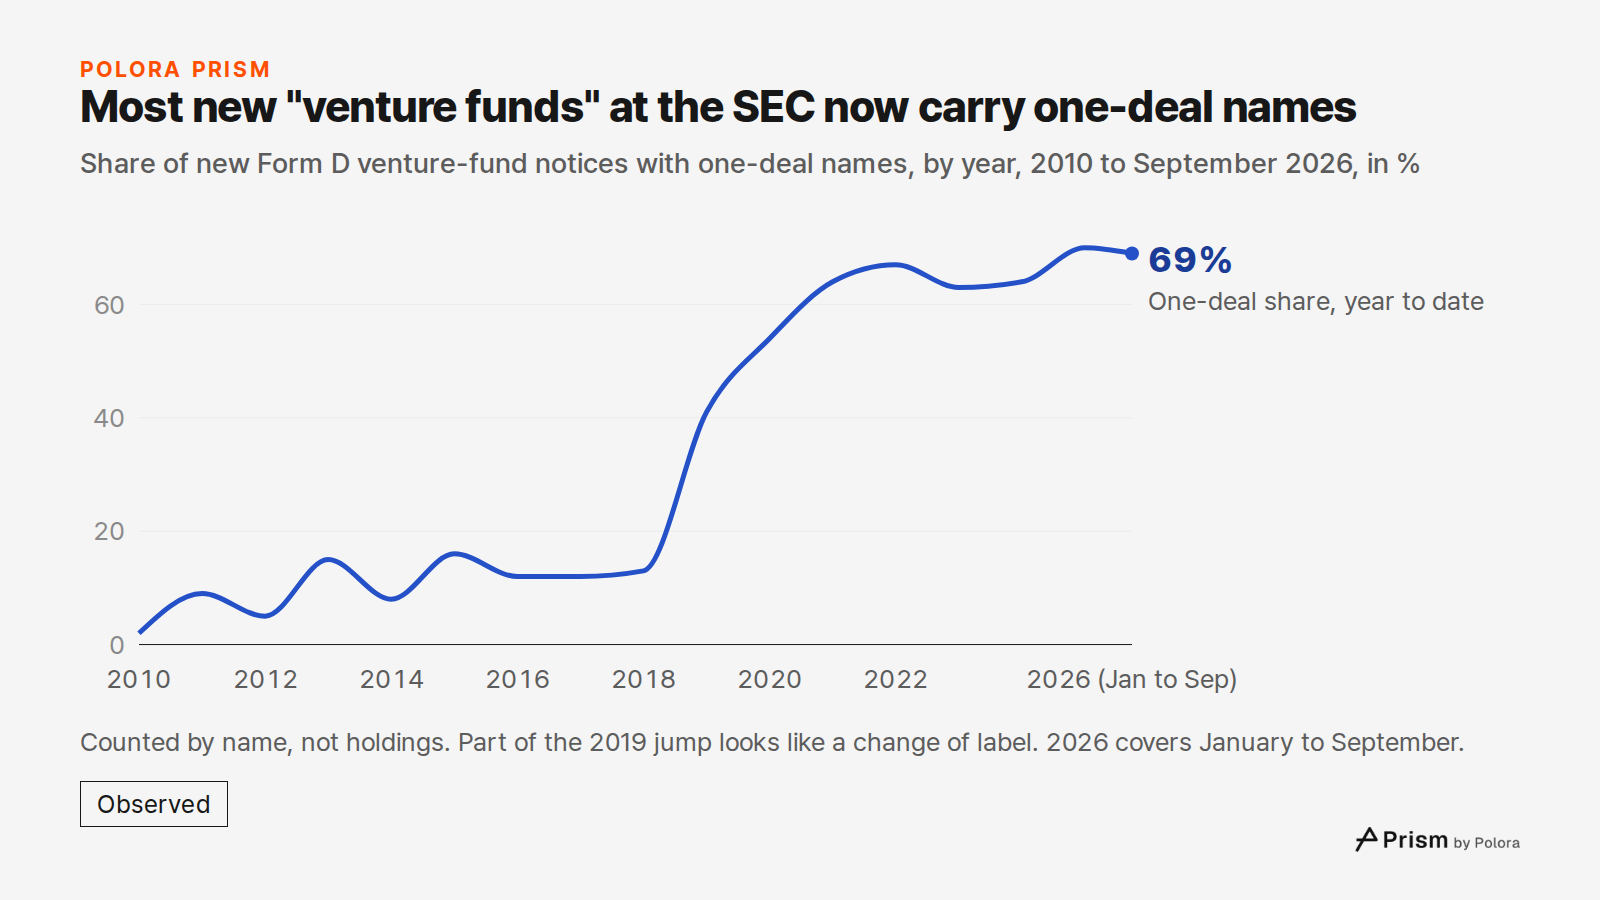
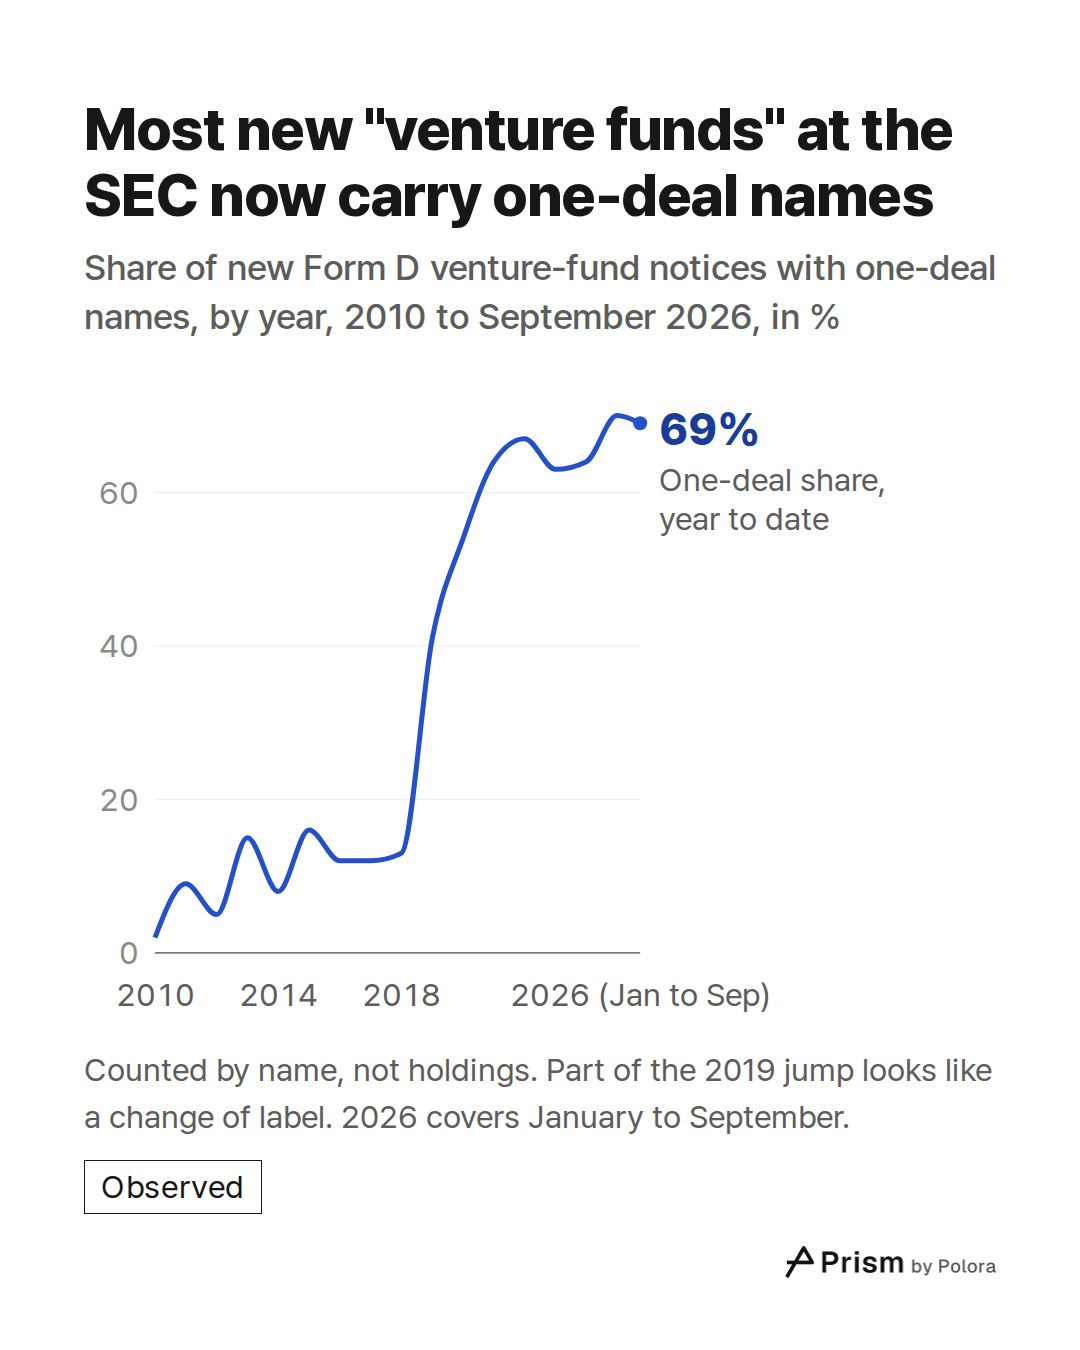
For most of the 2010s, one-deal names were a thin layer among venture funds. In 2010 they were 2.2% of new venture-fund notices; in 2018, 12.6%, or 160 notices.
2019 : a new label as well as new vehicles
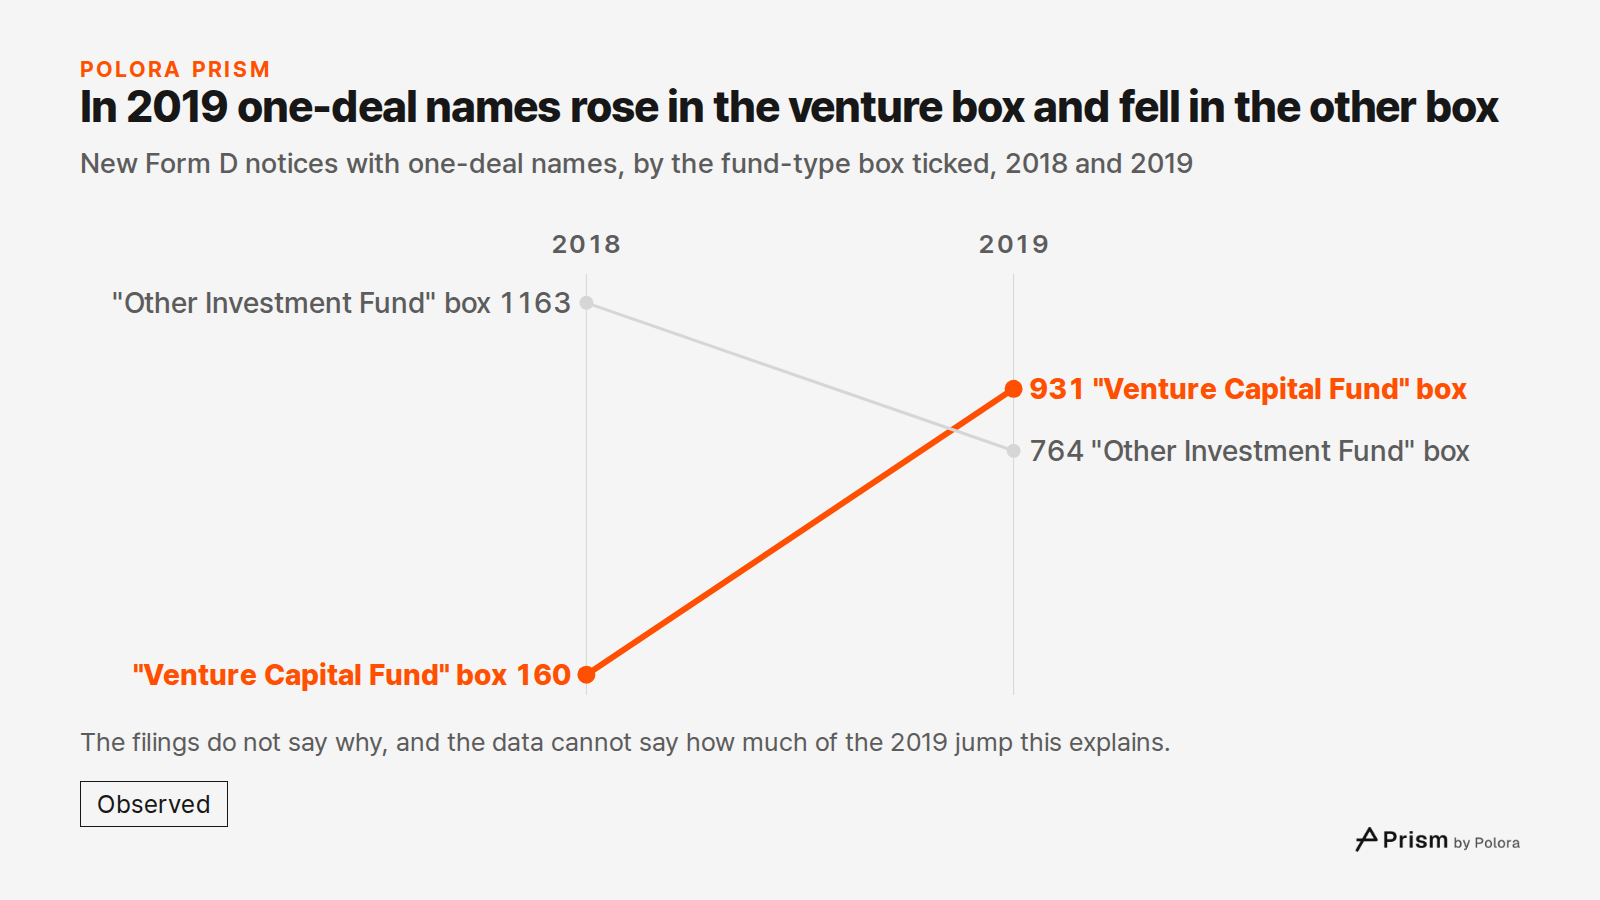
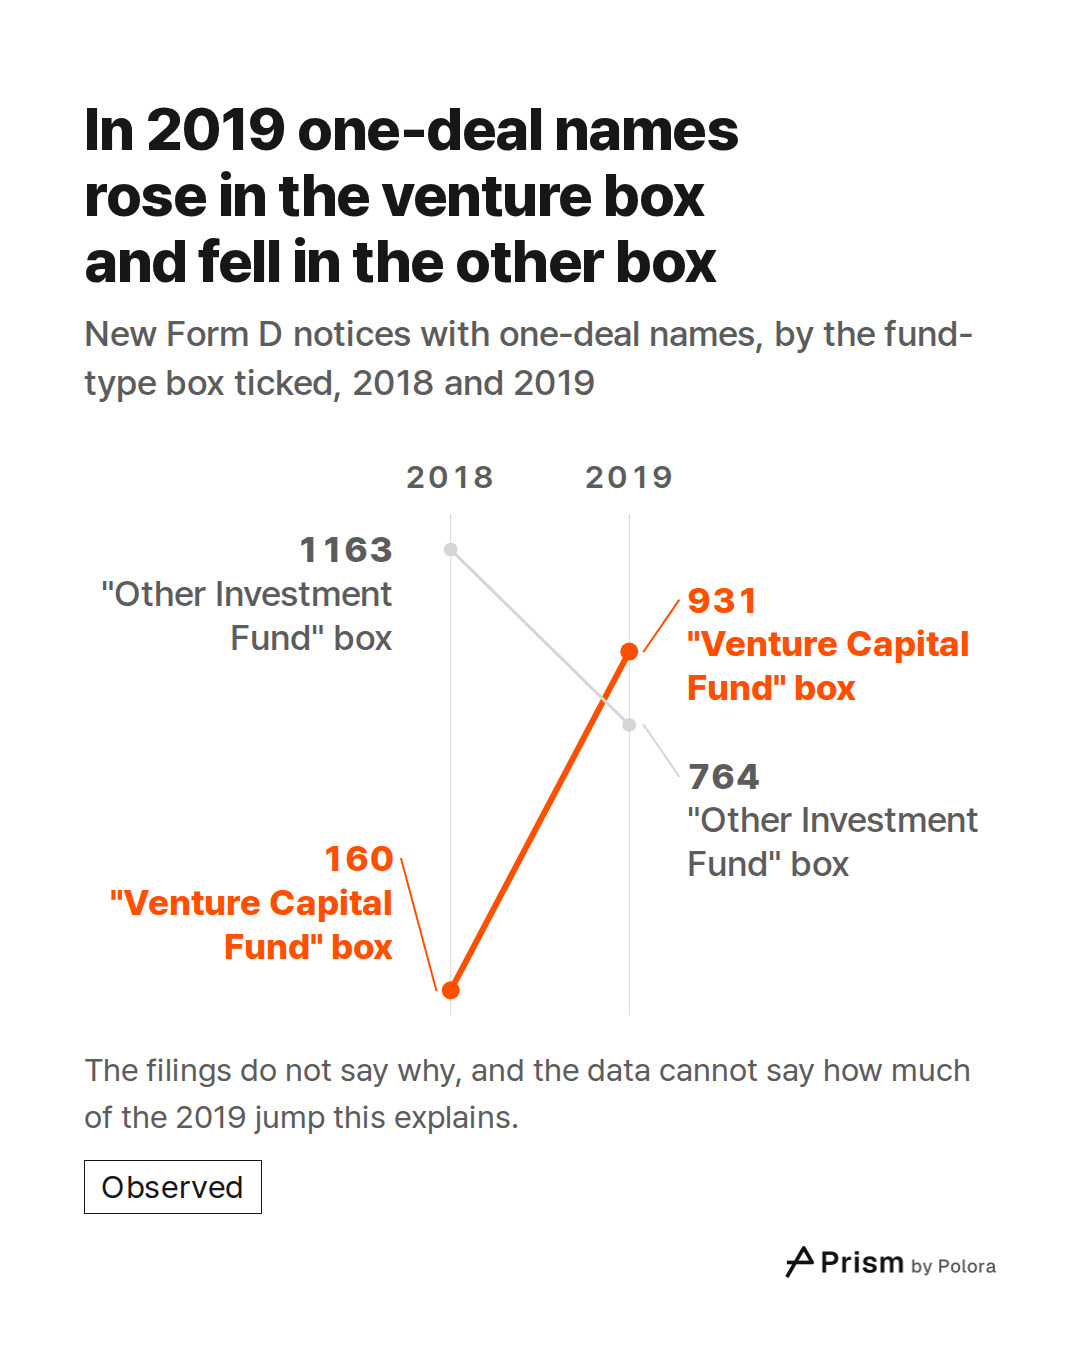
The share leapt in 2019, and part of that leap looks like a new label rather than new vehicles. The same kind of vehicle can be filed under a different box, "Other Investment Fund". Some master funds whose one-deal vehicles had all been filed in that box in 2018 had their new vehicles filed as venture funds in 2019. One-deal names in the venture box went from 160 in 2018 to 931 in 2019, while one-deal names in the "other" box fell from 1,163 to 764.
That pattern points to a change in which box some platforms tick, but the filings do not say why, and the data cannot say how much of the 2019 jump it explains. The rise in one-deal names is still there when both boxes are counted together : they were 3% of new notices across the two boxes in 2010, 30% in 2018 and 55% in 2025. That combined count is rougher, because the "other" box also holds some portfolios outside startups whose names happen to match the rule.
2020 and 2021 : the boom
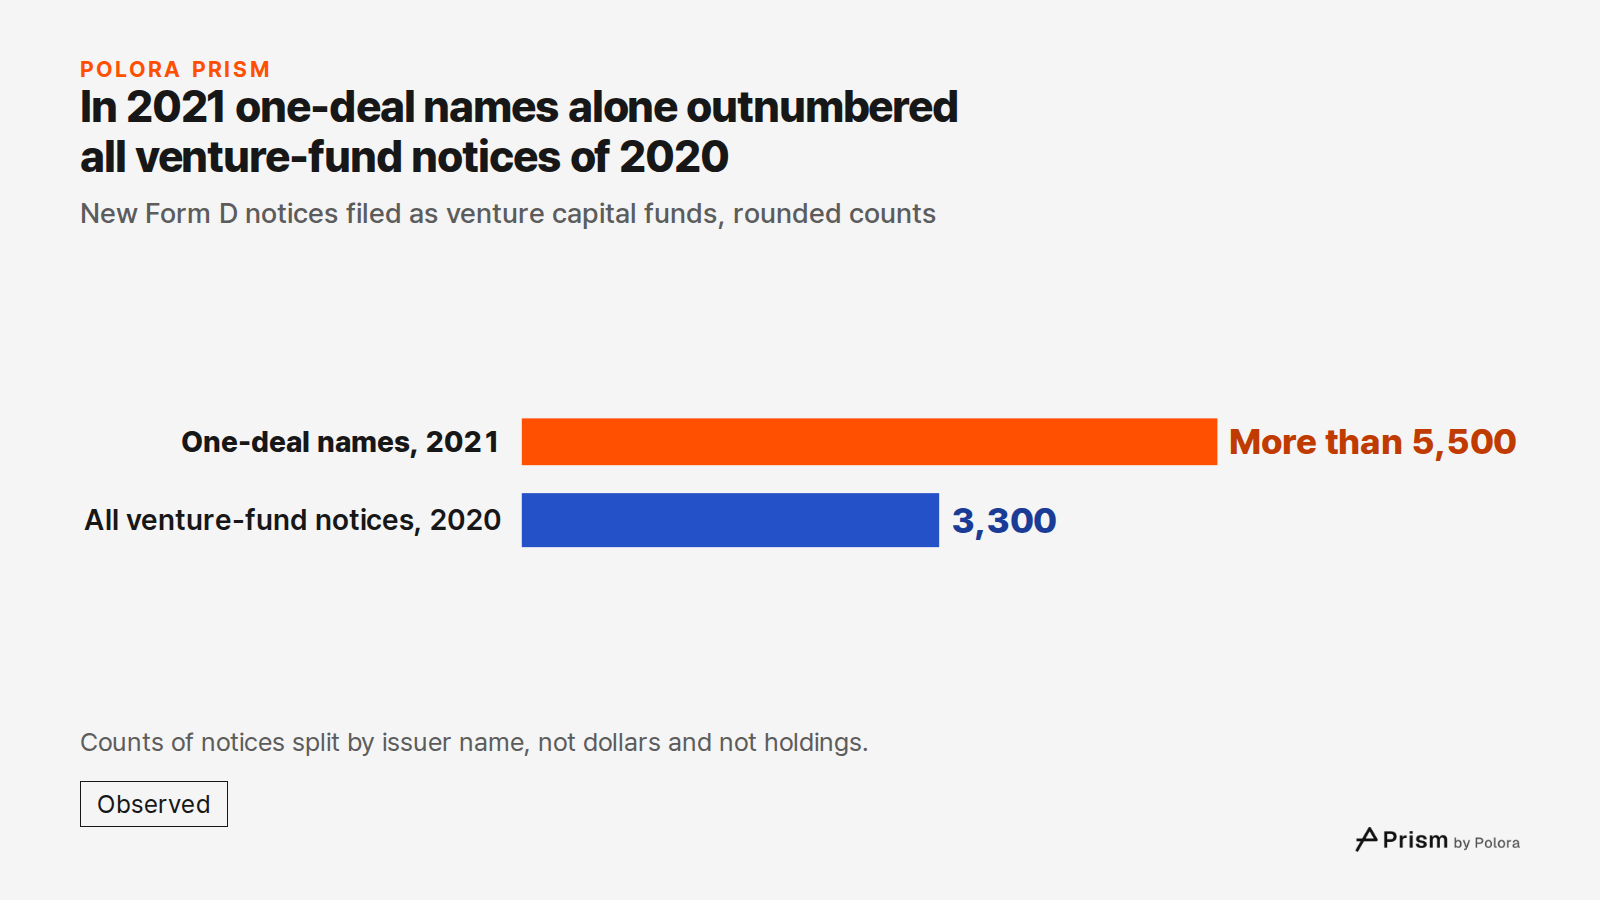
Then came the boom. In 2021, more than 5,500 new venture-fund notices carried one-deal names, more than all 3,300 new venture-fund notices of every kind in 2020. By 2021 AngelList was offering founders "roll up vehicles", which, as TechCrunch and AngelList's own case study both describe, let a founder bring many angel investors into a round as a single line on the cap table. That shows the product existed then. It does not measure how much of the boom it accounts for.
2022 to 2024 : off the peak, same split
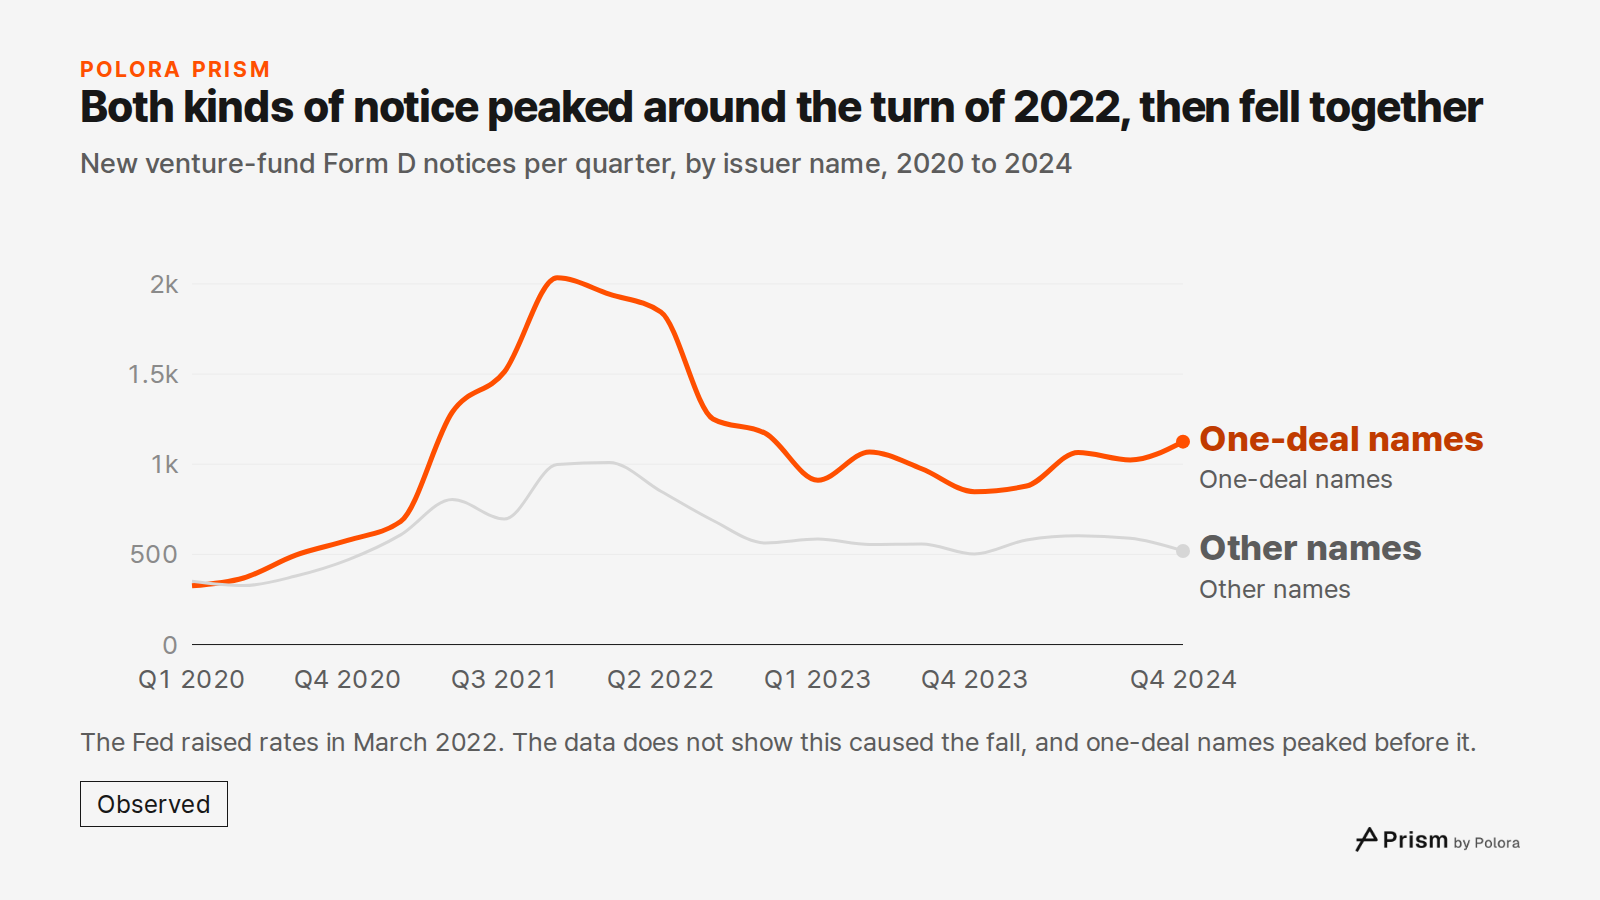
Notices with one-deal names peaked at 2,034 in the last quarter of 2021; other names peaked at 1,010 in the first quarter of 2022. Both then fell. In March 2022 the Federal Reserve raised the target range for its policy rate, the federal funds rate. The fall followed, but the data does not show the rate rise caused it, and one-deal names had already passed their quarterly peak before the decision.
Two things put the fall in proportion. Counted over whole years, there were more new venture-fund notices in 2022 (9,319) than in 2021 (8,623), because the strong start of 2022 outweighed its weak end. And the split hardly moved : in each year from 2021 to 2024, one-deal names were between 63% and 67% of new venture-fund notices.
2025 and 2026 : busier again
Filing picked up again in 2025, to about 7,400 new venture-fund notices. In the first nine months of 2026 there were already 7,300, nearly as many as in all of 2025, and 69% of them carried one-deal names.
What this does and does not show
These are counts of notices, not dollars. A small vehicle and a large fund each count as one notice. Notices with one-deal names tend to report small sums. Among the 2025 venture-fund notices with one-deal names, the median amount sold was $250,000. That is the amount each notice reported as sold when it was filed, which is meant to be soon after the first sale, so a vehicle can end up larger than its first notice says. The SEC also cautions that its Form D data sets come from what filers report, and it cannot guarantee their accuracy.
What the count does show is a change in what fills the "Venture Capital Fund" box. A reader who sees a rising number of new venture funds in Form D filings is now mostly looking at notices whose names mark them as one-deal vehicles. The names do not prove what each vehicle holds, and a new notice is not the same as a new fund manager. It says nothing about how venture investments will perform.
- SEC, Form D Data Sets]
- SEC, EDGAR full index of filings by form type]
- SEC, Filing a Form D Notice]
- AngelList, How Rootly's Founders Used a Roll Up Vehicle to Add Strategic Angels to Their Seed Round (August 12, 2021)]
- TechCrunch, AngelList returns to its founder-focused roots, with a twist (September 28, 2021)]
- Hemrock, SPV Formation: Entity, Documents, Cost, and Timeline]
- Federal Reserve, FOMC statement of March 16, 2022]
![Sources 7 : sec.gov · SEC, Form D Data Sets], sec.gov · SEC, EDGAR full index of filings by form type], sec.gov · SEC, Filing a Form D Notice] + 4](https://media.cdn.polora.ai/picks/2026/11/pickrun_2c524a6e763b4b12/ZpxiF1JHwSNYxyuc-slide-08--are-most-new-venture.jpg)